3 Reasons to Avoid PLUS and 1 Stock to Buy Instead
Over the last six months, ePlus’s shares have sunk to $68.52, producing a disappointing 15.7% loss - a stark contrast to the S&P 500’s 4.3% gain. This may have investors wondering how to approach the situation.
Is now the time to buy ePlus, or should you be careful about including it in your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Do We Think ePlus Will Underperform?
Even with the cheaper entry price, we don't have much confidence in ePlus. Here are three reasons why we avoid PLUS and a stock we'd rather own.
1. Long-Term Revenue Growth Disappoints
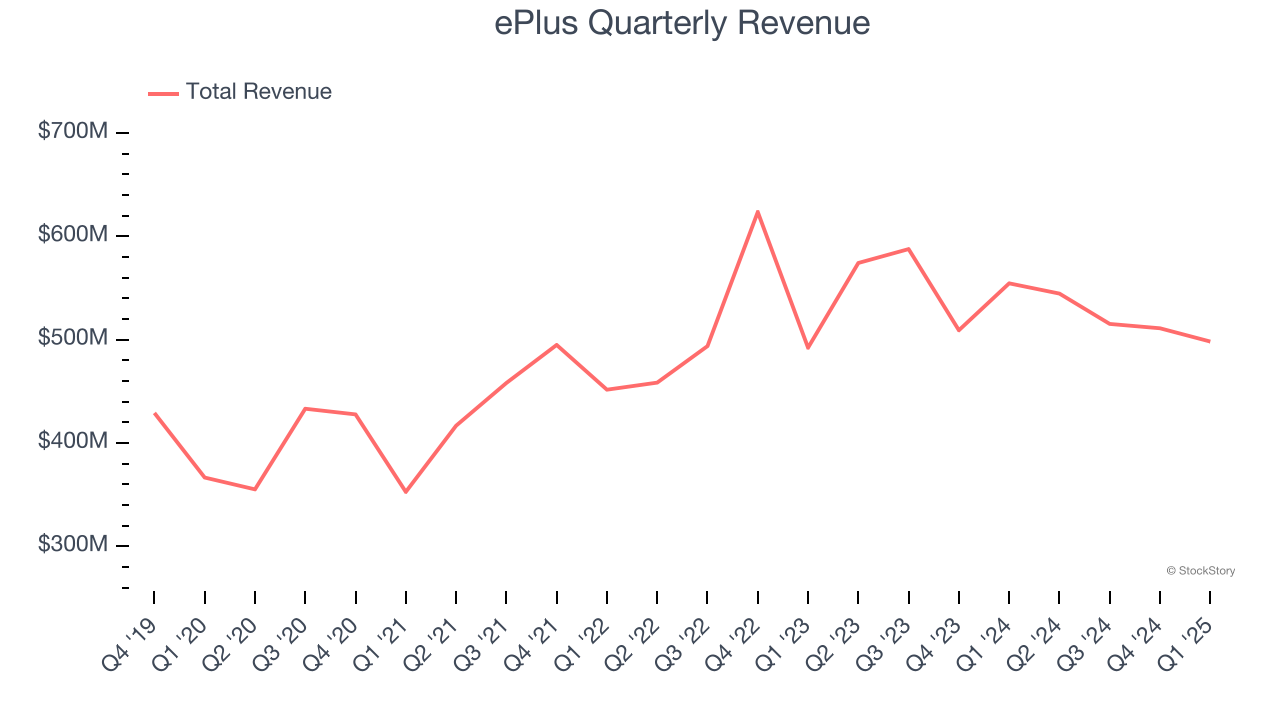
Examining a company’s long-term performance can provide clues about its quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Unfortunately, ePlus’s 4.9% annualized revenue growth over the last five years was mediocre. This fell short of our benchmark for the business services sector.
2. EPS Took a Dip Over the Last Two Years
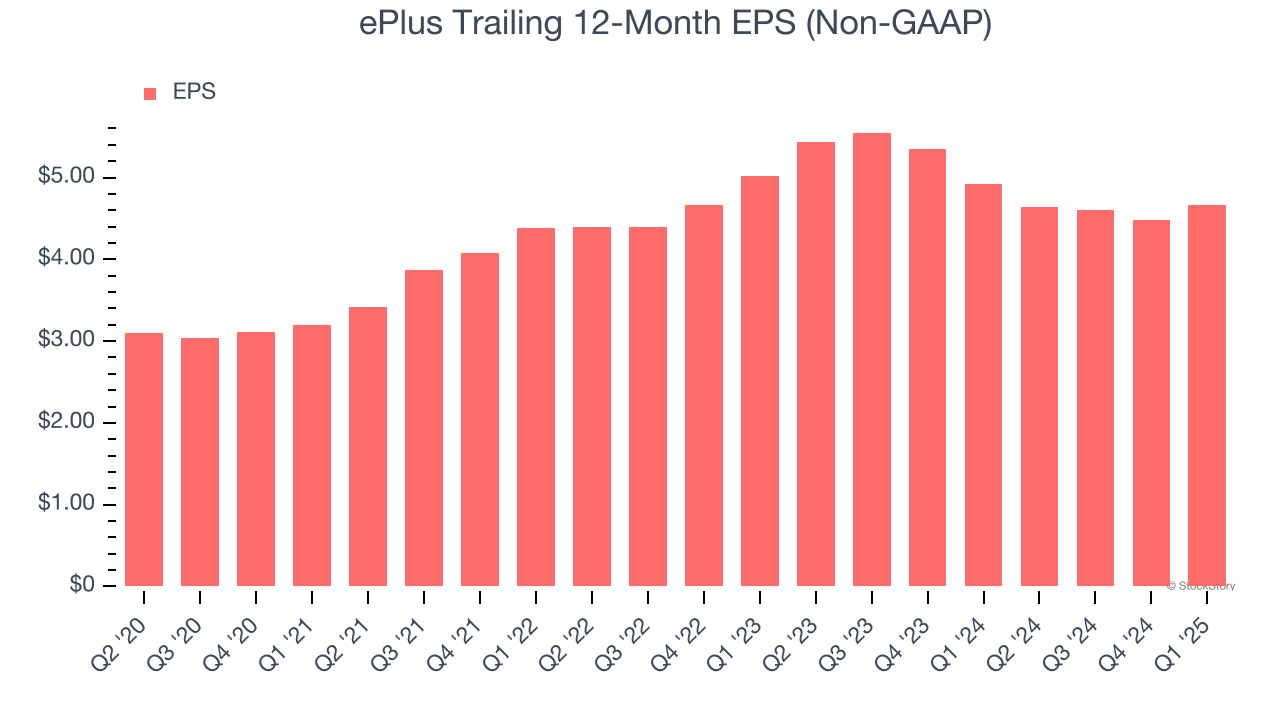
While long-term earnings trends give us the big picture, we also track EPS over a shorter period because it can provide insight into an emerging theme or development for the business.
Sadly for ePlus, its EPS declined by 3.7% annually over the last two years while its revenue was flat. This tells us the company struggled to adjust to choppy demand.
3. Previous Growth Initiatives Haven’t Impressed
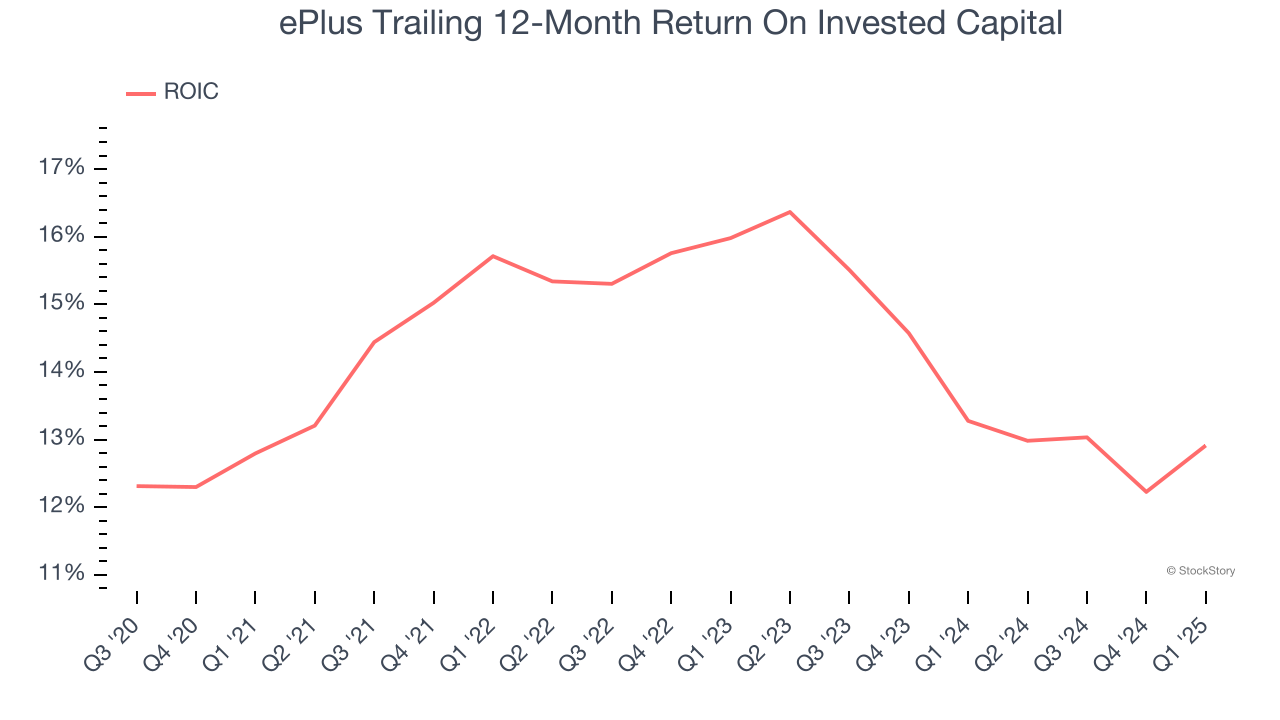
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? A company’s ROIC explains this by showing how much operating profit it makes compared to the money it has raised (debt and equity).
ePlus historically did a mediocre job investing in profitable growth initiatives. Its five-year average ROIC was 14.1%, somewhat low compared to the best business services companies that consistently pump out 25%+.
Final Judgment
We see the value of companies helping their customers, but in the case of ePlus, we’re out. Following the recent decline, the stock trades at 14.7× forward P/E (or $68.52 per share). At this valuation, there’s a lot of good news priced in - we think there are better stocks to buy right now. We’d recommend looking at a top digital advertising platform riding the creator economy.
High-Quality Stocks for All Market Conditions
Donald Trump’s April 2024 "Liberation Day" tariffs sent markets into a tailspin, but stocks have since rebounded strongly, proving that knee-jerk reactions often create the best buying opportunities.
The smart money is already positioning for the next leg up. Don’t miss out on the recovery - check out our Top 9 Market-Beating Stocks. This is a curated list of our High Quality stocks that have generated a market-beating return of 183% over the last five years (as of March 31st 2025).
Stocks that made our list in 2020 include now familiar names such as Nvidia (+1,545% between March 2020 and March 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+354% five-year return). Find your next big winner with StockStory today.
StockStory is growing and hiring equity analyst and marketing roles. Are you a 0 to 1 builder passionate about the markets and AI? See the open roles here.
Mentioned In This Article
Latest News
| Sep-02 | |
| Aug-24 | |
| Aug-05 | |
| Aug-04 | |
| Jul-28 | |
| Jul-21 | |
| Jul-06 | |
| Jul-01 | |
| Jun-30 | |
| Jun-25 | |
| Jun-23 | |
| Jun-22 | |
| Jun-17 | |
| Jun-16 | |
| Jun-03 |
