Cars.com's (NYSE:CARS) Q2 Earnings Results: Revenue In Line With Expectations But Stock Drops 15.1%
Online new and used car marketplace Cars.com (NYSE:CARS) met Wall Street’s revenue expectations in Q2 CY2025, but sales were flat year on year at $178.7 million. Its non-GAAP profit of $0.41 per share was in line with analysts’ consensus estimates.
Is now the time to buy Cars.com? Find out by accessing our full research report, it’s free.
Cars.com (CARS) Q2 CY2025 Highlights:
- Revenue: $178.7 million vs analyst estimates of $179.2 million (flat year on year, in line)
- Adjusted EPS: $0.41 vs analyst estimates of $0.42 (in line)
- Adjusted EBITDA: $50.9 million vs analyst estimates of $50.21 million (28.5% margin, 1.4% beat)
- Operating Margin: 8.5%, up from 5.3% in the same quarter last year
- Free Cash Flow Margin: 10.2%, down from 13.2% in the previous quarter
- Dealer Customers: 19,412, in line with the same quarter last year
- Market Capitalization: $825.7 million
Company Overview
Originally started as a joint venture between several media companies including The Washington Post and The New York Times, Cars.com (NYSE:CARS) is a digital marketplace that connects new and used car buyers and sellers.
Revenue Growth
A company’s long-term sales performance can indicate its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Regrettably, Cars.com’s sales grew at a sluggish 4.1% compounded annual growth rate over the last three years. This was below our standard for the consumer internet sector and is a poor baseline for our analysis.
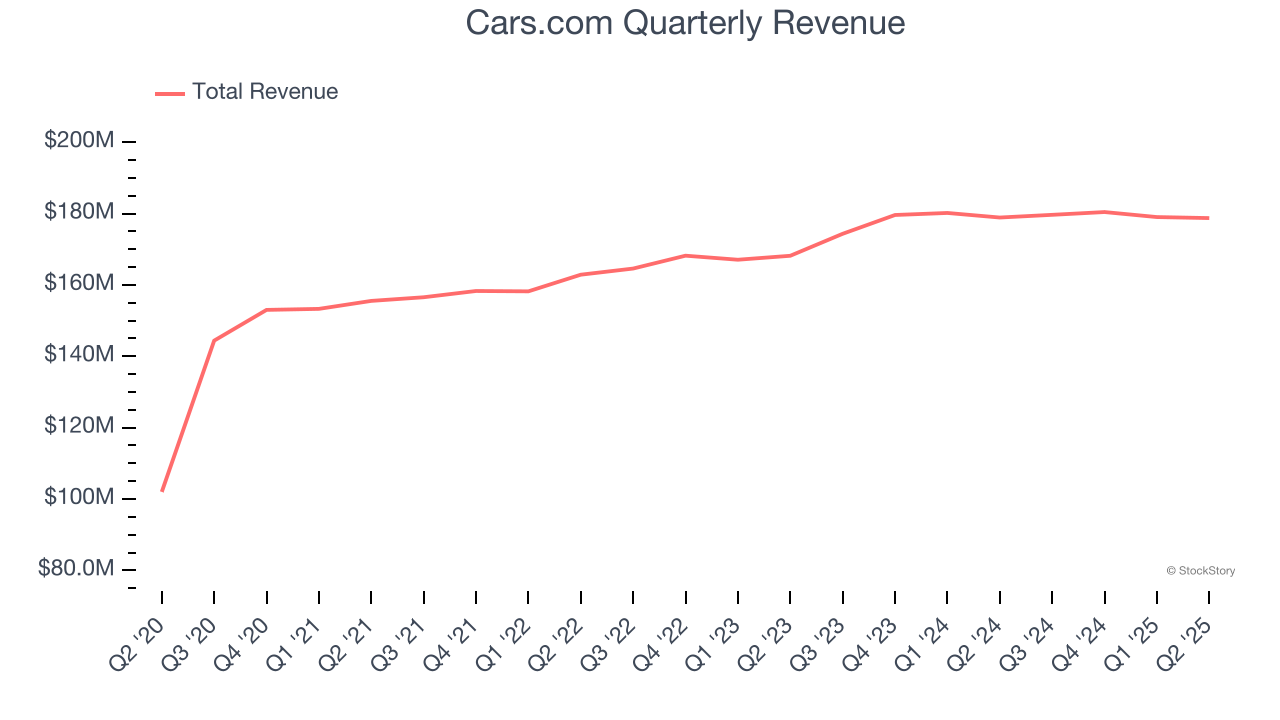
This quarter, Cars.com’s $178.7 million of revenue was flat year on year and in line with Wall Street’s estimates.
Looking ahead, sell-side analysts expect revenue to grow 2.5% over the next 12 months, a slight deceleration versus the last three years. This projection doesn't excite us and suggests its products and services will see some demand headwinds.
Here at StockStory, we certainly understand the potential of thematic investing. Diverse winners from Microsoft (MSFT) to Alphabet (GOOG), Coca-Cola (KO) to Monster Beverage (MNST) could all have been identified as promising growth stories with a megatrend driving the growth. So, in that spirit, we’ve identified a relatively under-the-radar profitable growth stock benefiting from the rise of AI, available to you FREE via this link.
Dealer Customers
Buyer Growth
As an online marketplace, Cars.com generates revenue growth by increasing both the number of users on its platform and the average order size in dollars.
Cars.com struggled with new customer acquisition over the last two years as its dealer customers were flat at 19,412. This performance isn't ideal because internet usage is secular, meaning there are typically unaddressed market opportunities. If Cars.com wants to accelerate growth, it likely needs to enhance the appeal of its current offerings or innovate with new products.
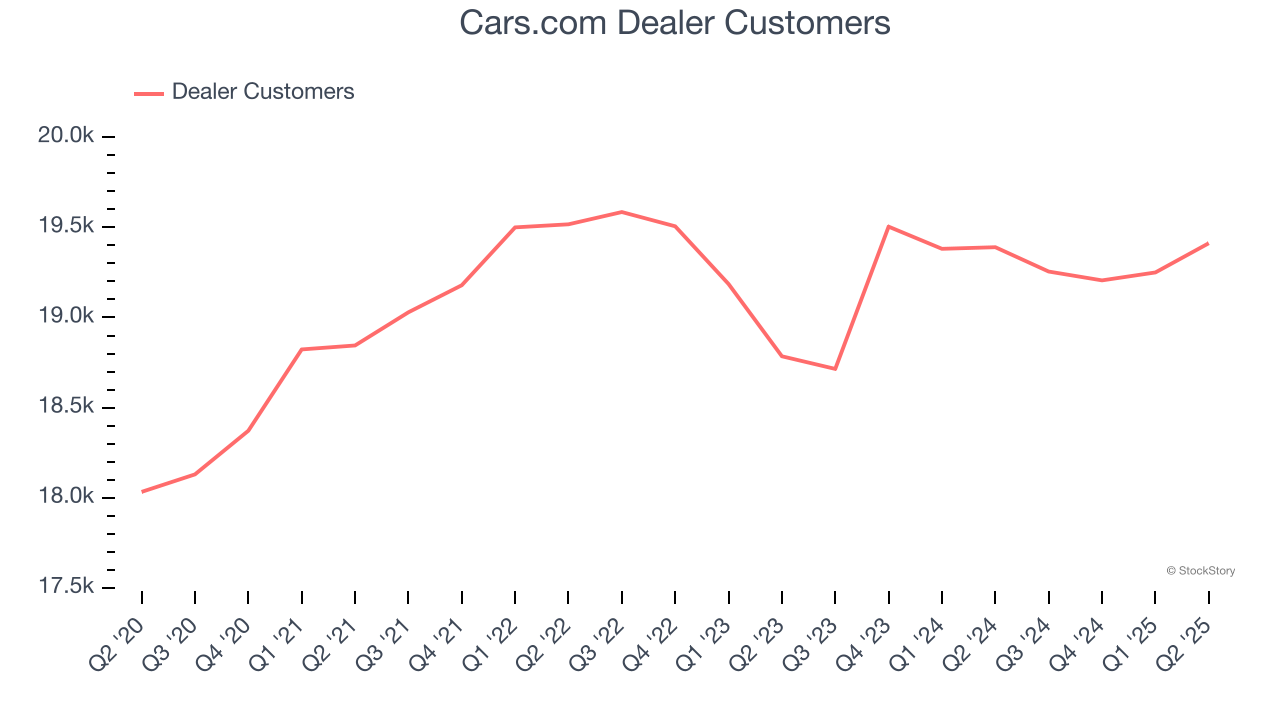
Unfortunately, Cars.com’s dealer customers were once again flat year on year in Q2. The quarterly print isn’t too different from its two-year result, suggesting its new initiatives aren’t accelerating buyer growth just yet.
Revenue Per Buyer
Average revenue per buyer (ARPB) is a critical metric to track because it measures how much the company earns in transaction fees from each buyer. ARPB also gives us unique insights into a user’s average order size and Cars.com’s take rate, or "cut", on each order.
Cars.com’s ARPB growth has been subpar over the last two years, averaging 1.7%. This raises questions about its platform’s health when paired with its flat dealer customers. If Cars.com wants to grow its buyers, it must either develop new features or lower its monetization of existing ones.
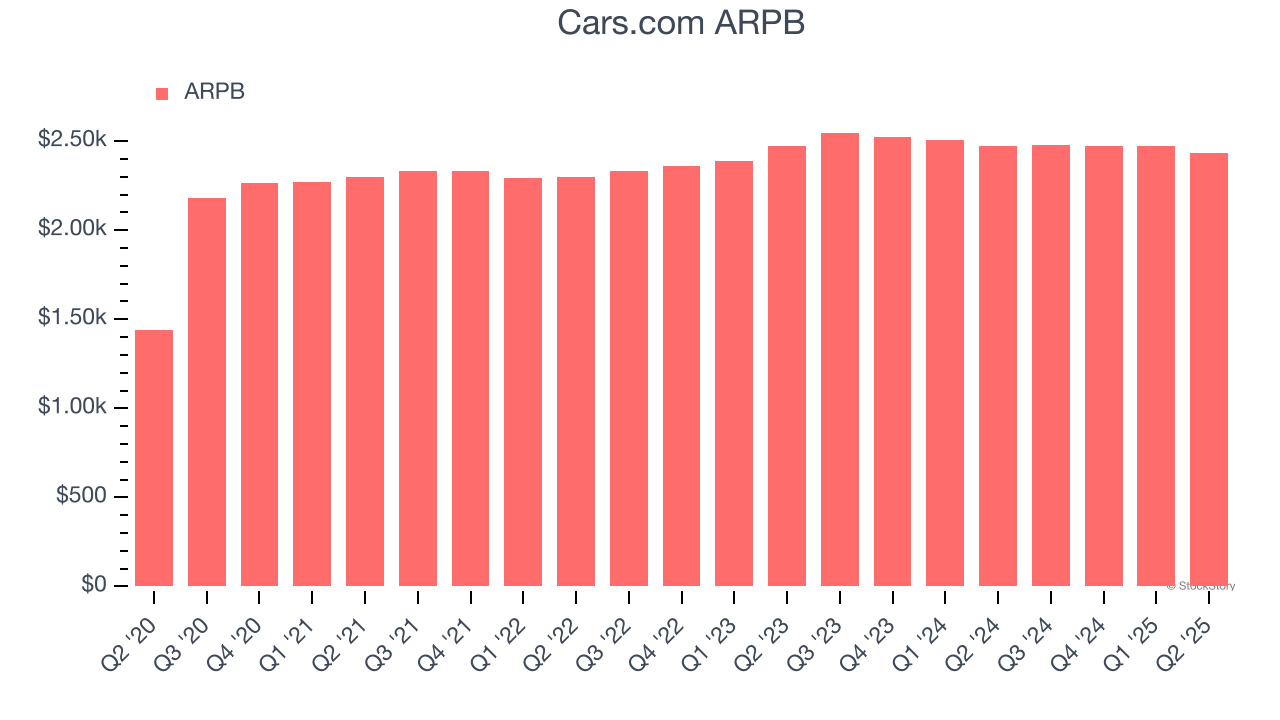
This quarter, Cars.com’s ARPB clocked in at $2,435. It declined 1.6% year on year, worse than the change in its dealer customers.
Key Takeaways from Cars.com’s Q2 Results
It was good to see Cars.com narrowly top analysts’ EBITDA expectations this quarter. On the other hand, its revenue was in line. Overall, this was a weaker quarter. The stock traded down 15.1% to $11.16 immediately after reporting.
So do we think Cars.com is an attractive buy at the current price? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. We cover that in our actionable full research report which you can read here, it’s free.
Mentioned In This Article
Latest News
| Sep-30 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-29 | |
| Jul-23 | |
| Jul-01 | |
| Jun-23 | |
| Jun-23 | |
| Jun-23 | |
| Jun-11 | |
| Jun-11 | |
| May-20 | |
| May-07 | |
| May-07 |
