ServisFirst Bancshares (NYSE:SFBS) Misses Q3 Sales Expectations
Regional banking company ServisFirst Bancshares (NYSE:SFBS) fell short of the market’s revenue expectations in Q3 CY2025, but sales rose 10.2% year on year to $136.3 million. Its non-GAAP profit of $1.30 per share was 2.7% below analysts’ consensus estimates.
Is now the time to buy ServisFirst Bancshares? Find out by accessing our full research report, it’s free for active Edge members.
ServisFirst Bancshares (SFBS) Q3 CY2025 Highlights:
- Net Interest Income: $133.4 million vs analyst estimates of $137.6 million (15.9% year-on-year growth, 3% miss)
- Net Interest Margin: 3.1% vs analyst estimates of 3.2% (8.3 basis point miss)
- Revenue: $136.3 million vs analyst estimates of $146.8 million (10.2% year-on-year growth, 7.2% miss)
- Efficiency Ratio: 35.2% vs analyst estimates of 31.7% (355.3 basis point miss)
- Adjusted EPS: $1.30 vs analyst expectations of $1.34 (2.7% miss)
- Tangible Book Value per Share: $32.37 vs analyst estimates of $32.28 (13.5% year-on-year growth, in line)
- Market Capitalization: $4.11 billion
Tom Broughton, Chairman, President, and CEO, said, “All of our regions and markets were solidly profitable in the third quarter of 2025. We have seen great progress in all our markets and our newer offices have reached profitability.”
Company Overview
Founded in 2005 with a focus on serving underserved mid-sized businesses, ServisFirst Bancshares (NYSE:SFBS) is a bank holding company that provides commercial banking services to businesses and professionals through its subsidiary ServisFirst Bank.
Sales Growth
From lending activities to service fees, most banks build their revenue model around two income sources. Interest rate spreads between loans and deposits create the first stream, with the second coming from charges on everything from basic bank accounts to complex investment banking transactions. Thankfully, ServisFirst Bancshares’s 8.7% annualized revenue growth over the last five years was solid. Its growth surpassed the average banking company and shows its offerings resonate with customers, a great starting point for our analysis.
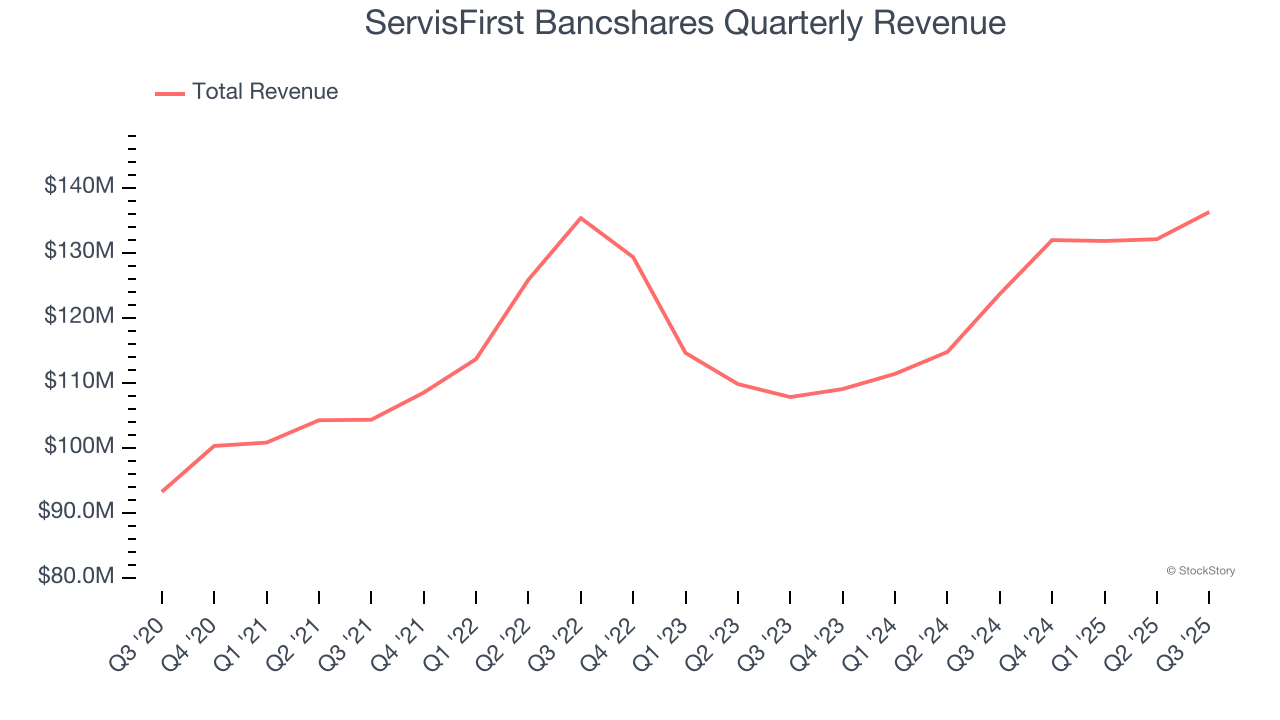
We at StockStory place the most emphasis on long-term growth, but within financials, a half-decade historical view may miss recent interest rate changes, market returns, and industry trends. ServisFirst Bancshares’s annualized revenue growth of 7.4% over the last two years is below its five-year trend, but we still think the results suggest healthy demand.
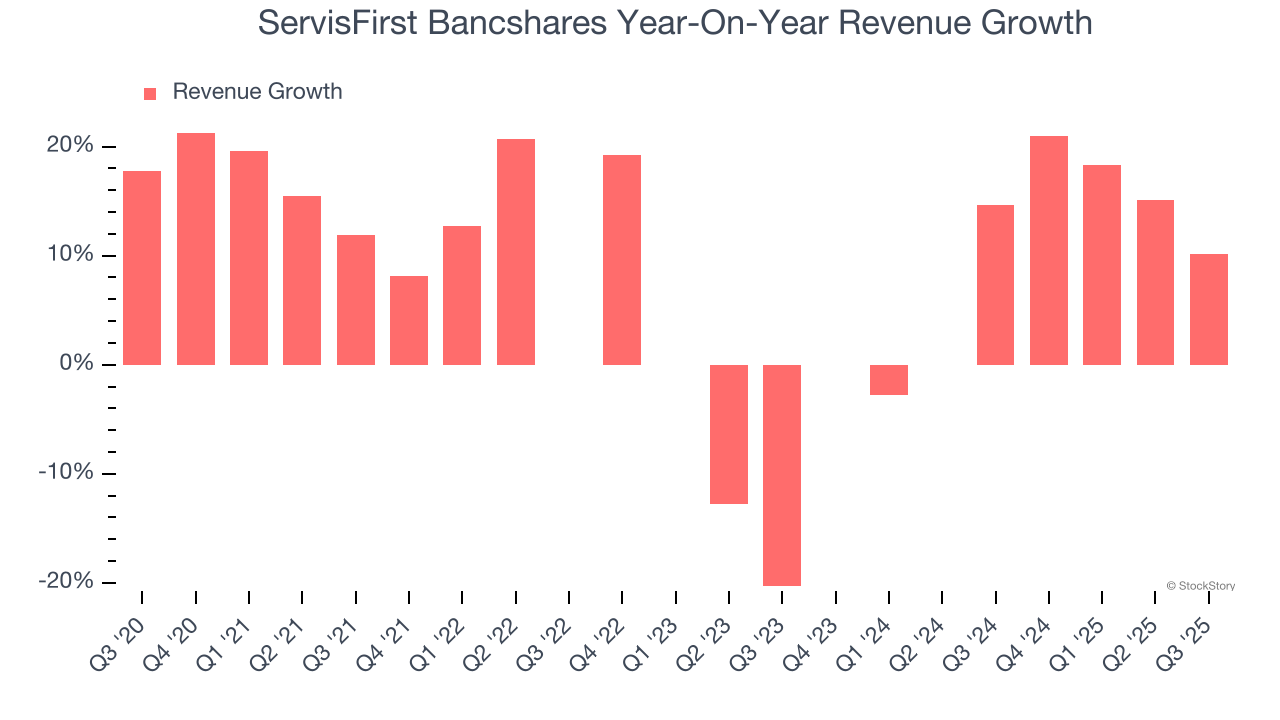
This quarter, ServisFirst Bancshares’s revenue grew by 10.2% year on year to $136.3 million but fell short of Wall Street’s estimates.
Net interest income made up 93.4% of the company’s total revenue during the last five years, meaning ServisFirst Bancshares lives and dies by its lending activities because non-interest income barely moves the needle.
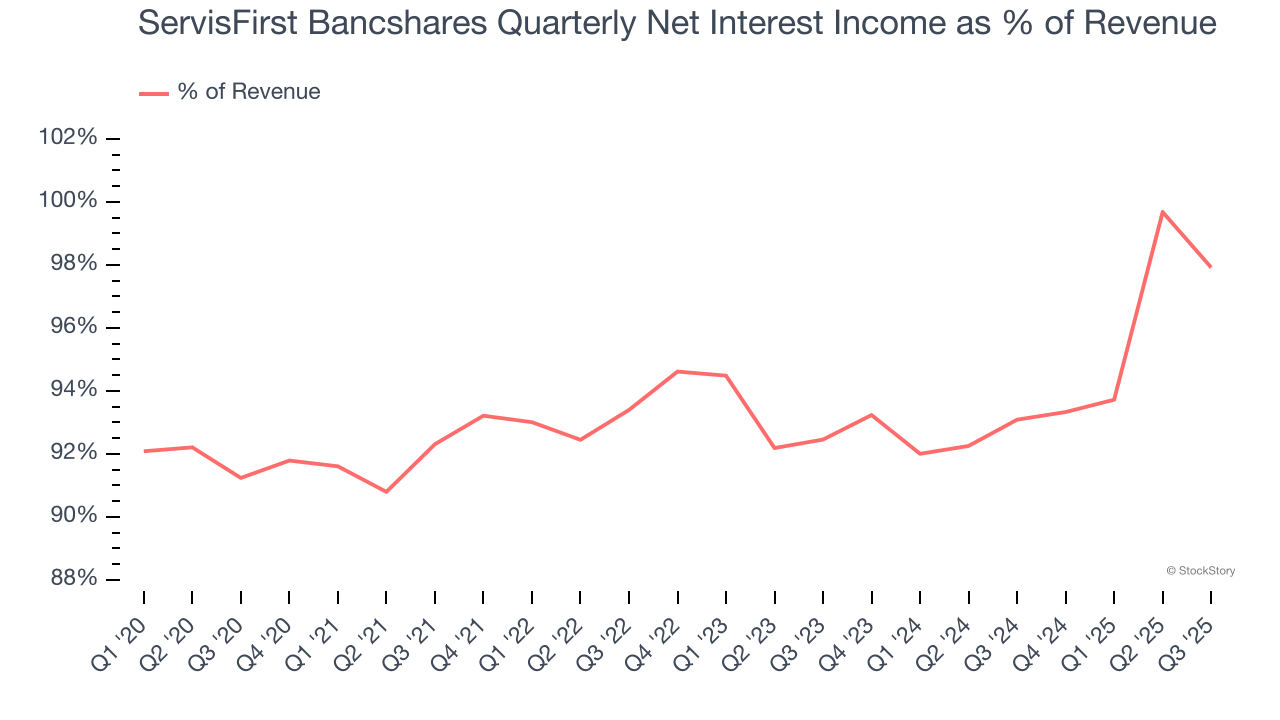
Net interest income commands greater market attention due to its reliability and consistency, whereas non-interest income is often seen as lower-quality revenue that lacks the same dependable characteristics.
Software is eating the world and there is virtually no industry left that has been untouched by it. That drives increasing demand for tools helping software developers do their jobs, whether it be monitoring critical cloud infrastructure, integrating audio and video functionality, or ensuring smooth content streaming. Click here to access a free report on our 3 favorite stocks to play this generational megatrend.
Tangible Book Value Per Share (TBVPS)
Banks operate as balance sheet businesses, with profits generated through borrowing and lending activities. Valuations reflect this reality, emphasizing balance sheet strength and long-term book value compounding ability.
Because of this, tangible book value per share (TBVPS) emerges as the critical performance benchmark. By excluding intangible assets with uncertain liquidation values, this metric captures real, liquid net worth per share. Other (and more commonly known) per-share metrics like EPS can sometimes be murky due to M&A or accounting rules allowing for loan losses to be spread out.
ServisFirst Bancshares’s TBVPS grew at an incredible 13.3% annual clip over the last five years. The last two years show a similar trajectory as TBVPS grew by 12.7% annually from $25.49 to $32.37 per share.
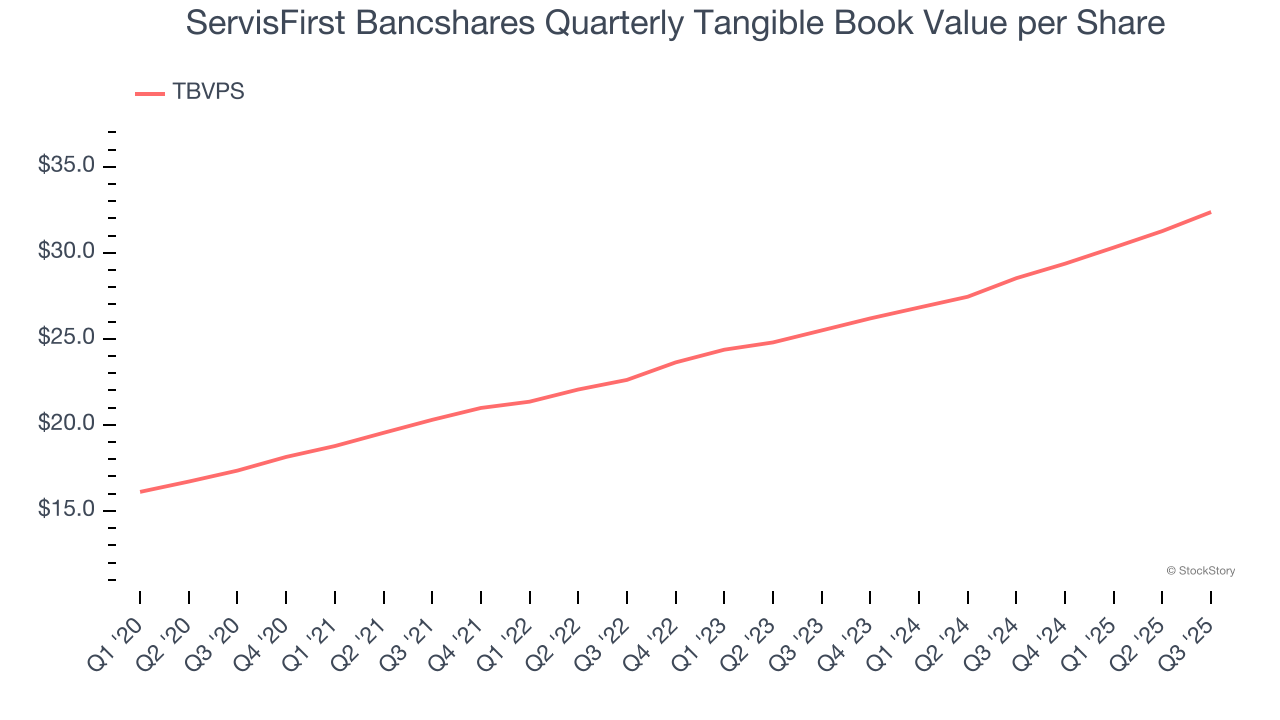
Over the next 12 months, Consensus estimates call for ServisFirst Bancshares’s TBVPS to grow by 13.8% to $36.83, top-notch growth rate.
Key Takeaways from ServisFirst Bancshares’s Q3 Results
We struggled to find many positives in these results. Its revenue missed and its net interest income fell short of Wall Street’s estimates. Overall, this was a softer quarter. The stock remained flat at $76.11 immediately following the results.
ServisFirst Bancshares underperformed this quarter, but does that create an opportunity to invest right now? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. We cover that in our actionable full research report which you can read here, it’s free for active Edge members.
Mentioned In This Article
Latest News
| Aug-25 | |
| Aug-24 | |
| Jul-21 | |
| Jul-21 | |
| Jul-20 | |
| Jul-20 | |
| Jul-20 | |
| Jul-17 | |
| Jul-09 | |
| Jun-24 | |
| Jun-15 | |
| Apr-21 | |
| Apr-21 | |
| Apr-20 | |
| Apr-20 |
