Buy the Dip in Alphabet (GOOGL) Stock as Q1 Earnings Approach?
Outside of Tesla TSLA, Wall Street will be paying close attention to Alphabet’s GOOGL quarterly results this week, with the tech behemoth set to release its Q1 report on Thursday, April 24th.
Mounting antitrust pressures have weighed on Alphabet stock as a call to potentially break up Google’s search engine business has led to lower investor sentiment amid broader economic concerns. Furthermore, monopoly concerns regarding Alphabet’s dominance in the online advertising market have extended the selloff, with GOOGL shares down 20% year to date.
That said, Alphabet stock is still sitting on +40% gains over the last two years, making it a worthy topic of if now is a good time to buy the dip.
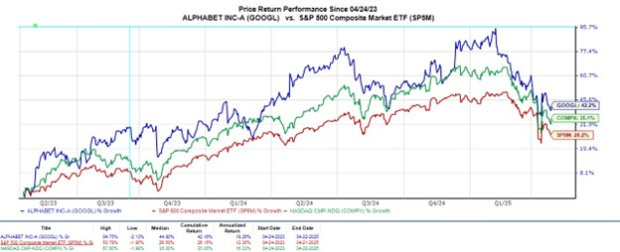
Image Source: Zacks Investment Research
Alphabet’s Q1 Expectations
Optimistically, Alphabet’s Q1 sales are expected at $75.53 billion, a 12% increase from $67.59 billion in the comparative quarter. On the bottom line, Q1 EPS is expected to be up 6% to $2.01 compared to $1.89 per share a year ago. Alphabet has exceeded the Zacks EPS Consensus for eight consecutive quarters with an average earnings surprise of 11.57% in its last four quarterly reports.
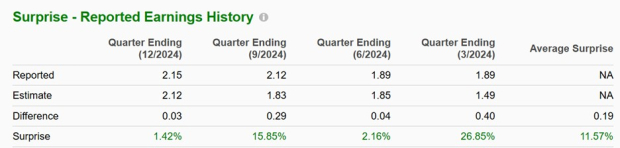
Image Source: Zacks Investment Research
Cheapest P/E Valuation Among the Mag 7
Most appealing about Alphabet stock at the moment is that GOOGL has the cheapest P/E valuation among the "Magnificent 7" big tech stocks. Trading around $150, GOOGL is at a 16.9X forward earnings multiple, a noticeable discount to the benchmark S&P 500’s 19.8X.
Notably, the next cheapest P/E valuation among the Mag 7 is Meta Platforms META at 19.9X forward earnings, with Tesla's 87X the highest among the group.
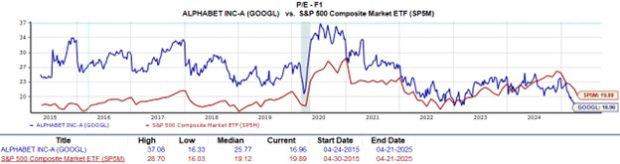
Image Source: Zacks Investment Research
GOOGL Price Target & Broker Recommendations
Based on short-term price targets offered by 48 analysts, the Average Zacks Price Target for Alphabet stock is $202.06, which suggests 37% upside from current levels.
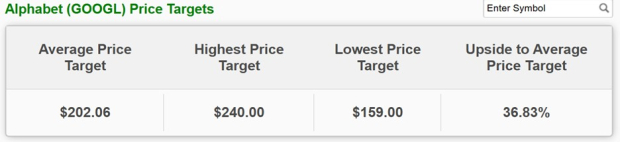
Image Source: Zacks Investment Research
Although the average brokerage recommendation (ABR) shouldn’t be confused with the Zack Rank, GOOGL has an ABR of 1.40 on a scale of 1 to 5 (Strong Buy to Strong Sell) which is based on the recommendations of 53 brokerage firms.
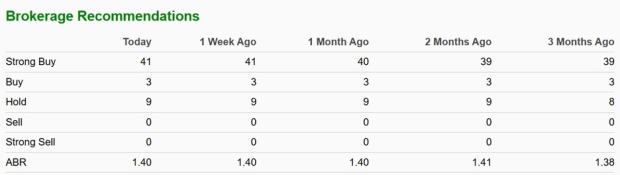
Image Source: Zacks Investment Research
Conclusion & Final Thoughts
While the downside risk is starting to look priced in, Alphabet stock currently lands a Zack Rank #3 (Hold). To that point, Alphabet’s EPS outlook is still attractive, but earnings estimate revisions have trended down for fiscal 2025 and FY26.
Considering such, Alphabet’s Q1 report will be critical as a further decline in EPS revisions could lead to a sell rating, but of course, an uptick may lead to a buy rating with GOOGL trading at its cheapest forward P/E valuation in the last decade.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Alphabet Inc. (GOOGL): Free Stock Analysis Report
Tesla, Inc. (TSLA): Free Stock Analysis Report
Meta Platforms, Inc. (META): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 4 hours | |
| Nov-19 | |
| Nov-19 | |
| Nov-19 |
Anthropic's Mega IPO Lives Up to Wall Street Hype but Fails to Revive AI Trade
GOOGL -3.46%
The Wall Street Journal
|
| Nov-19 | |
| Nov-19 | |
| Nov-19 | |
| Nov-19 | |
| Nov-19 | |
| Nov-19 | |
| Nov-19 | |
| Nov-19 | |
| Nov-19 |
