Bear of the Day: The Campbell's Company (CPB)
The Campbell’s Company Overview
Zacks Rank #5 (Strong Sell) stock The Campbell’s Company (CPB) is one of North America’s largest branded food and beverage product companies. Headquartered in Camden, NJ, and founded in 19222, the company’s portfolio includes brands such as Campbell’s, Rao’s, Goldfish, Pepperidge Farm, Swanson, Pacific Foods, Prego, Pace, V8, Snyder’s of Hanover, Lance, Cape Cod, Kettle Brand, Late July, and Snack Factory. The Campbell’s meals and beverages segment comprises ~60% of sales and includes soup, simple meals, and beverages sold through retail and foodservice stores throughout North America. The snacks segment includes frozen products, cookies, and crackers and accounts for the remaining 40% of revenues.
Campbell’s Snack Segment Sees Weakness
In Q4, Campbell’s snack segment saw organic net sales fall 6% while operating earnings plunged 28%. Unfortunately for Campbell’s, multiple factors drove the weakness. First, over the past few years, consumers have dramatically cut back on junk food and are choosing healthier alternatives (with GLP-1 fat loss drugs only intensifying this headwind). Second, with inflation running hot, consumers are prioritizing essentials and cutting back on discretionary snack food purchases. Finally, costs are rising, squeezing margins. For instance, the management team expects raw-material and packaging inflation of 5-6% and double-digit logistics inflation, driven by higher diesel costs and reduced driver availability. Additionally, import tariffs have added 4% to the company’s costs. Since late 2021, gross profit margins have plunged from 32.5% to 28.14%.
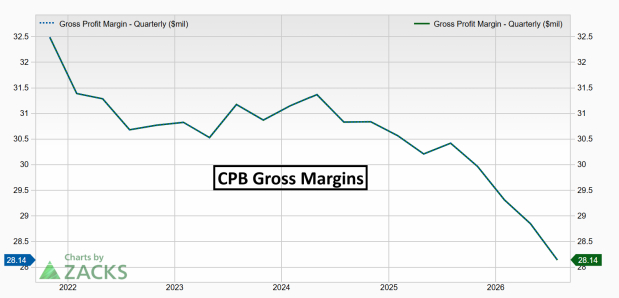
Image Source: Zacks Investment Research
Earnings Will Be Stagnant Through Next Year
Campbell’s management team expects earnings to remain weak. Fiscal 2027 guidance suggests 2027 will be another year of declining sales and profits after an abysmal 2026, when EPS plunged 27%. Zacks Consensus Estimates expect a similar trajectory, with 2027 annual earnings dropping 18.43%.
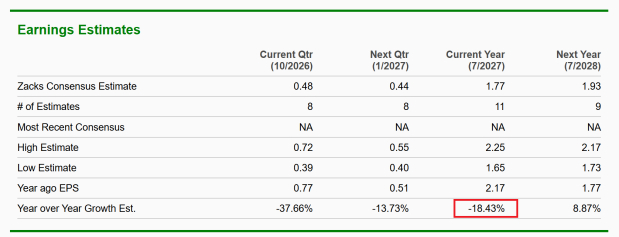
Image Source: Zacks Investment Research
CPB Technical View
Campbell’s shares have shown troubling relative weakness, down 36% over the past year compared to the S&P 500’s 16.5% gain. Even if CPB shares stage a rally, a lot of overhead selling supply waiting from bulls who are offside on their positions.
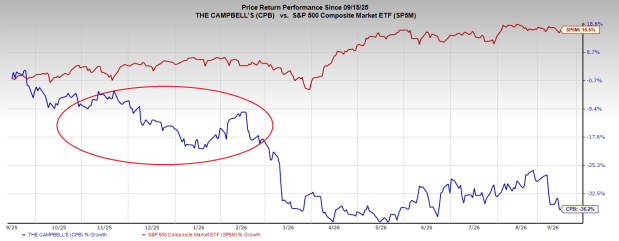
Image Source: Zacks Investment Research
Bottom Line
The Campbell’s Company faces shifting consumer habits, shrinking margins, and a stagnant earnings trajectory. These fundamental and technical headwinds make a near-term turnaround unlikely.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
The Campbell's Company (CPB): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Mentioned In This Article
Latest News
| 3 hours | |
| Sep-08 | |
| Sep-08 | |
| Sep-04 | |
| Sep-04 | |
| Sep-04 | |
| Sep-04 | |
| Sep-03 | |
| Sep-03 | |
| Sep-03 | |
| Sep-03 | |
| Sep-03 | |
| Sep-03 | |
| Sep-03 | |
| Sep-03 |
