Micron Earnings: Watch These Key Metrics
Memory giant Micron Technology MU is set to report its quarterly results after the market’s close this Wednesday, September 30th. The release will undoubtedly draw heavy attention given the massive momentum around the company, with Micron reflecting one of the strongest plays on the AI frenzy in 2026.
Micron’s previous quarter brought record results again, and the company also provided a highly bullish growth outlook for the upcoming release. Given the importance of the print, let’s take a look at a few key metrics to keep an eye out for.
DRAM Expectations
As expected, Micron's DRAM results will be a major focus, with demand for high-bandwidth memory remaining red-hot from the ongoing AI infrastructure buildout. Our consensus estimate for DRAM sales stands at $38.3 billion, suggesting roughly a triple-digit 330% YoY growth rate from the same period last year.
The company has regularly crushed our consensus DRAM estimates in recent periods, stringing together five consecutive beats.
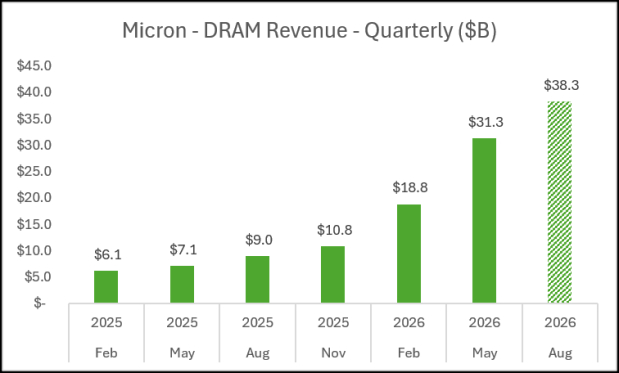
Image Source: Zacks Investment Research
The favorable pricing environment will also be key to watch, with improved supply-demand dynamics across the memory landscape providing a big boost to Micron’s results. The strength has flowed directly into profitability, with management guiding for a roughly 86% gross margin in the upcoming release.
NAND Expectations
NAND results are similarly worth investors’ attention because they reveal demand for enterprise storage and serve as a secondary engine for Micron's overall growth amid the favorable environment. The current Zacks Consensus estimate calls for $12.3 billion in sales, good enough for roughly 435% YoY growth.
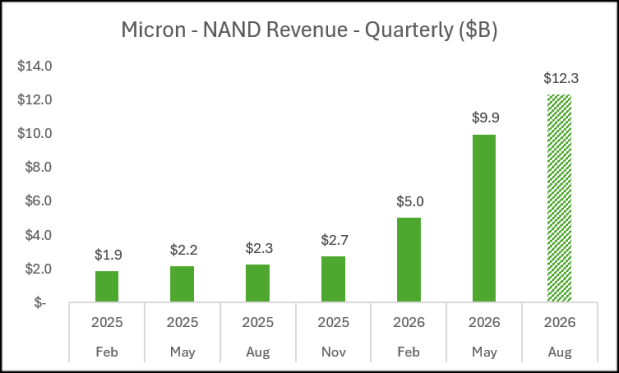
Image Source: Zacks Investment Research
Headline Expectations
The overall growth picture remains red-hot, with the current Zacks Consensus sales estimate sitting at $50.9 billion, reflecting roughly 350% YoY growth. Adjusted earnings are expected to come in at $31.45 per share, soaring from the $3.03 per share reported in the year-ago period.
Micron has consistently been a stellar earnings performer thanks to the demand backdrop, exceeding the Zacks Consensus EPS estimate by an average of roughly 21% across its last four releases. Both EPS and sales expectations for the upcoming release have trended modestly higher over recent months.
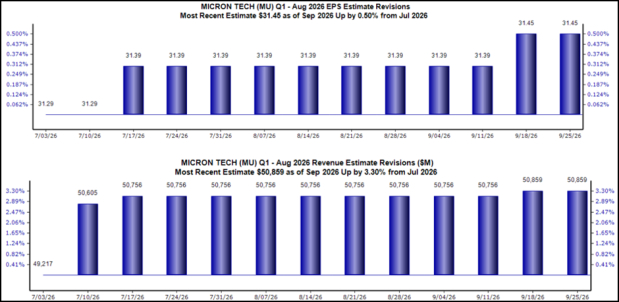
Image Source: Zacks Investment Research
Bottom Line
Micron’s MU upcoming release will be closely watched given the massive growth the company has enjoyed alongside the AI infrastructure boom. DRAM results will undoubtedly take center stage, though NAND growth, memory pricing, and the company’s outlook will also be key areas to watch. With Micron coming off record results and expectations calling for another quarter of explosive growth, the release should provide an important look into whether its AI-driven momentum can remain red-hot.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Micron Technology, Inc. (MU): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Mentioned In This Article
Latest News
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 3 hours | |
| 4 hours | |
| 4 hours | |
| 4 hours | |
| 4 hours | |
| 5 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours | |
| 7 hours | |
| 8 hours |
