Should Investors Chase Carnival (CCL) Stock After Its 13% Post-Earnings Surge?
Carnival Corporation CCL) stock surged 13% on Tuesday after the cruise giant delivered better-than-expected fiscal third-quarter results and provided an encouraging demand outlook.
The rally is particularly notable as CCL entered its Q3 report near 52-week lows of $21 a share, with investors concerned about higher fuel costs, geopolitical disruptions, and the durability of consumer travel spending.
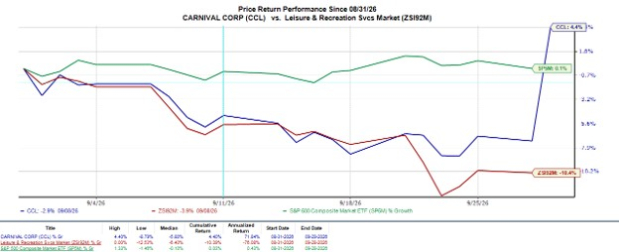
Image Source: Zacks Investment Research
Carnival Tops Q3 Expectations With Record Revenue
Carnival posted adjusted Q3 earnings of $1.43 per share, topping the Zacks EPS Consensus of $1.36 by 5% and matching the year-ago period despite a $131 million unfavorable impact from higher fuel prices and currency movements.
Quarterly revenue rose 3.5% year over year to a record $8.44 billion, also exceeding Q3 expectations of $8.36 billion. Net yields increased 2.4% in constant currency and came in more than one percentage point above Carnival's previous guidance.
Notably, Carnival has now exceeded earnings expectations for 16 consecutive quarters and has surpassed sales estimates in three of its last four quarterly reports.
Most importantly, strong demand appears to be carrying into next year. Carnival's 2027 booked occupancy and pricing are both at record levels, while third-quarter customer deposits reached a record $7.6 billion despite essentially flat capacity growth.
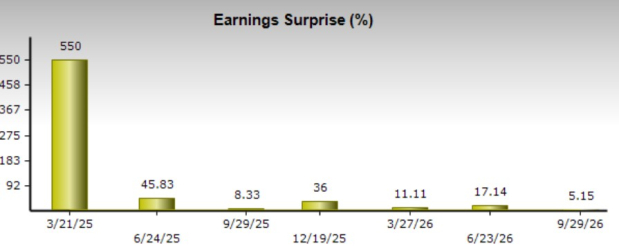
Image Source: Zacks Investment Research
Carnival Raises Its 2026 Outlook
Carnival now expects full-year fiscal 2026 adjusted EPS of approximately $2.24, with adjusted net income of roughly $3.08 billion. Management said operational improvements have added more than $150 million to its adjusted net income outlook compared with June guidance, enough to offset roughly $150 million of higher fuel costs.
There is one modest caution: Carnival expects Q4 adjusted EPS of about $0.20, slightly below the current consensus expectation of $0.24. Still, record 2027 bookings provide a much stronger indication that underlying cruise demand remains resilient.
Bottom Line
The combination of record revenue, improving yields, strong 2027 bookings, and a raised full-year outlook helps validate the bullish case for Carnival despite persistent fuel-cost pressures.
Still, following a 13% one-day surge, investors may not need to aggressively chase CCL shares even at an attractive sub-12X forward earnings multiple.
That said, Carnival stock currently lands a Zacks Rank #3 (Hold), making further upward earnings-estimate revisions for FY27 especially important following today's sharp post-earnings rally.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Carnival Corporation (CCL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Mentioned In This Article
Latest News
| 3 hours | |
| 4 hours | |
| 8 hours | |
| 10 hours | |
| 11 hours | |
| 11 hours | |
| 12 hours | |
| 12 hours | |
| 12 hours | |
| 12 hours | |
| 12 hours | |
| 12 hours | |
| 12 hours | |
| 13 hours |
Carnival Earnings Prediction Market Preview: What Will Josh Weinstein Say?
CCL +13.41%
Benzinga Prediction Markets
|
| 17 hours |
