Q3 Earnings Season Begins: Global Week Ahead
What happens across this Global Week Ahead?
- The IMF-World Bank meetings take place in Bangkok, against
- A backdrop of high energy costs and rising central bank rates, while
- The latest U.S. and China macro data
- Wall Street Q3 earnings, and
- Turbulent bond markets point to a packed week ahead
Next are Reuters’ five world market themes, re-ordered for equity traders—
(1) U.S. Q3 Earnings Season Kicks Off — with the Major Banks, of Course
It's the start of Q3 U.S. earnings season, and who better to kick things off than the banks?
Four of the six largest U.S. lenders, JPMorgan Chase JPM, Goldman Sachs GS, Citigroup C and Wells Fargo WFC, report on Tuesday, followed a day after by Morgan Stanley MS and Bank of America BAC.
Earnings are expected to rise up to +20% relative to last year.
Still, the surge in Treasury yields to multi-decade highs has hurt shares — the KBW Bank Index is down around -13% from its peak in August.
Investors will be looking for signs that the recent spike in government borrowing costs may curb dealmaking and lending growth, as well as pressure funding costs across the industry.
(2) U.S. and French Government Bond Yields Keep Surging
Surging government borrowing costs are clearly luring some investors back to bonds as evidenced by the strong demand at the latest U.S. and Japanese auctions.
But do you really want to catch a falling knife?
That's the question for traders in the coming week as the bond selloff shows few signs of abating.
U.S. and French bond yields have hit fresh 24-year highs and market volatility is high.
The French-German 10-year bond yield spread, at around 136 basis points, was below 100 bps a month ago.
The speed and scale of the rise in the French risk premium is hurting Italian peers, the euro and European shares.
It's also led to some finger-pointing at the role of hedge funds — that fast-money group that has stepped up its presence in systemically important bond markets of late.
(3) On Wednesday, U.S. Consumer Price Inflation (CPI) Data for September Lands
A fresh look at U.S. inflation on Wednesday will be among the last key data released before the Federal Reserve decides whether to hike interest rates again to contain high prices.
The September CPI is set to show a 0.6% rise on a monthly basis. The core measure, excluding volatile energy and food components, is estimated to increase just 0.2%, according to a Reuters poll.
Thursday's Producer Price Index (PPI) numbers will further flesh out the inflation picture. Retail sales data is also out that day.
Core CPI for August rose at its fastest pace in four months, helping cement the Fed's first rate hike since 2023.
Bets on another hike when the Fed meets in late October have fallen back. A hot CPI report could change that.
(4) On Wednesday, Mainland China Macro Data Will Reveal Export Growth
Chinese data on Wednesday will show whether AI-related exports are still propping up an economy hobbled by anemic demand at home.
Overseas shipments from the world's second-largest economy have logged double-digit growth for ???four straight months on surging global demand for AI goods, electric vehicles, solar cells and lithium-ion batteries.
But a prolonged property slump has kept domestic consumption in the doldrums.
Exports are forecast to have jumped +25.3% year-on-year in September in dollar terms, according to a Reuters poll, up from +25% in August.
Imports are projected to show +23.5% growth versus +28.2% previously.
Separate figures the same day are expected to show continuing price pressures related to the Iran war.
The Producer Price Index is forecast to have risen to +4.4% in September from +3.8% the previous period, while consumer inflation may have edged up to +1.1% from +0.8%.
(5) The IMF and World Bank Annual Meetings Happen in Bangkok
The IMF and World Bank annual meetings go on tour to Bangkok next week with three themes front and center: growth, debt and geopolitics.
Market focus is on Tuesday's updated IMF World Economic Outlook, given the Iran war has already forced two cuts to its global GDP forecast this year.
IMF chief Kristalina Georgieva has signaled it won't make easy reading, given sky-high energy prices, record public debt and tetchy bond markets.
Fractured and fractious geopolitics, including conflicts in the Middle East and Ukraine, will feature prominently, as will how to regulate AI given an arms race between the US and China.
Senegal's recently announced debt rework plan is likely to get attention from IMF crisis watchers too, although they will have more than half an eye on whether France is dragging the Eurozone back in that direction as well.
Zacks #1 Rank (STRONG BUY) Stocks
This week, I picked three fresh Zacks #1 (STRONG BUY) large-cap stocks.
(1) Keysight Technologies KEYS: This is a $375 a share tech growth stock, with a market cap of $64.3B.
It is found in the Zacks Electronics-Measuring Instruments industry. The stock holds a Zacks Value score of D, a Zacks Growth score of C, and a Zacks Momentum score of D.
F12M P/E: 33.3.
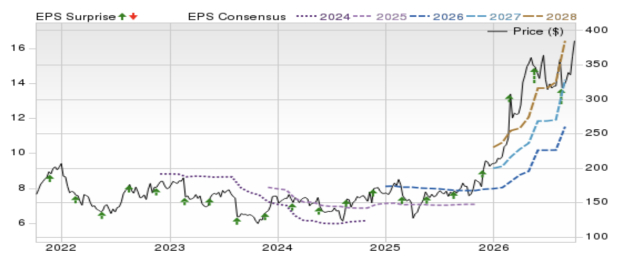
Image Source: Zacks Investment Research
Keysight Technologies is a provider of electronic design and test instrumentation systems.
Keysight's suite of connected car test solutions include Virtual Drive Test Toolset, which facilitates automakers to build virtual test routes in the lab by integrating network and channel emulation capabilities, and combining data captured in the field.
Moreover, the company is evolving its expertise in software test automation capabilities.
Meanwhile, KeysightCare aids customers with end-to-end scalable support model solution loaded with robust test and measurement know-how to reduce time-to-market and enhance efficiency in a cost-effective manner.
(2) Ciena CIEN: This is a $426 a share Communications stock, with a market cap of $63.3B.
It is found in Zacks Communication Components industry. The stock holds a Zacks Value score of F, a Zacks Growth score of B, and a Zacks Momentum score of C.
F12M P/E: 62.3.
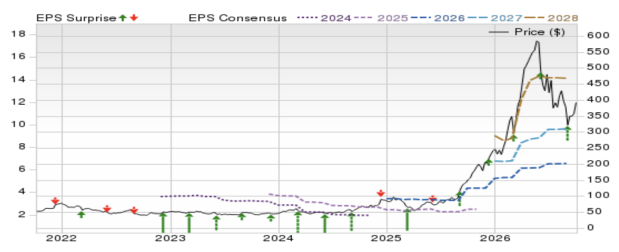
Image Source: Zacks Investment Research
Ciena Corp. is a leading provider of optical networking equipment, software and services.
Its reporting segments are: Networking Platforms, Platform Software & Services, Blue Planet Automation Software & Services, and Global Services.
The Networking Platforms segment includes networking solutions optimized for the convergence of coherent optical transport, Optical Transport Network switching and packet switching.
Its products include the 6500 packet-optical platform, the Waveserver family of products, 6500 Reconfigurable Line System, 5400 family of packet-optical platforms and coherent-optimized edge line system, the 3900 family of service delivery switches and service aggregation switches and the 5000 series of service aggregation platforms.
The Platform Software & Services segment provides domain control management, analytics data and planning tools.
Blue Planet is a comprehensive, cloud native and standards-based software portfolio that enables customers to realize their digital transformation.
(3) A.P. Moller-Maersk AMKBY: This is an $18 a share global shipping stock, with a market cap of $58.2B.
It is found in the Zacks Transportation-Shipping industry. The stock holds a Zacks Value score of A, a Zacks Growth score of B, and a Zacks Momentum score of B.
F12M P/E: 7.3.
A.P. Moeller-Maersk A/S operates as a shipping company.
It operates container vessels, tankers, supply ships, special vessels, APM terminials and oil drilling rigs.
A.P. Moeller-Maersk A/S is headquartered in Copenhagen, Denmark.
Key Global Macro
Wednesday’s U.S. CPI data for SEP is among the key inflation reports this week.
On Sunday, the IMF World Bank meetings began in Bangkok.
On Tuesday, the Reserve Bank of Australia (RBA) meeting minutes come out, and Mainland China releases a raft of macro data. Among this, China’s CPI for SEP is reported. The consensus looks for +1.1% y/y, while the prior is +0.8% y/y.
On Wednesday, the U.S. CPI for SEP gets released early. The prior broad CPI was +3.4% y/y, while the core CPI was +2.4% y/y.
On Thursday, the U.S. PPI for SEP gets released. The prior AUG broad PPI was up +5.4% y/y, while the prior AUG core PPI was up +4.6% y/y.
On Friday, the Euro Area core and broad HICP data for SEP gets released. Look for core HICP to remain unchanged at +2.5% y/y. Broad HICP should also remain unchanged at +3.8% y/y.
Conclusion
On Oct. 7th, Zacks Research Director Sheraz Mian shared his Q3 earnings set-up.
Key points:
(1) The overall setup for the Q3 earnings season remains very favorable, with earnings growth expected to be in the double digits for the 8th consecutive quarter.
The growth momentum is broad-based.
15 of the 16 Zacks sectors are expected to enjoy positive earnings growth, and the outlook steadily improving.
(2) Total S&P500 earnings in Q3 are currently expected to increase +24.6% from the same period last year, on +11.5% higher revenues.
(3) The revisions trend remains positive, sustaining the favorable revisions trend that has been in place for a year now.
Since the start of Q3, earnings estimates have moved higher for half of the 16 Zacks sectors.
We are seeing a similar trend for Q4 — and full-year 2027, as well.
(4) Micron MU and Nvidia NVDA continue to be material contributors to the Info Tech sector’s growth picture.
Excluding Nvidia, Micron, and Alphabet GOOGL, which enjoyed an outsized gain in the preceding period?
Q3 earnings for the rest of the Info Tech sector would be +20.7% (vs. +43.4% otherwise).
That’s all from me!
Best of luck, in trading & investing.
John Blank, PhD.
Zacks Chief Equity Strategist and Economist
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
The Goldman Sachs Group, Inc. (GS): Free Stock Analysis Report
Bank of America Corporation (BAC): Free Stock Analysis Report
Wells Fargo & Company (WFC): Free Stock Analysis Report
JPMorgan Chase & Co. (JPM): Free Stock Analysis Report
Morgan Stanley (MS): Free Stock Analysis Report
Citigroup Inc. (C): Free Stock Analysis Report
Ciena Corporation (CIEN): Free Stock Analysis Report
Micron Technology, Inc. (MU): Free Stock Analysis Report
NVIDIA Corporation (NVDA): Free Stock Analysis Report
Alphabet Inc. (GOOGL): Free Stock Analysis Report
Keysight Technologies Inc. (KEYS): Free Stock Analysis Report
A.P. Moller-Maersk (AMKBY): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Mentioned In This Article
Latest News
| 4 min | |
| 16 min | |
| 26 min | |
| 37 min | |
| 44 min | |
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 2 hours |
