Bull of the Day: Micron (MU)
Micron Technology Company Overview
Zacks Rank #1 (Strong Buy) Micron Technology (MU) manufactures and markets high-performance memory and storage technologies, including Dynamic Random-Access Memory (DRAM), NAND flash memory, NOR Flash, and other memory solutions. The Idaho-based company’s solutions power leading-edge computing, consumer, networking, mobile, automotive, industrial, and data center products. The company’s mission is to be a global leader in memory and storage solutions.
AI Demand & the DRAM Bottleneck
The DRAM technology Micron manufactures is critical to the artificial intelligence buildout because AI models depend on massive streams of data and model parameters that must be accessed, processed, and moved at ultra-high speeds to prevent the processor from stalling. AI computation is heavily “memory-bound,” meaning the processor’s speed is often limited by how fast data can be fed to it rather than how fast it can calculate. Recently, SpaceX (SPCX) CEO Elon Musk, whose company is a leading provider of compute, said that “Few realize that memory, not compute, is the rate limiter of the Agentic Era.”
Micron is currently benefiting from a perfect elixir of soaring AI infrastructure demand reshaping memory and storage demand mixed with a tight global DRAM supply. Micron continues to benefit as hyperscalers jockey for AI supremacy and spend increasingly more CAPEX on AI infrastructure. Last quarter, Micron reported revenues that more than tripled year-over-year along with earnings-per-share that increased 10-fold.
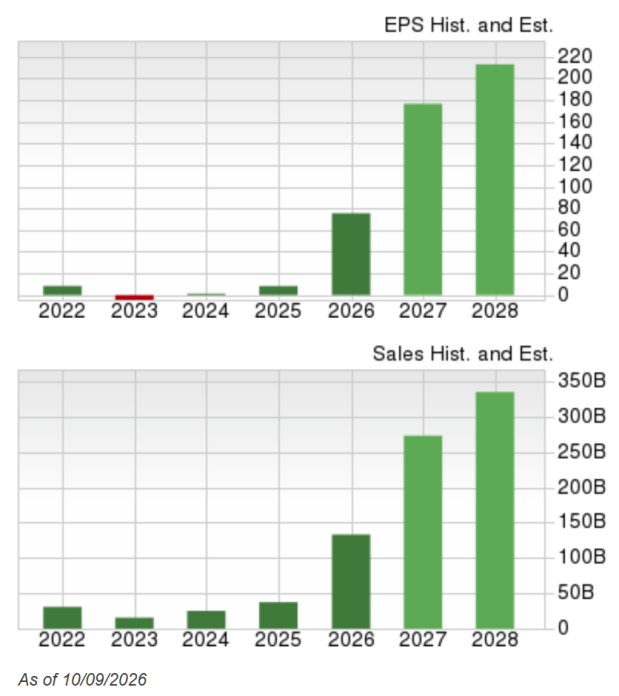
Image Source: Zacks Investment Research
Meanwhile, because supply is tight and Micron is one of only three major global DRAM suppliers, its gross margins have soared to more than 80%.
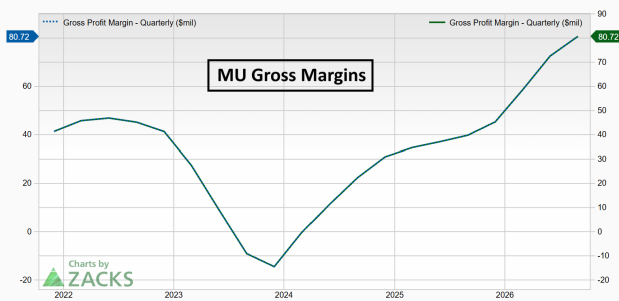
Image Source: Zacks Investment Research
Micron: A Consistent Earnings Outperformer
Wall Street expectations remain high. Next quarter, Zacks Consensus Estimates suggest revenue will grow 352.68% while earnings spike 699.16%. Nevertheless, Micron has proven it can beat high estimates. The memory leader has beaten Wall Street analyst expectations for 14 consecutive quarters, with an average beat of 21% over the past four.
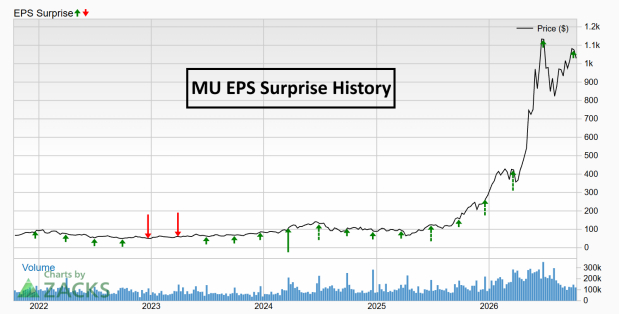
Image Source: Zacks Investment Research
High Demand Visibility
As of the fourth quarter, Micron had signed 26 take-or-pay strategic customer agreements (SCAs), which management estimates will represent more than 35% of revenues through 2030. Additionally, approximately three-quarters of that expected revenue has a defined pricing framework.
Micron Buybacks to Begin as CHIPS Act Restrictions End
Micron has faced a buyback restriction tied to the U.S. CHIPS Act agreement, under which the company received a $6.1 billion reward. However, the share buyback restrictions end on December 9th. Recently, Micron’s board approved a $35.16 billion share repurchase program. The share buyback will have a bullish impact on the supply/demand dynamics for Micron shares.
Micron has a Reasonable Valuation
Micron not only has one of the fastest-growth rates on Wall Street, but it also sports one of the most attractive valuations. Micron’s P/E ratio is currently just 13.63x.
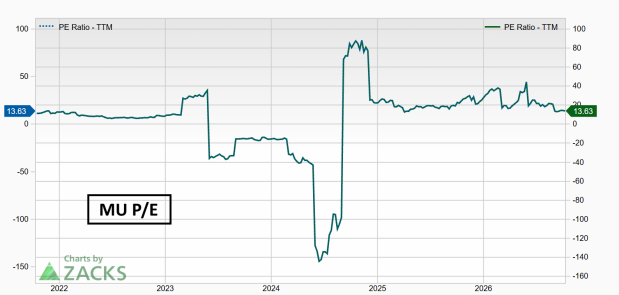
Image Source: Zacks Investment Research
Micron Technical View
Micron shares are setting up in a bullish monthly flag pattern.
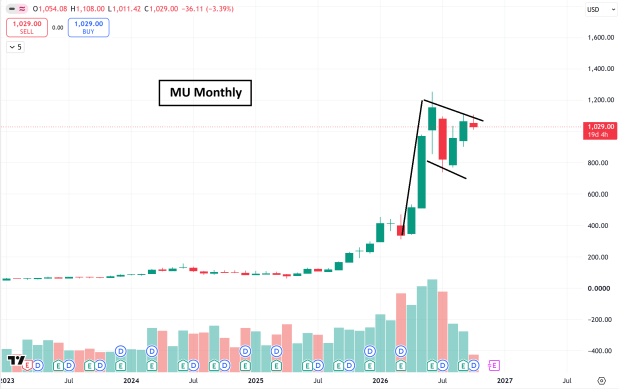
Image Source: TradingView
Bottom Line
Amid critical DRAM bottlenecks, surging gross margins, and expanding enterprise agreements, Micron is well positioned to continue benefiting from the ongoing AI infrastructure boom.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Micron Technology, Inc. (MU): Free Stock Analysis Report
Space Exploration Technologies Corp. (SPCX): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Mentioned In This Article
Latest News
| 9 min | |
| 48 min | |
| 49 min | |
| 1 hour | |
| 2 hours | |
| 3 hours | |
| 3 hours | |
| 4 hours | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 |
