Buy Top-Ranked Tech Stock TSMC Now on the Dip and Hold
Technology, semiconductor, and artificial intelligence stocks jumped on Monday as the bulls attempt to push the Nasdaq back above its 50-day moving average heading into the heart of big tech earnings—Meta, Tesla, and others report later this week.
Now might be time to start buying tech and AI-boosted stocks again after the recent wave of selling because the core fundamentals of the most important companies remain impressive and bullish—even if cracks are showing up across the more speculative names.
Investors need to take a step back from the AI-fear-induced selling and look at the stellar earnings growth picture. Earnings expansion has proven over the long haul to be one of the biggest factors that drives stock prices higher.
The tech stock we dive into today—Taiwan Semiconductor—reported a strong beat-and-raise Q3 on October 15. TSMC’s strong upward earnings revisions earn the chip maker a Zacks Rank #1 (Strong Buy) right now.
Plus, Taiwan Semi has slipped ~14% from its early October records and is finding technical support.
Earnings Growth Tells Investors to Buy Stocks Right Now
Nearly every Zacks sector (15 out of 16) is expected to report YoY growth in the third quarter, highlighting a bullish backdrop beyond AI and Tech. Total third-quarter earnings are projected to jump 24.6% for the S&P 500, on 11.8% revenue expansion. Even taking the Tech sector out of the equation completely, S&P 500 earnings are projected to jump 14.5% in Q3.
But Q3’s strength is already priced into the market in a big way. This is why guidance for Q4 and beyond matters more than anything. Thankfully, the outlook for Q4 earnings jumped from 23.4% in early July to 27.7% before the big banks started reporting.
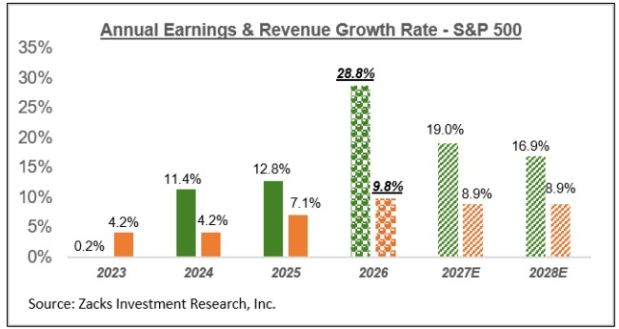
Image Source: Zacks Investment Research
Looking at the full year, total S&P 500 earnings are expected to grow by +28.8% in 2026 on +9.8% higher sales, with growth projected in 15 out of 16 sectors.
Better still, S&P 500 earnings are projected to grow another 19.0% in 2027 and 16.9% in 2028.
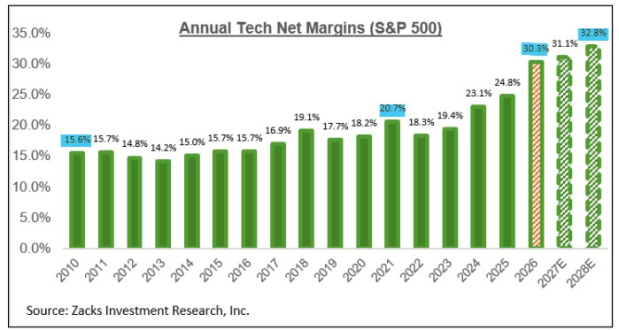
Image Source: Zacks Investment Research
The margins growth is also staggering, with S&P 500 margins projected to jump to 15.3% in 2026 and 18% in 2028, blowing away the previous 2021 peak of 13.2% and nearly doubling 2012.
Annual Tech sector margins are projected to reach 30.3% in 2026 and 32.8% in 2028, doubling 2010’s 15.6% and crushing 2021’s post Covid boom’s 20.7%.
TSMC: Best Tech Stock to Buy Now and Hold Forever
Taiwan Semiconductor Manufacturing Company (TSM) better known as Taiwan Semi or TSMC, is arguably the most critical technology company on the planet. TSMC physically builds and manufactures almost all the cutting-edge semiconductors for Nvidia (NVDA) and most other AI giants.
The pure-play foundry firm reportedly captures 60% of the entire global chip foundry market and 90% of advanced semiconductor manufacturing. Taiwan Semi spent decades building what’s now an impenetrable moat around its leading-edge chip-building business by earning the trust of customers like Apple, Nvidia, AMD, and Qualcomm.
Nvidia and other technology giants rely on TSMC because of its unmatched scale and expertise. Plus, they know that Taiwan Semi is not aiming to compete against them in the chip design business.
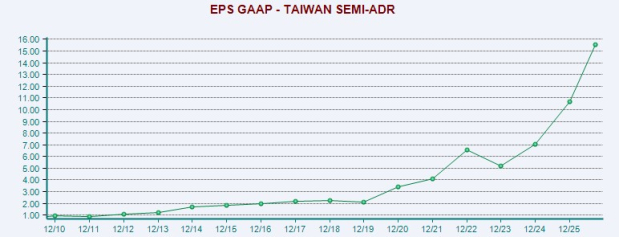
Image Source: Zacks Investment Research
Taiwan Semi is racing to address one of its only potential shortfalls: geopolitical fears, by expanding its manufacturing footprint outside of Taiwan into the U.S., Japan, and elsewhere.
TSMC grew its Q3 earnings by 58% on 41% higher revenue. The company said that 3- nanometer chip shipments accounted for 33% of its total wafer revenue, up from 23% in the year-ago period. More importantly, its most advanced 2-nm chips accounted for 8%, up from 3% in the second quarter.
The chip builder’s expansion at the bleeding edge is strong considering that it didn’t even start volume production on its 2-nm technologies until 4Q25. Advanced technologies, which TSMC defines as 7-nanometer and beyond, accounted for 79% of total wafer revenue up from 74% in the year-ago period.
Taiwan Semi management upped its guidance when it reported on October 15, citing “continued strong demand for our leading-edge process technologies, including the steep ramp-up of our 2-nanometer technology.” TSM’s recent upward earnings revisions earn it a Zacks Rank #1 (Strong Buy).
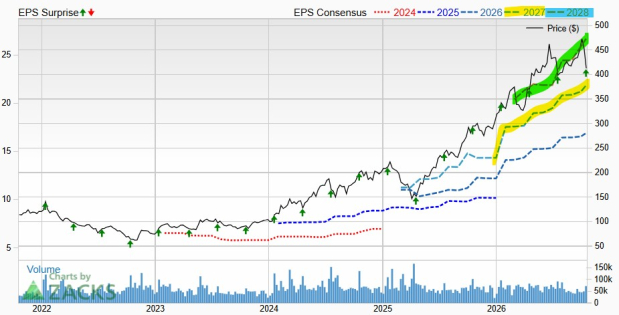
Image Source: Zacks Investment Research
The leading chip builder said earlier this year that it expects to grow its revenue by 30% in 2026 as part of a compound annual growth rate (CAGR) of ~25% between 2024 and 2029. Taiwan Semi’s strong outlook is likely to improve since it has already boosted its 2026 outlook after three straight beat-and-raise periods.
TSMC is projected to grow its revenue by 41% in 2026 and another 33% next year to reach $228 billion, adding more than $100 billion vs. 2025’s ~$122 billion total and more than tripling its 2023 figure. On the bottom line, it’s projected to grow its earnings by 59% in 2026 and 29% next year, doubling its 2025 total ($10.65) in the process ($21.85 a share in 2027).
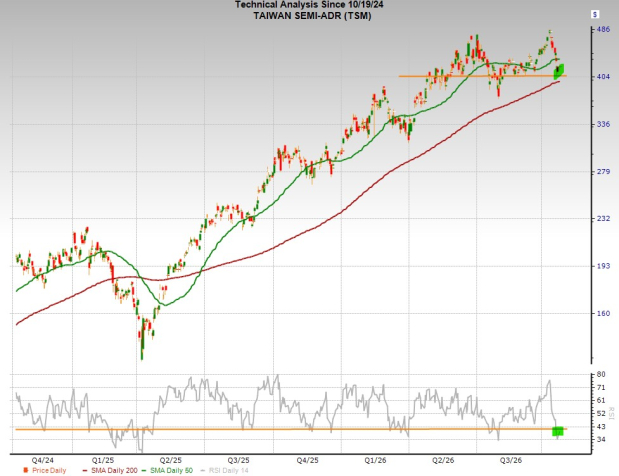
Image Source: Zacks Investment Research
TSMC quadrupled the Zacks Tech sector during the last 20 years, soaring ~4,300%. The dividend-paying chip maker boasts a strong balance sheet with mountains of cash. TSM stock has outclimbed the entire Mag 7 over the last year and outpaced five of the seven in the past decade, lagging only Tesla and Nvidia.
Yet, investors can buy it down ~14% from its early October highs, with an average Zacks price target that implies 29% upside. It is attempting to retake its 50-day moving average after finding support at the technical range highlighted above. Taiwan Semi stock is also trading at some of its more oversold RSI levels in the past several years.
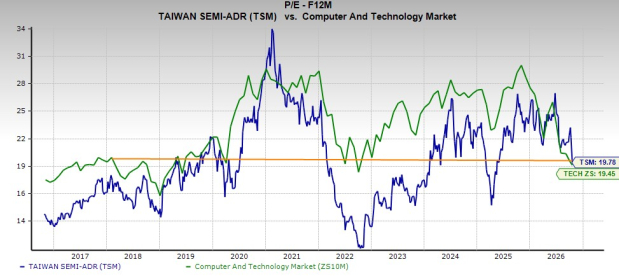
Image Source: Zacks Investment Research
TSMC is trading almost directly in line with the Tech sector and the S&P 500 (and its own 10-year median) despite its outperformance and at a 36% discount to its highs at 19.8X forward 12-month earnings.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
NVIDIA Corporation (NVDA): Free Stock Analysis Report
Taiwan Semiconductor Manufacturing Company Ltd. (TSM): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Mentioned In This Article
Latest News
| 2 hours | |
| 2 hours | |
| 2 hours | |
| 2 hours | |
| 2 hours | |
| 2 hours | |
| 2 hours | |
| 2 hours | |
| 2 hours | |
| 2 hours | |
| 2 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 4 hours |
