Capital One's Discover Payoff Arrives Early As $6.69 Beat Shows Earnings Power, But Interchange And Marketing Headwinds Loom
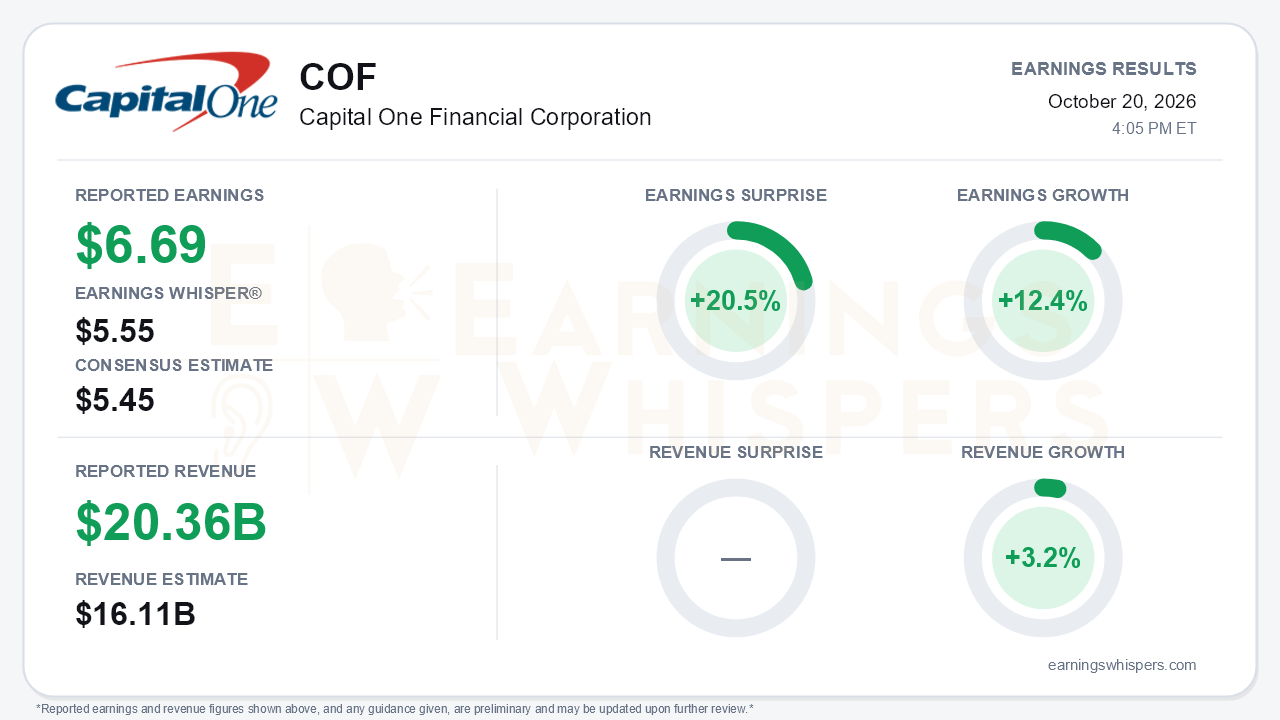
Capital One delivered its strongest quarter since closing the Discover deal. Adjusted earnings of $6.69 per share topped the $5.45 consensus by 20.5% and cleared the $5.55 Earnings Whisper number by a wide margin. Earnings grew 12.4% year over year, and the sequential climb was steep: adjusted EPS has risen from $3.86 in Q4 2025 to $4.42, then $5.81, and now $6.69. GAAP EPS rose to $5.61 from $4.73 in Q2, net of $0.60 in acquisition amortization, $0.42 in Discover integration costs and $0.06 in Brex integration costs. The central development is a change in management's message. On the call, management stopped describing deal-model earnings power as a future promise and said it is now visible in the results. The open question is how much of that power survives a looming interchange cut and a deliberate marketing ramp.
The revenue figures need care. The $20.357 billion figure, up 3.2% year over year, equals total interest income plus non-interest income. Capital One's own measure, total net revenue, was $16.34 billion. Measured against the $16.11 billion consensus, that is a modest beat. The headline 26.4% revenue surprise mostly reflects the gap between those two definitions rather than a blowout top line.
The real story is margin and credit:
- **Margins:** Net interest margin expanded 40 basis points to 8.41%, and management said the structural NIM impacts from the deal have now played out. Domestic card revenue margin reached 17.85%.
- **Pre-provision earnings:** Adjusted pre-provision earnings grew 9% sequentially after a flat Q2.
- **Expenses:** Non-interest expense fell 2%.
- **Credit:** The domestic card charge-off rate dropped to 3.98% from 4.71% in Q2 and 5.10% in Q1, helped by what management called structurally stronger recoveries.
The quality of the beat holds up better than it first appears. The reserve release shrank to $225 million from $662 million, so lower actual losses, not reserve accounting, did the heavy lifting. Two caveats apply:
- **Buybacks:** Diluted shares fell 5% year over year, which flattered per-share growth.
- **Book value:** Tangible book value per share slipped to $102.72 from $105.21. Accumulated other comprehensive loss widened to $10.0 billion from $6.3 billion, and the TCE ratio fell to 9.8%. CET1 still stood at a comfortable 13.8%.
Integration is running ahead of plan. Combined synergies have reached roughly $1.8 billion annualized against a $2.5 billion target, even though earlier commentary had described expense synergies as back-loaded to mid-2027. All Discover front-book card originations now run on Capital One's tech stack, up from 50% last quarter, and the back-book conversion is set to finish in Q1 2027. Discover originations grew year over year for the first time since the deal closed. Legacy Capital One card loans grew about 6%, accelerating from 5.3% in Q2 and 3.9% in Q1. Auto originations rose 22%, and Global Payment Network volume reached about $191 billion.
Bears have legitimate ammunition:
- **Discover card balances:** These are shrinking faster, down 2.9% year over year versus 1.5% in Q2, and management expects contraction for several more quarters. That held total domestic card growth to about 2%.
- **Card delinquencies:** The rate rose 35 basis points to 3.74%. Management characterized the increase as seasonal, but delinquencies are now moving in line with seasonal patterns instead of beating them.
- **Auto credit:** Auto charge-offs rose 16 basis points to 1.59% as the subprime mix normalizes.
- **Funding:** Deposits fell 1%.
- **Interchange:** Management expects the Visa/Mastercard merchant settlement, which faces a final approval hearing in November, to reduce interchange revenue by roughly the size of the remaining synergies.
- **Marketing:** Capital One plans heavier marketing in Q4 and a broader step-up in 2027, alongside continued AI and network investment, which could pressure efficiency ratios.
The 2-point Q3 decline in marketing spend is therefore not a trend to extrapolate.
Investor sentiment became somewhat more positive heading into the report, rising to 0.45 from 0.40. That is a constructive but not euphoric starting point. The stock tells a more cautious story:
- Shares closed at $199.83 before the release, down 3.7% from the opening price after the July report.
- They sat about 1.7% below the 200-day moving average.
- They were 12.4% below the August 14 inter-earnings high of $228.14 and only 5.3% above the October 1 low.
The market spent the quarter giving back a summer rally, even as the fundamental story improved. The Earnings Whispers trend readings are mixed: momentum is positive, while price and AVWAP remain negative.
The bottom line is that Capital One produced the quarter acquisition skeptics were not positioned for. Charge-offs fell sharply, margins widened, synergies arrived early, and management now openly claims the deal's earnings power is in hand. The market setup is more complicated than the surprise implies, however. The interchange settlement threatens to absorb much of the remaining synergy upside, marketing spend is set to rise, and the Discover book is still shrinking. That leaves a credible earnings story facing a stock that has yet to reclaim its trend.
Read our earnings preview for Capital One Financial Corporation: https://www.earningswhispers.com/article/COF/20402
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 1 hour | |
| 5 hours | |
| 5 hours | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 |
Capital One Logs Higher Profit, Revenue as Discover Integration Continues
COF
The Wall Street Journal
|
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-19 | |
| Oct-18 | |
| Oct-18 | |
| Oct-17 | |
| Oct-16 |
Best CD rates today, Friday, October 16, 2026: Earn up to 4.40% APY with multiple offers
COF
Yahoo Personal Finance
|
