SpaceX Crushes Q3 Estimates And Guides To A Revenue Step-Change, But Doubled Capex And Margin Normalization Complicate The Story
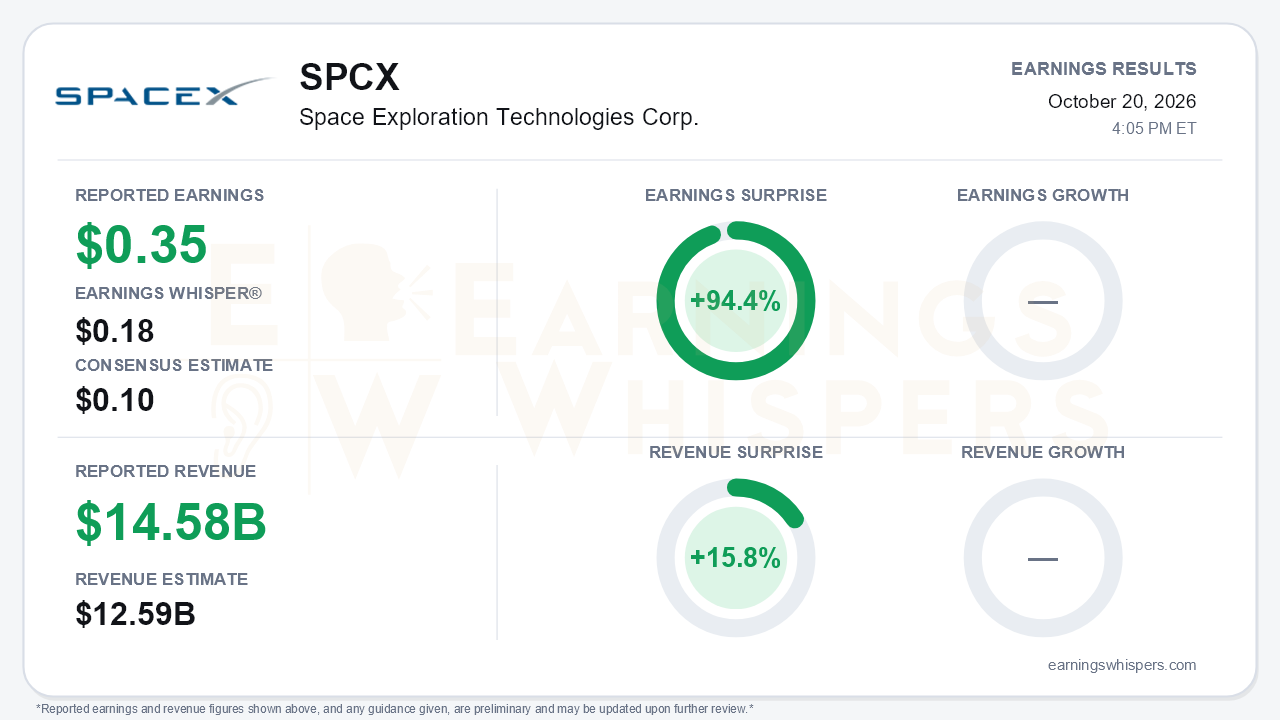
SpaceX delivered a third quarter that was less a beat than a change in scale. The company earned $0.35 per share, against a $0.10 consensus and an $0.18 Earnings Whisper number, a 94.4% surprise. Revenue of $14.575 billion beat the $12.59 billion consensus by 15.8%. Per the company, revenue rose 161% year-over-year, accelerating sharply from 92% growth in the second quarter, when revenue was $7.8 billion. The bottom line swung to $4.4 billion of net income from a $1.1 billion loss a year earlier and a $541 million loss in Q2. The guidance was arguably the bigger headline. Management issued its first Q1 2027 revenue outlook, $33 billion to $37 billion, which is more than double the quarter just reported. That is the central tension. The growth trajectory is steepening dramatically, but so is the capital required to sustain it.
The quality of the beat deserves some scrutiny. Income from operations was $2.8 billion, well below net income of $4.4 billion, so a meaningful share of the bottom line came from below the operating line. Adjusted EBITDA of $8.8 billion, up 306% with a margin near 60% versus roughly 45% in Q2, flatters the picture further. The Connectivity segment's 55% gross margin included about three points from a one-time tariff refund, and management guided Q4 gross margin back to Q2 levels. The Cursor acquisition also carries $23 billion of retention stock-based compensation over roughly three years. That included $1.2 billion in Q3 alone, which held Super Intelligence segment operating income to $431 million despite $5.0 billion of segment adjusted EBITDA.
Operationally, the SI segment is now the engine. Revenue reached $7.6 billion, up from $2.6 billion in Q2, on activated cloud agreements, $608 million from Cursor after a mid-quarter close, and growing model and software sales. Grok enterprise customers above $1 million in run-rate rose 50% sequentially, and Grokbot reached 800,000 paid weekly users within months of launch. Nameplate compute grew to 1.7 GW from 1.4 GW and was expected to reach about 2.2 GW by the end of October. Management lifted its year-end target to 2.5-3 GW and its end-2027 target to roughly 13 GW, describing itself as "highly confident," with an upside plan for more than 20 GW. Pricing is also moving in the company's favor. Compute is now tracking above $50 per watt, and short-term contracts are renewing higher. Backlog climbed to $63 billion from $47.5 billion, with about $42 billion expected within a year.
Connectivity remained healthy. Revenue grew 69% to $5.2 billion and ARPU rose to $69 from $66. Aviation contracts now cover about 12,000 aircraft, roughly a quarter of the addressable fleet. Starlink Mobile monthly users rose 37% sequentially to 22 million. There were softer spots, though. Consumer net adds slipped to 1.6 million from 1.7 million on kit inventory constraints, and Space segment revenue grew only 6% year-over-year.
The forward catalysts are numerous, but bears have legitimate ammunition:
• **Capex:** The Q4 capex guide of $35-40 billion is roughly double the Q2 framing of spending "similar to" $18.4 billion, which raises funding and debt questions.
• **Timelines:** Several schedules slipped. Starship cadence was reframed to weekly in the first half of 2027 and twice weekly in the second half, versus daily "a year from now" on the Q2 call. The first tower catch moved to Flight 15, and U.S. Starlink Mobile service slid to early 2028.
• **Pricing exposure:** Power, cooling and GPU supply remain the gating constraints, and reliance on short-term compute contracts exposes revenue to pricing swings.
• **Tesla merger:** The special-committee review of a potential combination adds conflict-of-interest overhang and requires approval from a majority of all Tesla shares.
On the positive side, Starship's first revenue-generating mission deployed V3 satellites, the FCC approved 15,000 Mobile V2 satellites, and a low-band spectrum deal positions SpaceX as a would-be U.S. carrier.
The market setup is more complicated than the surprise implies. Shares entered the report at $147.96, up 26.1% since the open after the August report. That is well off the $105.11 inter-earnings low but 16.1% below the $176.42 high set October 6. The stock was sitting just 1.7% above its 200-day moving average, suggesting investors had already given back much of the pre-report run. Investor sentiment remained clearly negative at -0.45, only modestly improved from -0.49 after the prior report. Expectations, in other words, were not euphoric heading into a quarter that cleared them by a wide margin. The AVWAP trend reading is positive, consistent with buyers still holding the upper hand since the last report.
The bottom line is that SpaceX posted an exceptional quarter and paired it with guidance implying another step-change in revenue. It also lifted its compute ambitions and secured better pricing. Still, part of the Q3 profit picture was flattered by one-time and non-operating items, margins are guided lower, capex is doubling, and several hardware timelines slipped. Investors with still-skeptical sentiment now have to weigh a credible hypergrowth story against the execution and financing demands of building it.
Read our earnings preview for Space Exploration Technologies Corp.: https://www.earningswhispers.com/article/SPCX/20615
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 20 min | |
| 21 min |
SpaceX Spikes As Analysts Hike Stock Targets. $1T Revenue Target 'Not Impossible,' Musk Says
SPCX +9.36%
Investor's Business Daily
|
| 23 min | |
| 27 min | |
| 31 min | |
| 35 min | |
| 36 min | |
| 36 min | |
| 44 min | |
| 46 min | |
| 50 min | |
| 57 min | |
| 58 min | |
| 58 min | |
| 1 hour |
