T-Mobile's Planned Churn Spike Puts A Bruised Stock's Growth Story To The Test
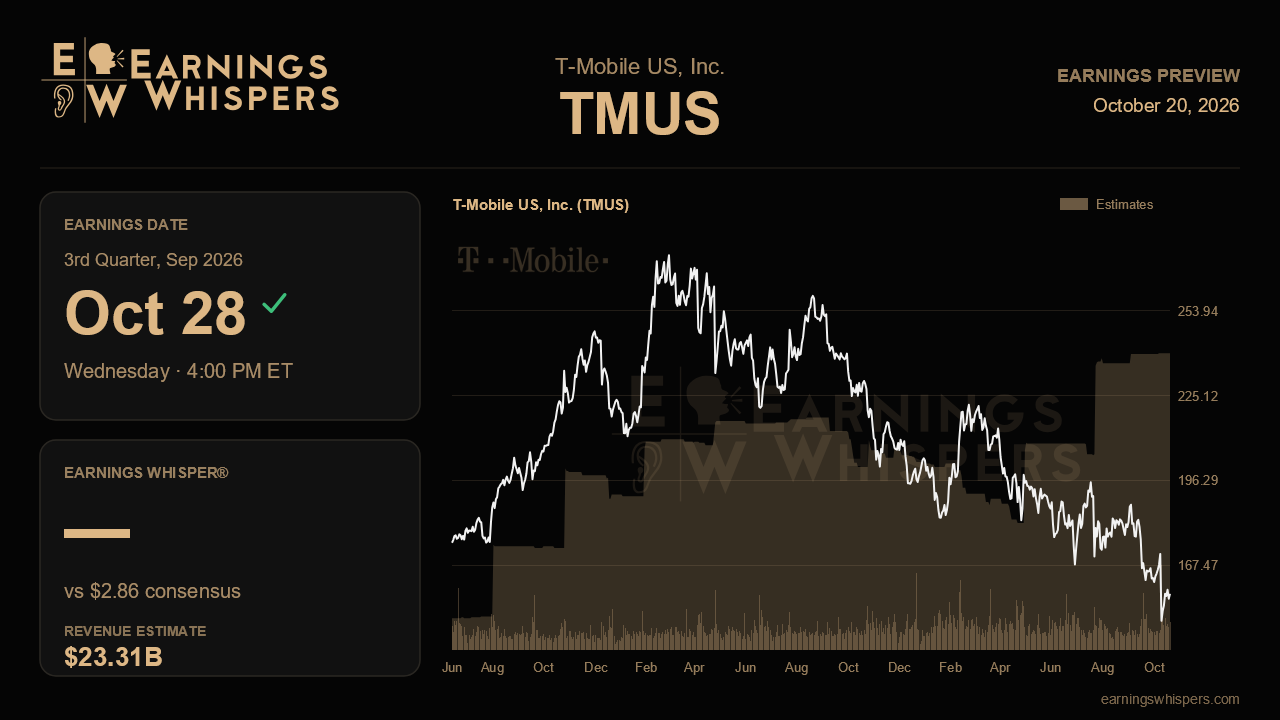
T-Mobile heads into its third-quarter report having told the market in advance that this would be an ugly quarter on one important measure. Management guided postpaid account net additions to only about 250,000, a sharp drop driven by a deliberate rate-plan modernization that it expected to push churn higher for a while, mostly among smaller-line accounts. The stock has since fallen 11.2% while the S&P 500 gained 3.7%. That raises a simple question for the October 28 release after the close: is the pain contained to what was flagged, or is it spreading into the metrics that drive earnings?
Wall Street expects earnings of $2.86 per share on revenue of $23.31 billion. That works out to roughly 10% EPS growth and about 6% revenue growth from a year ago, which is solid for a wireless carrier but a clear step down from the pace earlier in the year. EPS is also expected to fall from the $3.13 reported last quarter. Management has already set up that slowdown. It guided third-quarter core EBITDA to about $9.4 billion, up roughly 8%, and said full-year EBITDA growth would ease from around 12% in the first half to high single digits in the second half as merger-related comparisons get tougher. Postpaid service revenue growth had already slowed to 13% from 15%, and total service revenue growth to 9% from 11%. A number near the $9.4 billion EBITDA target would show the slowdown is the mechanical one management described and not a weakening in the business underneath.
The rate-plan change matters most because it is the trade management is asking shareholders to accept. The bet is that moving customers onto modern plans lifts revenue per account enough to more than make up for the accounts lost. Last quarter management said it now leans toward about 3% postpaid ARPA growth for the year, the top of its 2.5% to 3% range. If ARPA moves toward that 3% while account net adds land near 250,000, the strategy looks like it is working as designed. If net adds come in well below that figure, or ARPA fails to rise enough to offset them, the plan starts to look more like attrition than optimization. Holding the full-year account net-add target of 950,000 to 1.05 million would require a strong fourth-quarter rebound, so any change to that range will say a lot about management's confidence.
The softer revenue lines deserve attention too. Management said wholesale and other revenue would be roughly flat for the year as dish and TracFone traffic rolls off. Prepaid faces pressure on both subscribers and revenue per user, partly offset by customers moving up to postpaid. These are not core to the thesis, but they help explain why revenue growth is lagging the headline postpaid strength.
The bull case still rests on cash. Adjusted free cash flow guidance has been raised in each of the last three updates and now stands at $18.4 billion to $18.8 billion. The full-year targets of about $77 billion in service revenue and roughly $10 billion in capital spending were reaffirmed. A fourth increase would be harder to deliver, since the most recent one leaned on lower cash taxes rather than stronger operations. A firm reaffirmation would probably satisfy the market. Updates on the newer catalysts, including the direct-to-device joint venture agreement, the Capital One Visa card and fixed wireless broadband momentum, would add support but are unlikely to move results this quarter.
Sentiment has edged slightly more bearish than before the last report, though the move is modest. The stock price says more. At $156.09, shares sit far below the 200-day moving average of $189.09 and near the bottom of their post-earnings range of $147.90 to $189.87. That range is well below last quarter's $165.66 to $200.63 band. The market has priced in a meaningful slowdown, which lowers the bar somewhat. The report comes down to whether the churn spike stays inside the box management drew around it. If it does, and ARPA and cash flow hold, the selloff may look overdone.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 47 min | |
| 1 hour | |
| 1 hour | |
| 1 hour | |
| Oct-20 | |
| Oct-18 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 |
