Equinix Must Prove Its Record Guidance Raise Can Survive A Steep CapEx Ramp
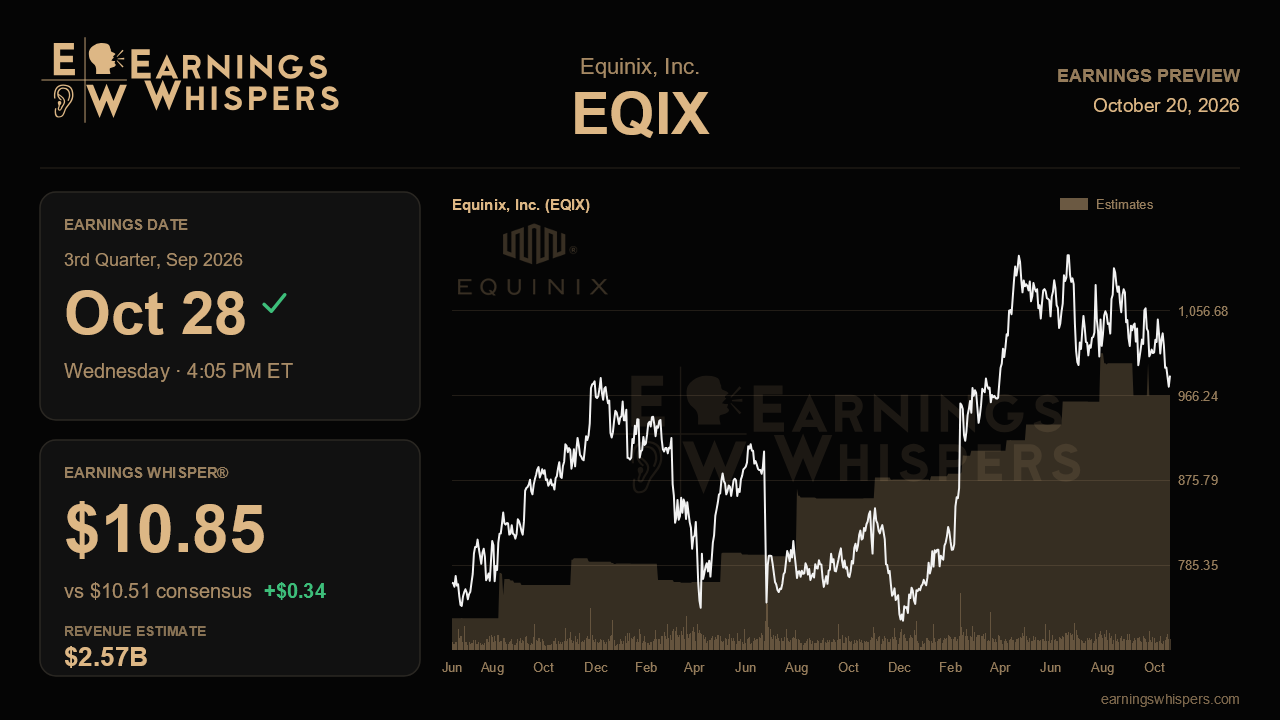
Three months ago Equinix delivered what management called the largest guidance raise in its history, lifting both its 2026 outlook and its multi-year targets on the back of accelerating AI-driven demand. The stock's response since then has been anything but celebratory. Shares have fallen about 8% while the S&P 500 gained roughly 4%, leaving the data center operator trailing the market by more than 12 points. That gap sets up the third-quarter report, due after the close on October 28, as a referendum on a single question: is the market right to worry about the cost of growth, or is it underpricing the growth itself?
The Street expects non-GAAP earnings of $10.51 per share on revenue of about $2.57 billion, an 11% increase from a year ago. That is solid double-digit growth for a business built on recurring colocation and interconnection fees, and it sits squarely on the 11% to 12% revenue growth management now projects for the full year. The per-share estimate implies roughly 7% growth from the $9.83 posted a year earlier, though the Earnings Whisper of $10.85 sits about 3% above consensus, a meaningful gap that suggests the informal bar is closer to last quarter's $10.67. Notably, the revenue consensus is below the $2.63 billion Equinix reported last quarter, which looks like a forgiving top-line hurdle if demand is as strong as management described. On the annual view, the company guides 2026 FFO to $42.69 to $43.29 per share, and the $43.05 consensus lands in the upper half of that range, signaling confidence without demanding a heroic beat.
The operating story to test is acceleration. Monthly recurring revenue growth has climbed from 8% to 11% over four quarters, annualized gross bookings rebounded 23% to $424 million, and net interconnections hit a record 9,700. Interconnections matter because they deepen customer lock-in and carry high margins, so another strong print there would support the target of roughly 51% EBITDA margins this year and 53% or better by 2029. Validation would look like MRR growth holding at 11% or better, bookings staying well above the soft first-quarter pace, and churn remaining near the 1.7% to 1.8% band. Early traction from Fabric GeoZones, which had about 80 enterprises in preview, and continued momentum in AI-related wins would add texture to the demand case.
The challenge lies on the other side of the ledger. Capital spending guidance jumped to $5 billion to $6 billion for 2026 from about $4.1 billion a quarter earlier, with $5 billion to $7 billion per year planned through 2029. Management also flagged leverage rising by roughly one turn and a blended cost of capital about 150 basis points higher. That plan only works if new capacity fills quickly, which puts the promise to double second-half cabinet deliveries and pull more than 7,000 cabinets forward from 2027 into the fourth quarter under a microscope. Any sign of slippage, whether from power constraints in tight metros or from the transition under a new chief product officer and reorganized global markets leadership, would feed the bear case that spending is running ahead of returns.
Sentiment has swung sharply, with the bullish reading rising to 63.4% from 16.3% heading into last quarter, even as the stock slid below its 200-day moving average near $1,000 and now trades just above its post-earnings low of about $962. That combination of upbeat sentiment and a weak tape suggests investors like the story but distrust the price of executing it.
Ultimately, this report needs to show that the delivery schedule is on track and that bookings are strong enough to absorb a much larger capital base. If Equinix can pair steady acceleration with clear evidence that its accelerated build is filling as planned, the record raise looks durable. If not, the market's skepticism about capital intensity may prove justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-20 | |
| Oct-20 | |
| Oct-16 | |
| Oct-15 | |
| Oct-14 | |
| Oct-09 | |
| Oct-08 | |
| Sep-28 | |
| Sep-22 | |
| Sep-21 | |
| Sep-21 | |
| Sep-17 | |
| Sep-14 | |
| Sep-14 |
