Chipotle's Turnaround Faces A Cyclospora Test As Shares Sink Toward Post-Earnings Lows
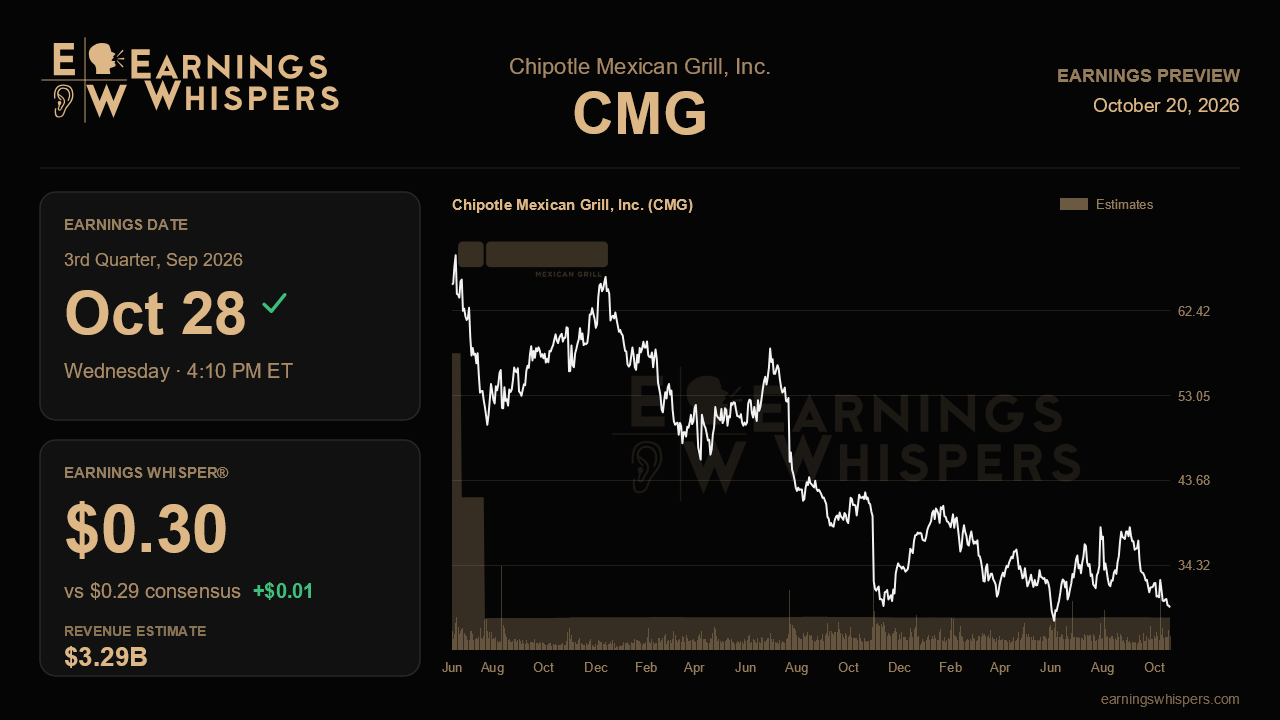
Three months ago, Chipotle delivered the kind of quarter a turnaround story needs: positive comparable sales, positive traffic and its first full-year guidance raise in more than a year. The market has since treated that progress as if it never happened. Shares have fallen 18.5% since the last report while the S&P 500 gained about 4%, and the stock now trades just above its post-earnings low. When Chipotle reports third-quarter results after the close on October 28, the question is simple but consequential: was the late-summer slowdown a temporary detour or the start of a stall?
Wall Street expects earnings of $0.29 per share, flat with a year ago, on revenue of roughly $3.29 billion, up 9.5%. The Earnings Whisper sits a penny higher at $0.30, a hint that some investors see modest upside but hardly a signal of elevated expectations. The revenue forecast actually dips slightly from the prior quarter's $3.35 billion, and with management guiding to only about 1% comparable sales growth, much of the year-over-year gain has to come from new restaurants rather than busier existing ones. Flat earnings on near double-digit sales growth tells you margins remain the weak link.
That comp guide is the crux of the report. Management framed the third quarter as roughly 3% underlying growth less about 200 basis points of drag from an industry cyclospora scare that hit demand in the second half of July. Chipotle said it was not directly implicated, since its lettuce comes from California, but it also noted that broader consumer caution had softened trends and that this quarter carries the toughest comparison of the year. A comp near or above 1% would validate the idea that the underlying business kept improving beneath the noise. Anything meaningfully below that, or commentary suggesting softness persisted into October after the cyclospora headlines faded, would challenge the claim that demand is genuinely recovering. Transaction growth matters more than the headline figure here, because traffic was the most encouraging part of last quarter's +1% reading.
The self-help agenda deserves scrutiny too. The high-efficiency equipment package was in more than 1,000 restaurants last quarter with a target of about 2,000 by year end, and those stores have been producing comps hundreds of basis points ahead of the rest. Evidence that the rollout stayed on pace, along with updates on rewards membership, the protein limited-time offers planned for the back half and the brand messaging refresh under a new chief brand officer, would show the drivers behind the full-year raise are intact. Management also said the lower-income and younger cohorts that had been most pressured were improving fastest; any reversal there would be telling.
Margins are the other swing factor. Restaurant-level margin fell 220 basis points last quarter to 25.2% as beef and freight inflation pushed cost of sales to 29.7%, and management is deliberately pricing below inflation, with full-year pricing near the high end of a 1% to 2% range. Investors can accept that trade-off if traffic is rewarding it. Another steep margin decline paired with a weak comp would be far harder to defend.
Sentiment has swung from mildly bullish before the last report to clearly bearish now, and the stock sits well below its 200-day moving average of about $34.52, near the bottom of a $29 to $39 post-earnings range. That pessimism lowers the bar somewhat. Ultimately, the report hinges on whether Chipotle can show that roughly 3% underlying momentum survived the cyclospora disruption and that its full-year low-single-digit comp outlook still holds. If it can, the selloff looks overdone; if it cannot, the turnaround narrative will need rebuilding.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-19 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 |
