UBS Needs Its Earnings Growth Story To Hold As Shares Sink Toward Post-Report Lows
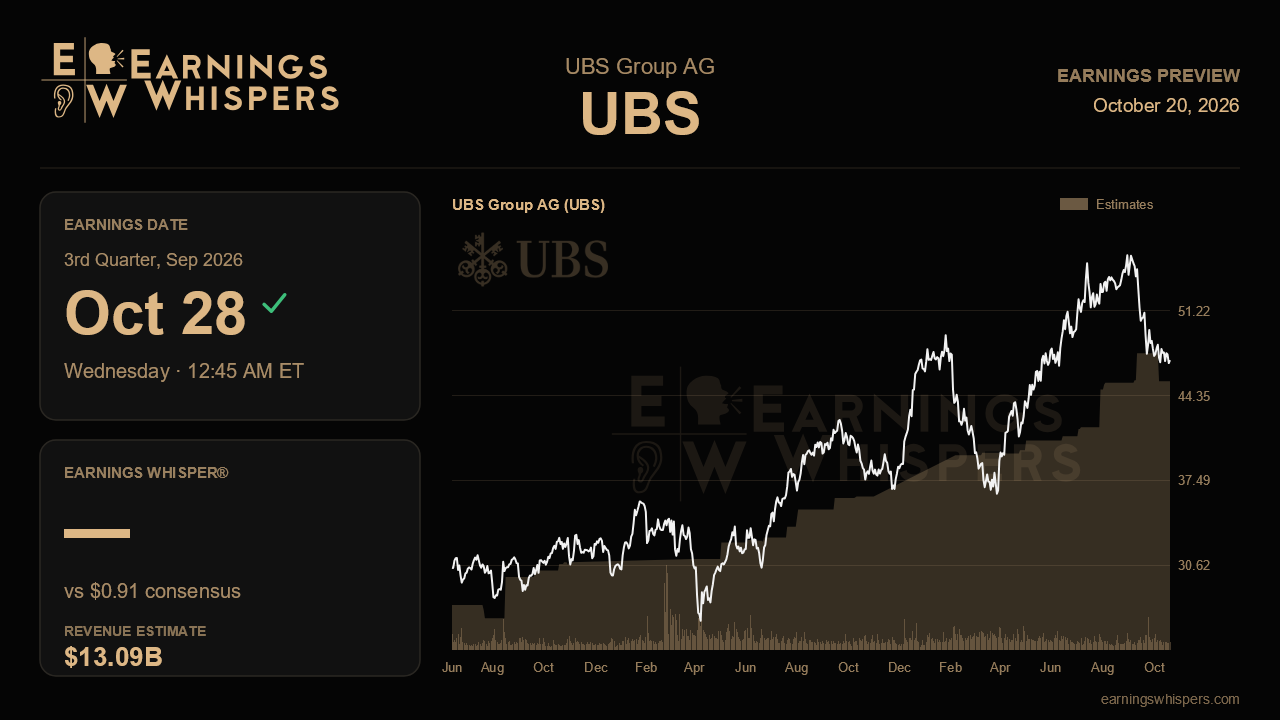
UBS heads into its third-quarter report with an awkward split between its numbers and its share price. Wall Street expects earnings per share to climb nearly 20% from a year ago, yet the stock has slid more than 10% since the last report while the broader market moved higher. When estimates point up and the stock points down, the report becomes a referendum on whether the profit trajectory is real and durable or whether investors are quietly bracing for something the forecasts have not yet captured.
The consensus calls for earnings of $0.91 per share, up from $0.76 in the same quarter last year and a step above the $0.87 delivered last quarter. That sequential gain matters. It suggests analysts believe UBS can keep stacking profit improvements rather than simply lapping an easy comparison. The revenue picture looks far stranger at first glance, with the Street modeling roughly $13.09 billion, about 26% below the year-ago figure and well under the $18.08 billion reported last quarter. A drop that steep alongside rising earnings is unusual for a bank, and the gap may reflect differences in how revenue is being measured rather than a true collapse in business activity. Either way, the earnings line is the cleaner gauge of expectations, and it implies that profitability per dollar of revenue must improve meaningfully.
That is the crux of the quarter. For a firm whose strategy centers on global wealth management, backed by its Swiss universal bank, asset management arm and investment bank, earnings growth of this magnitude typically requires some combination of healthy client activity, stable fee income from invested assets and disciplined expenses. If the top line genuinely softens while profits rise, the burden shifts almost entirely to cost control and credit quality. Evidence that wealth management fees and client flows are holding up would validate the idea that UBS earns more from a steadier, recurring revenue base. A beat driven mainly by lower provisions or one-time items would be less convincing, and a quarter in which expenses fail to fall in line with revenue would challenge the margin story the consensus is built on.
Sentiment has warmed noticeably even as the stock has cooled. Bullish readings have risen to about 62% from roughly 45% heading into the prior report, suggesting a growing camp sees the selloff as overdone. That optimism raises the bar somewhat: a merely in-line result may not satisfy those positioned for a rebound, while a clean beat with solid underlying drivers could find a receptive audience given how far the shares have fallen.
The chart reinforces the sense that the stock is at a decision point. At about $46.99, UBS sits just beneath its 200-day moving average of $47.09 and less than 1% above its post-earnings low of $46.54, well off the $55.99 high set earlier in the period. The current range is narrower than last quarter's swing between $42.62 and $55.15, but the stock is pressing on the bottom of it. A disappointing report could push shares below support, while a convincing one could help reclaim the long-term trend line.
Ultimately, the report needs to show that UBS can grow earnings on the strength of its core franchise rather than on accounting tailwinds or cost cuts alone. If the quality of earnings matches the headline number, the recent underperformance starts to look like an opportunity. If the profit gain looks thin beneath the surface, the market's skepticism will appear well founded.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 7 hours | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 | |
| Oct-19 | |
| Oct-19 | |
| Oct-19 | |
| Oct-18 | |
| Oct-17 | |
| Oct-16 | |
| Oct-16 |
