Ameriprise Faces A Flow Test As Comerica Exits And Huntington Waits In The Wings
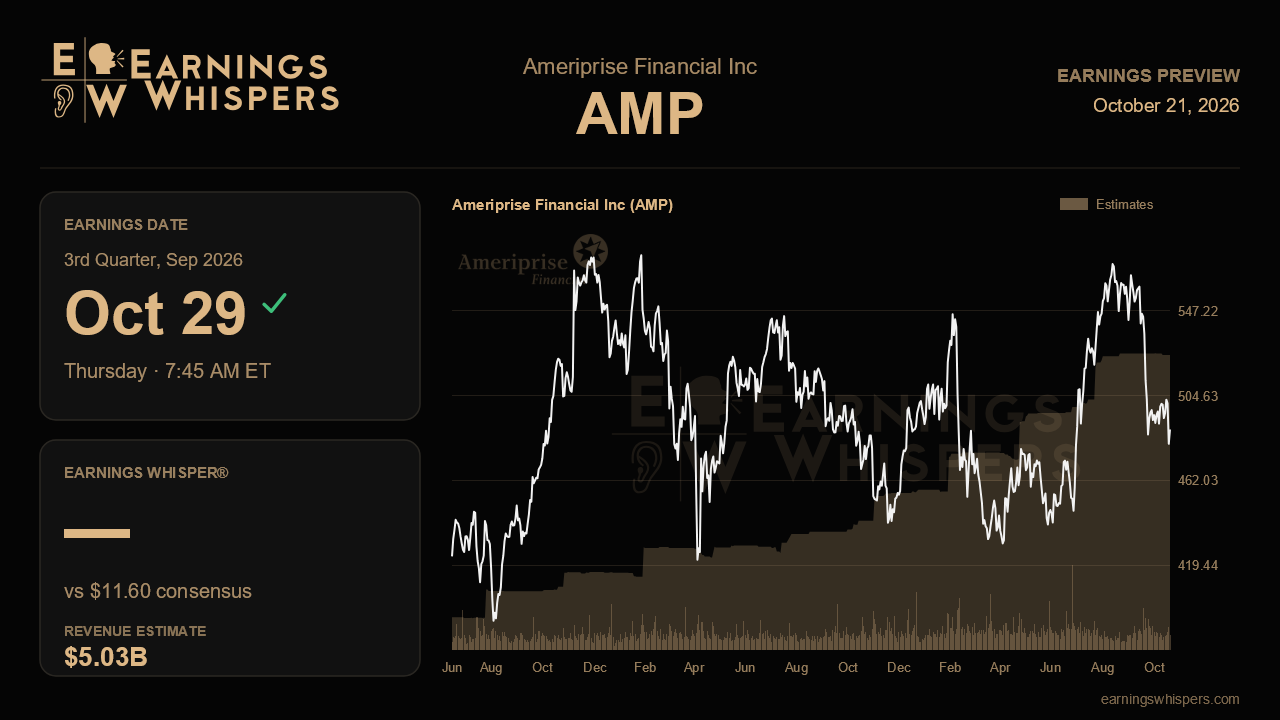
Ameriprise heads into its third-quarter report with a split personality that the market has chosen to punish. The earnings engine has been accelerating for a year, with adjusted EPS growth climbing from 12% to 22% over four quarters and return on equity reaching 55%. Yet the stock has fallen 8.2% since the last report while the S&P 500 gained 4%, a 12-point gap that suggests investors care less about record profitability than about soft client flows. This quarter is the one where the flow problem should look its worst, because the Comerica departure wraps up in September, while the Huntington offset does not arrive until the fourth quarter.
The Street expects EPS of $11.60 on revenue of about $5.03 billion, which would mean roughly 17% earnings growth on 5% revenue growth. That is still a strong result, but it marks a step down from the 22% EPS pace and 13% revenue growth posted last quarter. Part of that reflects tougher comparisons, since the year-ago quarter delivered $9.92 a share. Sequentially, the bar asks for about a 5% lift from the $11.07 reported in the second quarter, a modest ask if markets cooperated and expenses stayed contained. Management did not raise its outlook last time, instead reaffirming mid-single-digit firmwide G&A growth, flat asset management G&A and a capital return target of 85% to 90% of earnings. With capital return running at 91% last quarter, holding near the top of that range would reinforce the earnings-per-share math through a shrinking share count.
The heart of the story is client flows. Total client flows slid from a record $13.3 billion in late 2025 to $4.2 billion and then $3.1 billion, with management pinning the weakness on accelerating Comerica outflows, seasonal tax payments and a recruiting market it described as irrational, where competitors offer deals with paybacks stretching to eight years. Another weak number this quarter would not by itself break the thesis, since roughly $19 billion of Comerica assets were scheduled to leave by quarter end. What matters is whether management can show the underlying franchise is growing beneath that drag. Management said third-quarter recruiting looked even stronger, so evidence of improving advisor hiring, plus any confirmation that the roughly 260 Huntington advisors and $28 billion in assets remain on track for fourth-quarter onboarding, would validate the claim that the transition will more than offset the loss. A slip in Huntington timing or further deterioration in organic flows outside Comerica would challenge it.
Asset management is the other swing factor. The segment grew operating earnings 23% last quarter with margins of 43%, well above the 35% to 39% target, and the back-office transformation was due to finish this quarter. Sustaining margins in the low 40s while net outflows continue narrowing from $6.5 billion would confirm that the efficiency gains are durable rather than market-driven. On the softer side, certificate balances have been shrinking, cash earnings were flat, and Retirement & Protection earnings lagged on variable annuity outflows. The $46.6 billion sitting in third-party money market funds is a latent tailwind if rate cuts push clients back into advisory products, and any sign of that redeployment would be welcome.
Sentiment has improved from clearly bearish before the last report to slightly bullish now, but the stock tells a more cautious story. At $487.67, shares sit below the 200-day moving average of $493.21 and near the bottom of a post-earnings range spanning roughly $478 to $573. That positioning implies limited enthusiasm is priced in, which could cushion a messy flow print if earnings hold up.
Ultimately, this report must convince investors that weak headline flows are a temporary, explainable artifact of the Comerica exit rather than a sign that Ameriprise is losing ground in a costly recruiting war. If earnings keep compounding and management can point credibly to Huntington and a stronger recruiting pipeline, the gap between the operating story and the stock price becomes hard to justify.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-19 | |
| Oct-19 | |
| Oct-19 | |
| Oct-15 | |
| Oct-09 | |
| Oct-08 | |
| Oct-08 | |
| Oct-06 | |
| Oct-01 | |
| Oct-01 | |
| Sep-30 | |
| Sep-29 | |
| Sep-25 | |
| Sep-24 |
