AT&T Beats And Raises As Service Growth Accelerates, But Fiber ARPU Erosion And Higher Leverage Temper The Upgrade
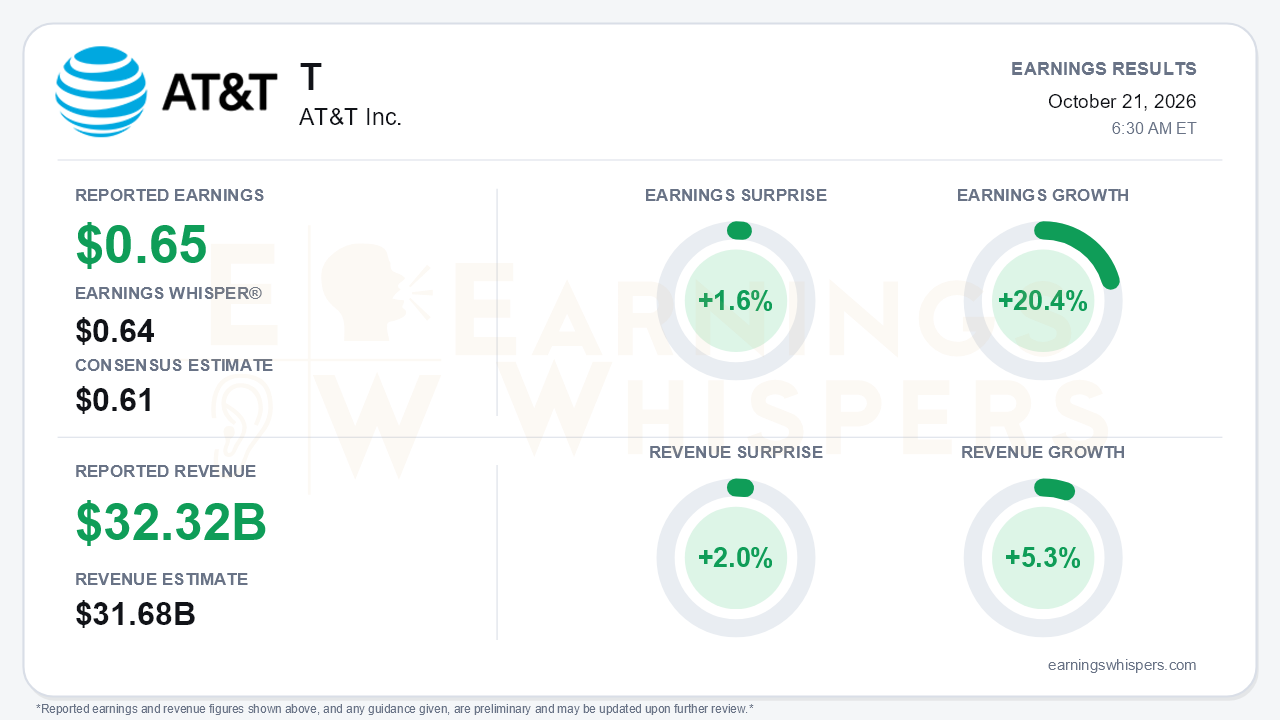
AT&T delivered a third quarter that extended its acceleration story. Adjusted EPS of $0.65 topped the $0.61 consensus and edged past the $0.64 Earnings Whisper number, a 1.6% beat. Earnings grew 20.4% year over year, the second straight quarter of roughly 20% adjusted EPS growth. Revenue of $32.32 billion rose 5.3% and beat consensus by 2.0%. Management raised 2026 adjusted EPS guidance to about $2.40 from $2.25 to $2.35. The central tension is that the top-line momentum is real, while the earnings raise and the cash story are less clean than the headline implies.
The gap between GAAP and adjusted results is wide. Diluted EPS from continuing operations was just $0.13, against $1.29 a year ago. The current quarter absorbed a $2.6 billion non-cash impairment on the held-for-sale Mexico wireless business and roughly $800 million of employee separation charges, with the separation cash largely due in 2027. The year-ago figure was inflated by the DIRECTV sale gain. On an adjusted basis the trend is healthy: adjusted operating margin expanded to 23.5% from 21.3%, and adjusted EBITDA rose 5.4% to $12.5 billion.
The quality of the guidance raise deserves scrutiny. On the call, management attributed most of the EPS increase to lower depreciation and amortization once Mexico moved to held-for-sale, not to stronger operations. Similarly, part of the 18.9% jump in Advanced Connectivity operating income came from lower depreciation on fully depreciated legacy assets. Segment EBITDA margin was flat at 41.8%, and the more modest operational lift shows up in the nudge of 2026 EBITDA growth to the upper portion of the 3% to 4% range.
The revenue trajectory is the strongest part of the report:
- Consolidated service revenue growth stepped up from 1.4% in Q1 to 2.7% in Q2 and 3.8% in Q3.
- Advanced Connectivity service revenue accelerated from 3.6% to 5.1% to 6.1%.
- Wireless service revenue growth climbed from 1.7% to 3.3% to 5.0%.
- Postpaid phone ARPU went from flat in Q1 to up 4% on pricing actions, with churn holding at 0.92%.
- Advanced home internet revenue jumped 23.4%, helped by the Lumen fiber acquisition.
The company posted a record 769,000 total consumer and business internet net adds, including 442,000 fiber and 327,000 fixed wireless. The consumer-only figure cited on the call was 696,000. Convergence reached 42.8% of advanced home internet households.
The soft spots are not trivial, and bears have legitimate ammunition. Fiber ARPU fell 4% year over year, sharply worse than the 1.3% decline in Q2. Management guided to a similar drop in Q4, citing introductory pricing, convergence discounts and lower-ARPU acquired customers. Postpaid phone net adds slowed to 379,000 from 432,000. Q4 EBITDA faces higher acquisition costs and about $100 million in unfavorable vendor settlements. Cash flow is also less impressive than the earnings line:
- Quarterly free cash flow of $5.0 billion was only marginally above last year's $4.9 billion.
- Nine-month free cash flow of $12.1 billion trails the prior year.
- Savings from the roughly $1 billion annual capex cut for 2027-2028 and lower cash taxes are being offset by higher interest costs and device working capital.
- The Mexico exit removes roughly $400 million to $500 million of annual free cash flow.
Net leverage rose to 3.13x from 2.68x after the EchoStar spectrum close, and the 2.5x target now slips to "during 2029." A CFO transition after year-end adds a layer of execution uncertainty.
On the other side, the forward catalyst list is substantial:
- A fiber joint venture with GIP and CPP Investments, with proceeds expected in 2027 for debt paydown.
- Proceeds from the Mexico sale, also expected in 2027.
- A multi-year Corning supply agreement.
- Hyperscaler fiber work with AWS and Microsoft.
- Progress on copper retirement, with more than 100 wire centers fully off legacy services.
The $10 billion 2026 buyback remains on track, and 2027 free cash flow guidance of $19 billion-plus was reaffirmed despite the capex reduction.
Investors were not leaning in ahead of the print. Earnings Whispers sentiment slipped from -0.055 to -0.100, a modest move further into negative territory. Shares closed at $23.42 the day before the report, essentially unchanged (+0.2%) from the open after the July release. That price sits 6.7% below the 200-day moving average of $25.09 and 13% below the mid-September high of $26.93. The stock was only 6.6% above the October 9 low of $21.96. The Earnings Whispers trend readings are split: sequential growth and momentum are positive, while price trend and AVWAP remain negative. That split reflects a stock whose fundamentals have improved faster than its chart.
The bottom line is that AT&T delivered the operating acceleration its strategy promised and raised its outlook. However, the EPS raise leans on accounting relief from Mexico, fiber pricing is eroding faster, and the deleveraging timeline has stretched. With sentiment slightly negative and shares well off their highs, the report gives the market a credible growth story to reassess. Converting that growth into cleaner cash flow and faster debt reduction remains the unresolved test.
Read our earnings preview for AT&T Inc.: https://www.earningswhispers.com/article/T/20434
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 2 hours | |
| 2 hours | |
| 3 hours | |
| 3 hours | |
| 5 hours |
AT&T Earnings Top Views As Wireless Subscriber Growth Underwhelms
T -6.26%
Investor's Business Daily
|
| 5 hours | |
| 5 hours | |
| 5 hours | |
| 5 hours |
AT&T Lifts Profit Outlook on Continued Postpaid Phone, Internet Growth
T -6.26%
The Wall Street Journal
|
| 5 hours | |
| 5 hours | |
| 7 hours | |
| 8 hours |
