Bristol Myers Must Prove Its Guidance Raise Was Real As Eliquis Tailwind Arrives
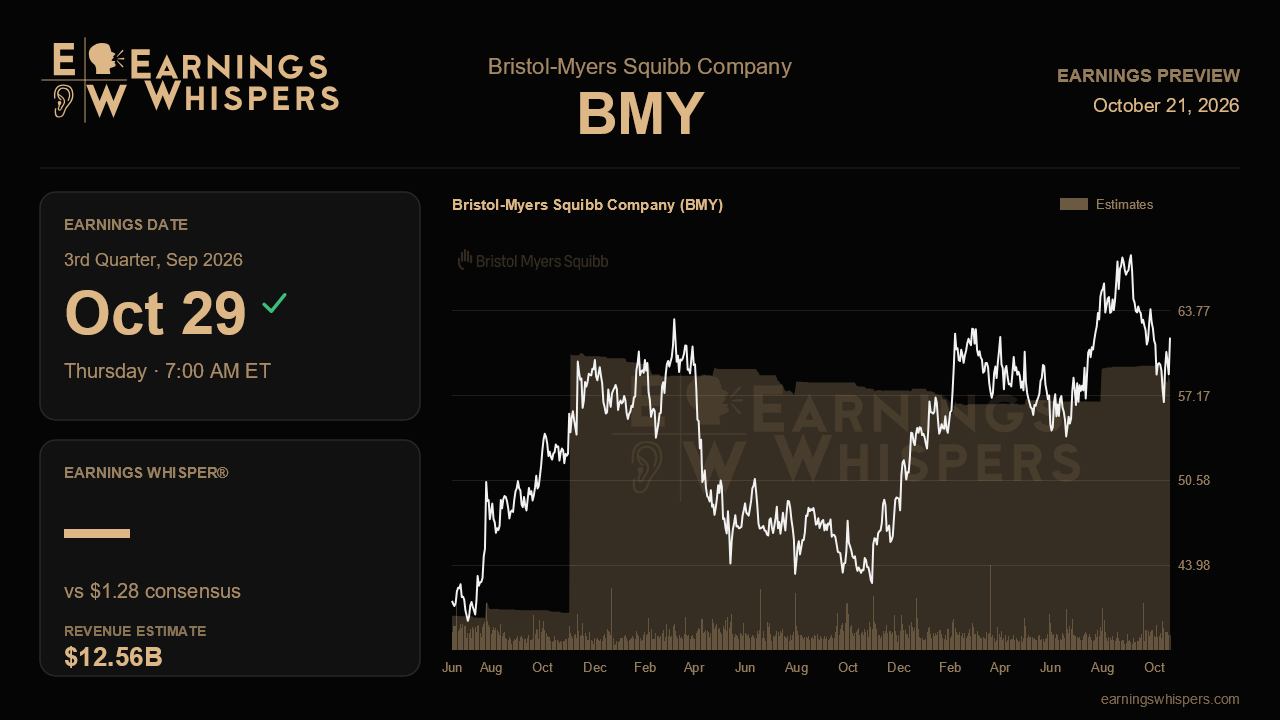
Three months ago Bristol Myers Squibb did something it had not done all year: it raised its outlook outright, rather than merely reaffirming it or hinting at the upper end. The market has largely shrugged. The stock has slipped about 1.6% since that report while the S&P 500 gained roughly 4.5%, and sentiment toward the name has cooled noticeably. That gap between improving fundamentals and a skeptical tape makes the third-quarter report, due before the open on October 29, a referendum on whether the raise reflected durable momentum or a well-timed quarter.
On the surface, the numbers the Street is looking for are unremarkable. Consensus calls for earnings of $1.28 per share on revenue of $12.56 billion. That implies sales growth of about 2.8% from a year ago but a 21.5% drop in per-share profit from $1.63, and a sequential step down from the $2.04 and $12.97 billion posted last quarter. A profit decline of that size sits awkwardly beside a company that just lifted its full-year view, so how management explains the earnings bridge, whether through spending, charges or timing, will matter as much as the headline figure. More telling is the disconnect on the annual outlook. Management now guides to 2026 earnings of $6.75 to $7.00 per share on revenue of $49 billion to $50 billion, yet consensus sits near $6.34 and $47.48 billion, essentially the top of the old range. Either analysts have been slow to update, or they doubt the second half can carry the load. A clean quarter that keeps the new range intact would force estimates higher.
Eliquis is the swing factor. Management lifted its full-year growth outlook for the blood thinner to roughly 20% to 25%, double the original 10% to 15% guide, citing the elimination of a pricing penalty in the second half. This is the first quarter where that benefit should show up in full, so Eliquis growth holding at or above the 21% pace seen in the second quarter would validate the thesis. Anything noticeably slower would raise questions about how much of the guidance raise depended on one mature product that still faces a $1.5 billion to $2 billion step down into 2027 as European exclusivity ends.
The longer-term story rests on the growth portfolio, which rose 14% last quarter and now accounts for about 60% of revenue. Investors should want to see that breadth sustained: Reblozyl accelerating, Camzyos continuing its roughly 59% growth clip, Breyanzi staying strongly positive even as growth moderates, and Cobenfi building beyond its modest $63 million base. The Opdivo trade-off also deserves scrutiny. Sales of the franchise fell 4% as patients moved to the subcutaneous Qvantig, which is running at an annualized rate above $1 billion. That conversion is healthy if combined Opdivo and Qvantig revenue holds steady, but troubling if the shift starts shrinking the overall franchise. Gross margin, which improved to 71.4% from 70.3%, is another check on whether the product mix is genuinely improving.
The pipeline adds texture. The Camzyos adolescent filing carried a September 30 decision date, so an update should be in hand. Meanwhile, the Milvexian atrial fibrillation readout and the Cobenfi ADEPT program have both slipped into early 2027. Management framed the delays as event-pace issues rather than efficacy concerns, and any further drift would test that patience.
Technically, shares at $61.68 sit above the 200-day moving average of $59.67 and roughly mid-range between the post-report low of $56.15 and high of $68.64, hardly the posture of a stock pricing in good news. The central question is simple: can Bristol Myers show that Eliquis and its newer drugs are delivering enough to make the raised guidance look conservative? If so, the lagging stock and stale estimates leave room for a rerating. If not, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 2 hours | |
| 7 hours |
Healthcare Stocks Are Rallying, and Flashing a Warning for the Rest of the Market
BMY
The Wall Street Journal
|
| Oct-20 | |
| Oct-20 | |
| Oct-19 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 |
