D.R. Horton Must Show Margin Strength Can Offset A Shrinking Fiscal Year-End Top Line
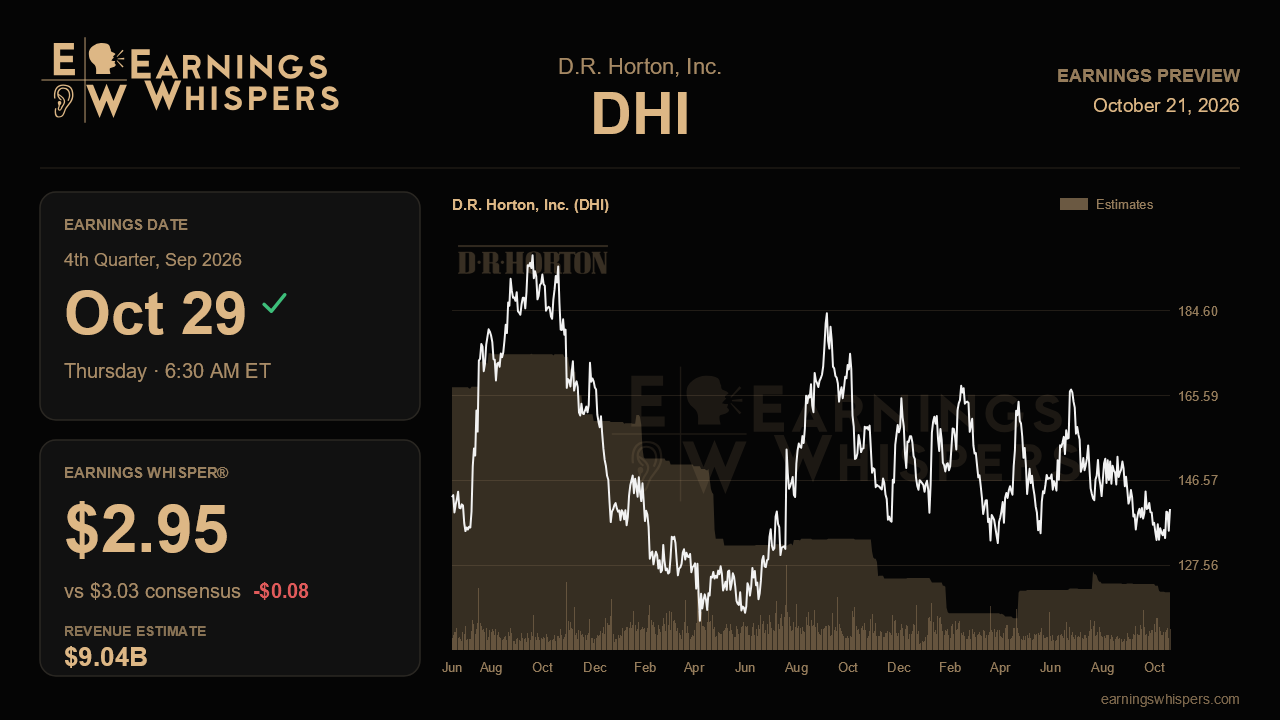
D.R. Horton enters its fiscal fourth-quarter report with a split personality. Its margins have been beating expectations, but its sales volume keeps disappointing. Last quarter the builder posted a home sales gross margin above the top of its own guidance, yet it cut its full-year revenue and closings outlook for the second straight time. The October 29 report, due before the open, will show which of those two trends deserves more weight heading into fiscal 2027.
The Street expects earnings of $3.03 per share on revenue of about $9.04 billion. That is essentially flat profit from the $3.04 earned a year ago, on sales down 6.6%. Holding earnings steady while revenue contracts depends on margins and the share count doing the work. The Earnings Whisper of $2.95 sits a few cents below consensus. The gap is modest, but it suggests the more skeptical part of the market sees the bar as slightly too high rather than too low.
Management's guidance frames the quarter. The company now expects fiscal 2026 revenue of $32.5 billion to $33.0 billion and closings of 83,800 to 84,300 homes. The original targets were $33.5 billion to $35 billion and as many as 88,000 homes. When the latest cut arrived, full-year consensus stood at $33.85 billion, well above the new range, so analysts have had to move down to management rather than the other way around. A fourth quarter that lands closings and revenue squarely inside the trimmed range would at least show the reset was sized correctly. Missing the low end after two reductions would raise harder questions about visibility.
The case for optimism rests on profitability. Gross margin rose from roughly 20% in the first quarter to 20.7% in the third, and management raised its fourth-quarter target to 20.5% to 21%. Early in the year it had pointed to something closer to 19.7%. Stick-and-brick costs fell 5% from a year earlier, cycle times shortened by about three weeks, and backlog pricing turned higher year over year for the first time in several quarters. A margin at or above the midpoint of that range would confirm that cost discipline is real, not a one-quarter gift. Investors should also listen for any update on the lumber and fuel inflation management flagged as a possible headwind next year.
The weaker side of the ledger is demand. Net orders were flat in the third quarter after rising 11% in the second, and the cancellation rate climbed to 20% from 16%. Management attributed that to softer traffic after April, and it guided starts lower for the fourth quarter. SG&A also deleveraged to 8.3% of revenue, and management said that won't reverse until growth returns. Fourth-quarter orders, cancellations and the year-end backlog are therefore more important than the headline EPS figure. Stabilizing orders and a cancellation rate easing back toward the mid-teens would validate the idea that the slowdown was a soft patch. Another decline would suggest the margin story is being bought with shrinking volume. Updates on the restructured rental business and any early benefit from the newly passed housing legislation could add color.
The market has already leaned skeptical. Shares are down 3.3% since the last report while the S&P 500 gained 3.1%, and the stock trades near $140, below its 200-day average of about $148. It sits in the lower half of a post-earnings range of $130 to $154, a range that is markedly lower than last quarter's. Sentiment has also soured noticeably, moving to clearly bearish from roughly neutral before the prior report.
Because this report closes the fiscal year, the decisive moment may be management's first framework for fiscal 2027. The company has reaffirmed $2.5 billion of buybacks and more than $3 billion of operating cash flow, which cushions the downside. The real test is whether D.R. Horton can guide to steady volume without sacrificing the margin gains it worked so hard to defend.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-19 | |
| Oct-06 | |
| Sep-29 | |
| Sep-22 | |
| Sep-21 | |
| Sep-21 | |
| Sep-21 | |
| Sep-14 | |
| Sep-10 | |
| Aug-27 | |
| Aug-26 | |
| Aug-19 | |
| Aug-14 | |
| Aug-14 |
