Hershey's Halloween Quarter Must Prove Salty Snack Freight Costs Won't Derail Its Margin Rebound
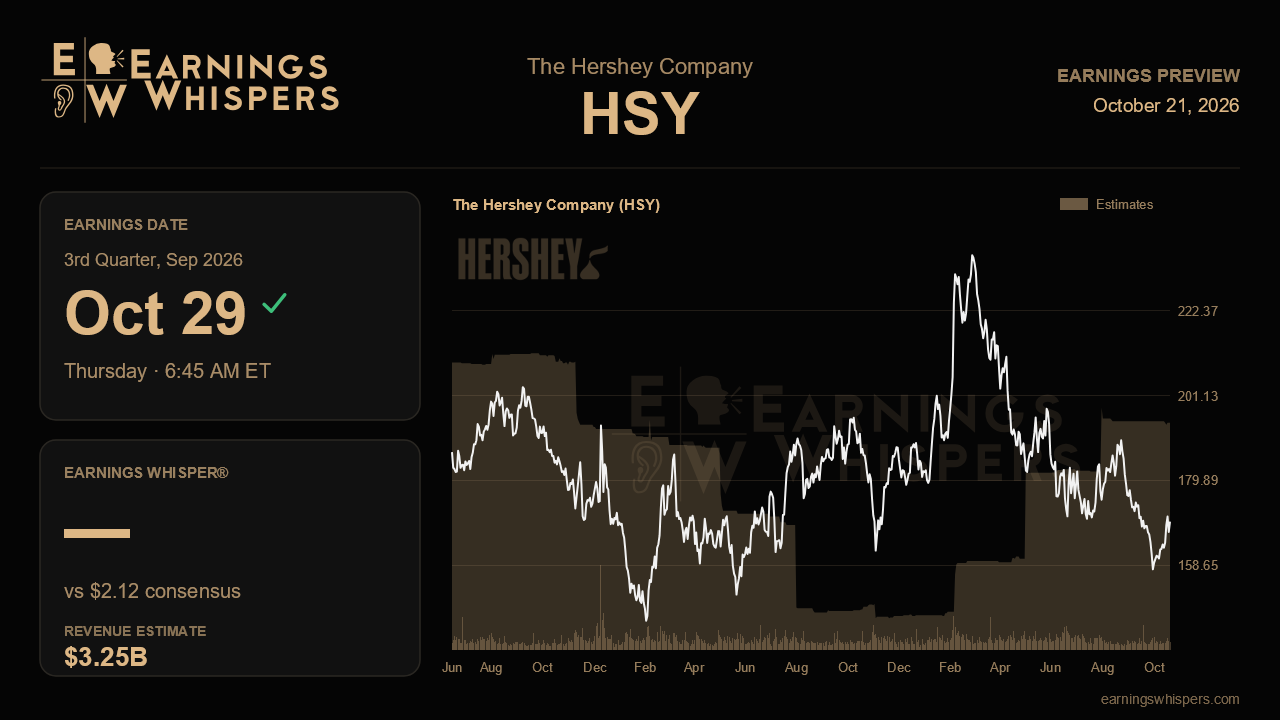
Hershey heads into its third-quarter report with a story that has improved on paper but deteriorated in the stock market. Last quarter, management nudged up full-year guidance, argued that real chocolate demand was running well ahead of what scanner data showed, and said it now has good visibility into cocoa deflation next year even if futures stay where they are. Since then the shares have fallen 7% while the S&P 500 gained 4.5%, a gap of more than 11 percentage points. The Halloween quarter now has to show whether the market was right to look past the upbeat commentary or whether it has priced in too much worry.
Wall Street expects earnings of $2.12 a share on revenue of $3.25 billion. That works out to profit growth of roughly 63% on sales growth of just over 2%, which says nearly everything about where Hershey is in its cycle. The top line is growing modestly. The earnings recovery comes almost entirely from margins rebuilding after last year's cocoa shock pushed year-ago profit down to $1.30 a share. Full-year guidance calls for $8.36 to $8.52 a share on revenue of $12.22 billion to $12.28 billion, and the consensus of $8.42 sits comfortably inside that range, slightly above the midpoint. Management lifted the bottom of its earnings range rather than the top, so the Street is not asking for heroics. A clean quarter that keeps the year on track should be enough.
The biggest swing factor is gross margin. In the spring, management talked about full-year expansion of about 400 basis points and hinted the back half could top 500. By the summer call that had slipped to just under 400, mostly because of freight and logistics problems in the salty snacks business, where DOTS pretzels have been squeezed by limited throughput and reliance on costly spot shipping. Management said real capacity relief will not arrive until 2027. That makes the salty segment's operating margin a key detail in this report. If freight costs have stabilized, the trim to margin guidance looks like a one-time adjustment. If they have widened, it raises the question of how much more of the cocoa benefit will leak away before it reaches shareholders.
On the revenue side, the quarter carries some noise. Management said about a point of third-quarter merchandising shifted into the second quarter, and it also flagged tougher comparisons as the business laps the successful Reese's Oreo launch, warning that some periods of everyday confection sales could turn negative. Against that, Halloween orders were already shipping with good visibility, and the company described its July Fourth s'mores execution as exceptional. A seasonal sell-through that holds up, together with price elasticity staying at or better than the planning range of roughly -0.8 to -1.0, would support management's view that demand is sturdier than the scanner data implies. International deserves a look too, since management planned extra optimization costs there in the back half on top of delayed cocoa savings.
Sentiment has soured noticeably. Bearish readings deepened to about 40% from 24% before the last report, and the stock sits near $170, well below its 200-day moving average of roughly $190. It trades in the lower part of its post-earnings range of $156 to $190, a range that has shifted down from the prior quarter's $168 to $200. Expectations for the stock, if not for the numbers, look subdued.
That sets up a fairly clear test. Investors are unlikely to get a big raise, so what matters is whether Hershey can show that the margin recovery is intact despite the salty snack supply chain, and whether management sounds as confident about 2027 cocoa deflation and its 2% to 4% North America confection framework as it did in the summer. If both hold, the gap between the improving fundamentals and a punished stock becomes hard to justify. If the salty segment's costs keep eating into margins, the summer's optimism will look premature.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-16 | |
| Oct-12 | |
| Oct-12 | |
| Oct-09 | |
| Oct-08 | |
| Oct-06 | |
| Oct-06 | |
| Oct-01 | |
| Oct-01 | |
| Oct-01 | |
| Sep-30 | |
| Sep-29 | |
| Sep-27 | |
| Sep-26 |
