Insmed Needs Brinsupri To Prove Its Organic Ramp After A 25% Post-Raise Slide
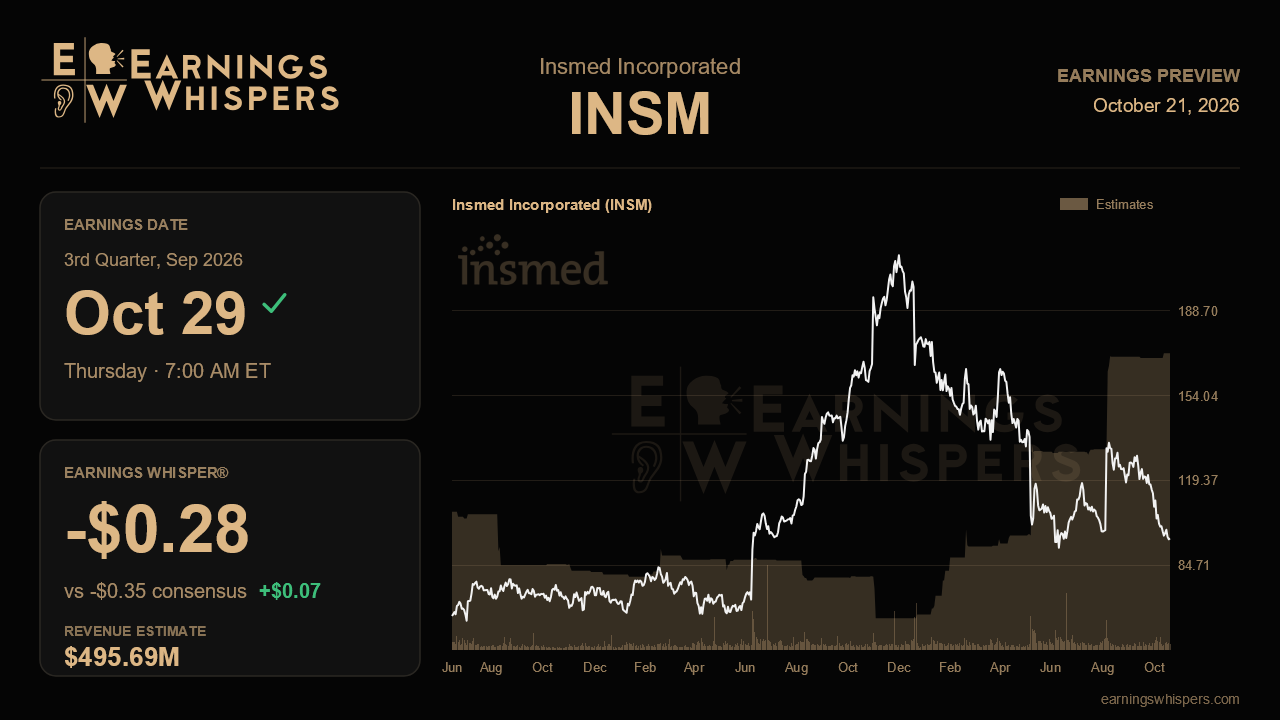
Three months ago Insmed delivered the most confident quarter in its recent history, raising Brinsupri guidance, nearly doubling portfolio peak-sales targets and declaring that demand for its new bronchiectasis drug was now fully organic. The market's response since then has been brutal. Shares have fallen about 25% while the S&P 500 has been roughly flat, leaving the stock near $96, just above its post-earnings low of $94.38 and far below its 200-day moving average around $128.50. That disconnect frames the third-quarter report, due before the open on October 29: either the operating story is intact and the selloff overshot, or investors are sensing a ramp that is harder to sustain than management suggested.
Wall Street expects revenue of about $495.7 million, up roughly 248% from $142.3 million a year ago and about 16% above last quarter's $425.5 million. The consensus loss is $0.35 per share, an 80% improvement from the $1.75 loss a year earlier. The whisper number sits at a narrower loss of $0.28, so the informal bar is somewhat higher than the published one, implying traders expect continued cost discipline and gross-margin strength to show up below the revenue line.
The revenue math runs through Brinsupri. Management guided Arikayce to $450 million to $470 million for the year, or roughly $115 million a quarter, which implies the Street is looking for Brinsupri somewhere near $380 million. That would be growth of about 23% from the second quarter's $309.2 million, a clear slowdown from the 49% and 44% sequential gains of the prior two quarters. A slower pace is not a warning sign by itself. With first-half Brinsupri sales of roughly $520 million, hitting the raised $1.25 billion to $1.4 billion full-year range requires about $365 million to $440 million per quarter in the back half, so consensus sits in the lower half of what guidance implies. A print comfortably above $400 million would suggest the range's upper end is in play.
The more important test is the quality of that growth. Management said the backlog of patients waiting for the drug has been exhausted and guided new starts flat at about 7,000 per quarter. That means sequential growth now depends on patients staying on therapy and refilling, and on prescribers deepening their use. The metrics that would validate the narrative are new starts holding near 7,000, cumulative prescribers continuing to climb from above 6,300, and the share of writers with five or more patients rising from about 30%. Gross-to-net discounts holding in the mid-to-high 20s and product costs staying near 16% of revenue would support the whisper's tighter loss. Weak persistence or a slip in starts would challenge the thesis far more than any headline revenue miss.
Arikayce is the secondary swing factor. Growth slowed to 8% year over year last quarter, and further softening would raise questions about the reiterated guidance. Beyond the numbers, updates on the EraCase filing for newly diagnosed MAC patients, the 2H26 Japan decision for Brinsupri, the still unresolved Japan pricing and the more cautious European outlook will help determine whether the enlarged peak-sales targets look credible.
Sentiment has improved to 26.6% bullish from 16.2% before the last report, so optimism has grown even as the stock has slumped. That combination suggests the shares are not priced for perfection. The central question is simple: can Brinsupri keep compounding once launch backlog demand is gone? Evidence that refills and prescriber depth are carrying the ramp would reinforce management's upgraded story, while signs of plateauing would explain why the market has refused to believe it.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-20 | |
| Oct-19 | |
| Oct-15 | |
| Oct-14 | |
| Oct-07 | |
| Oct-05 | |
| Oct-05 | |
| Sep-21 | |
| Sep-16 | |
| Sep-04 | |
| Sep-03 | |
| Aug-26 | |
| Aug-24 | |
| Aug-18 |
