Mastercard Tests A Breakout As Cross-Border Recovery Faces Its Proof Quarter
Three months ago, Mastercard turned what management had framed as a trough quarter into a quiet upside surprise. Cross-border travel improved faster than feared as Middle East disruption eased, U.S. volumes outside the Capital One migration sped up, and the company said full-year revenue should land higher within its range. When Mastercard reports third-quarter results before the open on October 29, the question is whether that recovery carried through the second half. The stock now trades just below its post-earnings high, so investors have already priced in much of the improvement.
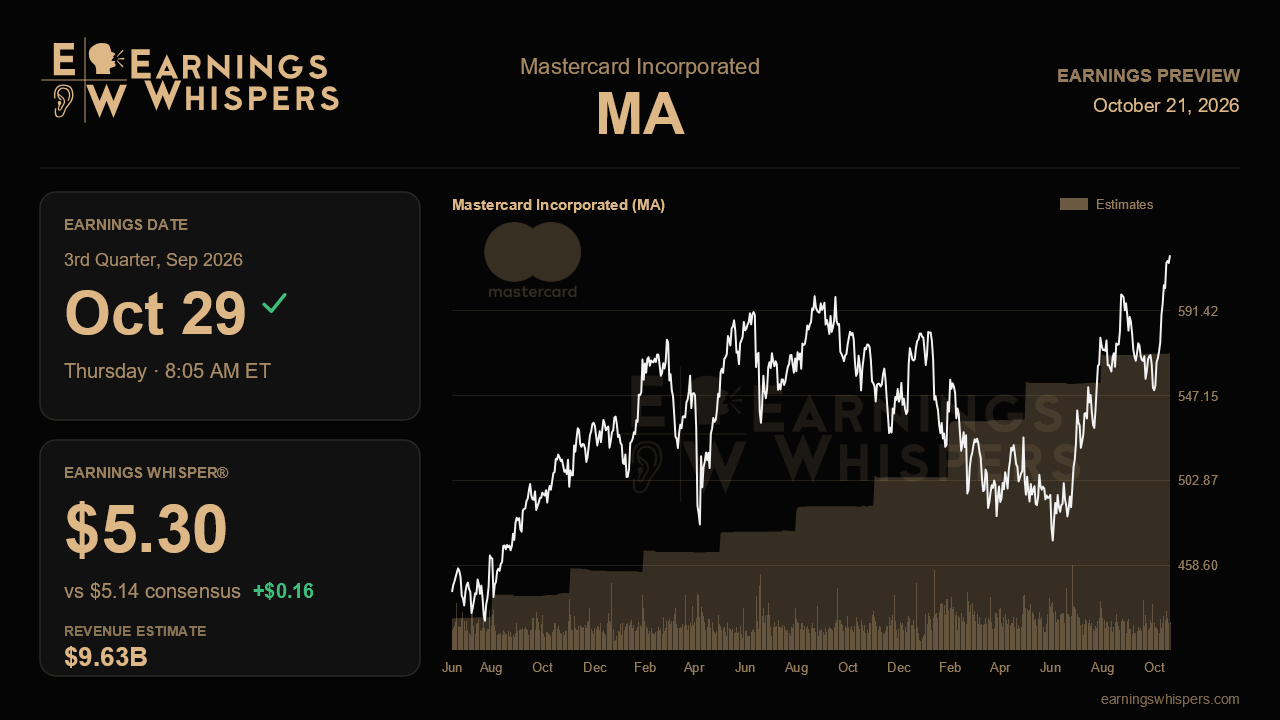
The Street expects earnings of $5.14 a share, up about 17.4% from $4.38 a year earlier, on revenue of roughly $9.63 billion, a 12% gain. The whisper number of $5.30 sits about 3% above consensus. For a company with Mastercard's steady record, that suggests the real bar is a clean beat, not a match. Revenue growth of 12% would equal the pace of the past two quarters. That is respectable, but it would not mark an acceleration. Matching it would mean absorbing the roughly half-point currency headwind management built into its outlook. It would also mean lapping a year-ago quarter that grew 15% partly on favorable currency swings. Holding 12% against those obstacles would show real strength underneath, while slipping toward 11% would hint that the second-quarter momentum was partly borrowed.
Cross-border volume is the most important line in the release. Management assumed a gradual second-half recovery in travel, and second-quarter cross-border volume held at 12%. Card-not-present spending outside travel ran near 20%, but some of that came from improved dollar availability in Venezuela, which may not last. A healthy report would show travel volumes improving sequentially and overall cross-border growth holding steady even as that Venezuela boost fades. Signs that travel stalled would undercut the main reason for raising the full-year outlook.
U.S. trends offer a second test. Switched volume excluding Capital One rose to 10% last quarter, helped by fuel prices and solid consumer and business spending. With the Capital One debit migration complete and its credit terms renegotiated, that relationship remains a revenue drag into next year. Underlying U.S. growth therefore needs to stay firm to offset it. Europe is also a watch point, since growth there is slowing as gains from earlier bank portfolio wins fade. Value-added services, up 18% in each of the past two quarters, should keep providing stability. Any slowdown there would stand out. Below the operating line, other expense should rise to about $125 million as interest on June's bond issue kicks in, a modest headwind already built into the outlook.
This quarter also gives the first look at catalysts management promoted heavily last time. These include the BVNK stablecoin acquisition, which was expected to close in the quarter, and Agent Pay for Machines, which launched with more than 30 partners. Investors should not expect meaningful revenue yet. They should look for confirmation that BVNK closed on schedule, early partner traction, and any change to the expense outlook from integration costs. This is also the first report shaped by the transition from departing CFO Sachin Mehra to Ling Hai, so how full-year guidance is framed will carry extra weight.
Sentiment has swung from 27.1% bearish before the last report to slightly bullish now. The shares have risen 7.5% since then, beating the S&P 500 by three points and sitting about 16% above their 200-day moving average. That combination raises the bar. The central issue is whether cross-border growth can keep Mastercard at 12% revenue growth despite currency and Capital One headwinds. If it can, a narrowing of the full-year range toward the upper end would support a breakout. If not, the stock's recent run leaves little room for disappointment.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 |
