Cheniere Faces A High Bar After Two Straight Raises As Hormuz Keeps LNG Tight
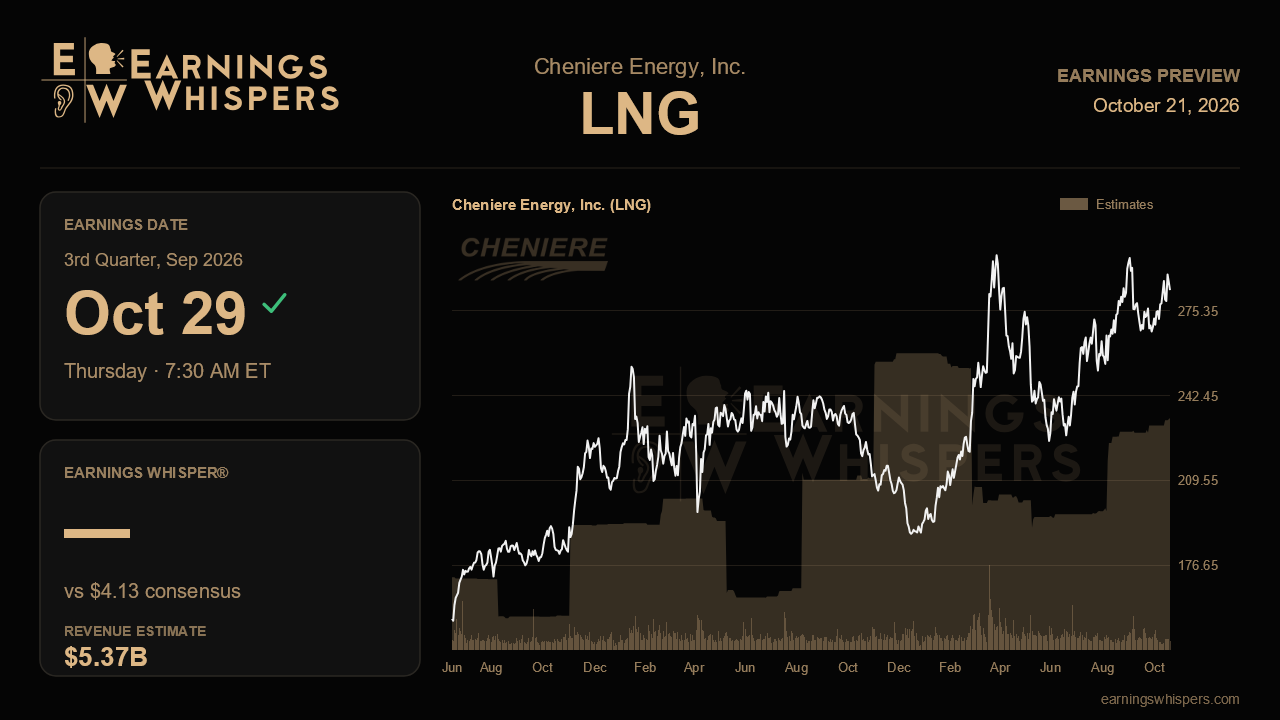
Cheniere Energy has turned guidance raises into something of a habit this year, and that is exactly what makes its third-quarter report on October 29 interesting. Full-year 2026 adjusted EBITDA guidance has climbed from roughly $6.6 billion to $7.0 billion when first introduced to $7.9 billion to $8.4 billion today. The latest increase came with a low end that sits above the prior high end. With a disrupted global LNG market still handing the company unusually rich spot margins, the question is not whether Cheniere is executing. It is whether there is room left for a third consecutive lift, and how much of that the market already assumes.
The Street is looking for earnings of $4.13 per share on revenue of about $5.37 billion. That implies a 20.9% jump in sales from a year ago alongside a 13.1% decline in per-share earnings. The split looks odd, but Cheniere's reported earnings have long been distorted by mark-to-market swings on long-term gas supply contracts. The first quarter's roughly $3.5 billion GAAP loss was driven by exactly those non-cash derivative charges. Management has since elected normal purchase, normal sale accounting on about three-quarters of those volumes, a change it says would have cut the number of loss-making quarters since 2021 from six to two. This should be one of the first cleaner quarters under that framework. Year-over-year EPS comparisons deserve some skepticism, while EBITDA and distributable cash flow deserve more weight. Sequentially, consensus calls for a meaningful step up from the $3.02 earned last quarter even as revenue eases from $5.73 billion.
The operational case for another raise rests on a few measurable items. Management tightened its production forecast to 53 to 54 million tonnes. Roughly two-thirds of that improvement came from reliability and debottlenecking rather than new capacity alone. Holding or nudging that range higher would show the gains are durable rather than a lucky stretch. Corpus Christi Stage 3 was more than 98% complete, with Train 7 commissioning ahead of its 2027 guaranteed date. Confirmation that Train 7 is contributing would support the volume story. Margins are the bigger swing factor. Cheniere was capturing $10 to $13 per MMBtu on spot cargoes against a long-run planning assumption of $2.50 to $3. Middle East supply losses and a European storage deficit that management doubted could even reach 70% before winter both argue those prices held. Any sign that spot margins compressed, or that China's limited flexibility softened global demand, would challenge the narrative.
Growth visibility matters too. Last quarter's signing of a roughly $4.7 billion lump-sum contract with Bechtel for Sabine Pass Phase 1, along with launching its financing, pointed to a final investment decision in early 2027 for more than 6 million tonnes of added capacity. Progress on financing and on contracting will be telling. Management acknowledged it can comfortably place mid-single-digit volumes at premium pricing but not 20 million tonnes, given how much uncontracted capacity the industry has sanctioned. New long-term agreements would ease that concern, as would continued buybacks under the expanded authorization of more than $10 billion through 2030.
Sentiment has cooled noticeably, slipping from solidly bullish ahead of last quarter to slightly bearish now, even though the shares have gained 5.9% since the last report while the S&P 500 was flat. At $283.35, the stock sits well above its 200-day average and above last quarter's high. It still trades about 5% below its post-earnings peak of $299.18, so this is not a breakout setup.
Ultimately, the report hinges on whether Cheniere's windfall from a tight market is translating into lasting earnings power. Reaffirming the raised range would be respectable. Moving it up again, while showing that reliability gains and Sabine expansion are on track, would confirm that this year's momentum is structural rather than merely circumstantial.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 8 hours | |
| Oct-05 | |
| Oct-01 | |
| Sep-29 | |
| Sep-24 | |
| Sep-10 | |
| Sep-08 | |
| Sep-04 | |
| Sep-03 | |
| Sep-03 | |
| Sep-02 | |
| Sep-01 | |
| Aug-31 | |
| Aug-31 | |
| Aug-12 |
