Blue Owl Must Prove Its Private-Credit Turn Is Real As Wealth Flows Face Test
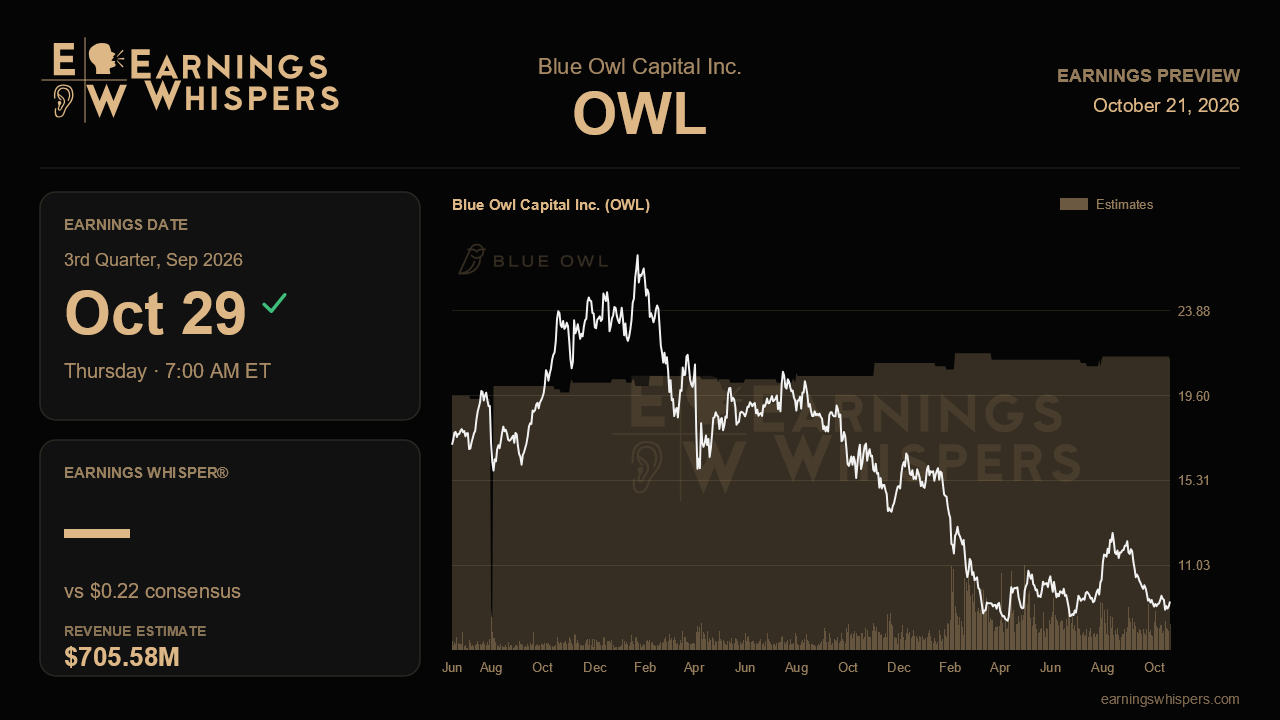
Blue Owl Capital spent its last earnings call arguing that the worst of the private-credit storm had passed. Wealth inflows had bottomed, the fee-related earnings margin target was hit ahead of schedule, and management again said it could beat Street numbers for the year. The stock has not bought the story. Shares have fallen 4.2% since that report while the S&P 500 gained 4.5%, leaving the third-quarter release as a straightforward test of whether the inflection management described is showing up in the numbers.
The bar itself is not demanding. Analysts expect earnings of $0.22 a share, matching both the prior quarter and the year-ago period, on revenue of about $705.6 million. That revenue figure would be down 3.1% from a year earlier and well below the $753.1 million reported last quarter. The sequential drop is the interesting wrinkle, because management explicitly said management fee growth should build in the third and fourth quarters. A report that shows rising fees and revenue comfortably above consensus would validate that claim. A quarter that merely lands near a contracting forecast would suggest the recovery is slower than the company implied, even if per-share earnings hold steady.
The wealth channel is the swing factor. Last quarter management called a trough in evergreen inflows at the May 1 close and reported that the July 1 close came in more than 50% higher. Non-traded BDC redemption requests eased modestly, and 90% of investors in one flagship vehicle asked to redeem nothing for a second straight quarter. The next step is evidence that this was a trend rather than a single good close: continued improvement in fundraising, further moderation in redemptions, and progress on the 21 additional wealth platforms slated for launch this year. Management was careful to say it did not expect a V-shaped rebound, so steady improvement would be enough. A relapse in redemptions would be the clearest challenge to the narrative.
Real assets carried the second quarter and needs to keep doing so. That segment grew AUM 25% and revenue 27% from a year earlier and now represents roughly 30% of the firm. The latest net lease vintage closed above its hard cap, and new data center credit and real estate credit vehicles had raised more than $1 billion toward a $1.5 billion goal. Updates on those first vintages, and on timing for the first close of the next digital infrastructure flagship, matter because that fund charges fees on committed capital and could lift revenue quickly. Investors should also track the $31 billion of AUM not yet paying fees, which management pegged at about $380 million of future management fees. Conversion of that backlog is what turns fundraising headlines into earnings.
The weaker side of the ledger has not gone away. Direct lending, once about half the business and now roughly 35%, was running near zero net deployment against a sluggish sponsor M&A environment. Growth in distributable and fee-related earnings slowed to 9% last quarter from double digits, and software exposure remains a sentiment overhang given drifting loan-to-value ratios and an unusually low loss rate that could normalize. Any detail on the possible traditional direct lending drawdown fund would show whether management can revive that engine.
Sentiment is still bearish but less so, improving from a reading of minus 0.24 before last quarter to minus 0.18 now. The stock, at $9.20, sits below its 200-day moving average of $10.58 and close to the bottom of its post-earnings range between $8.64 and $12.77. That positioning means a clean quarter could be rewarded, but the burden of proof sits with the company. The central question is whether management fees actually turned higher in the quarter, as promised. If they did, the improving story remains intact. If not, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 7 hours | |
| Oct-16 | |
| Oct-15 | |
| Oct-08 | |
| Oct-07 | |
| Oct-07 | |
| Oct-02 | |
| Oct-02 | |
| Oct-02 | |
| Oct-01 | |
| Oct-01 | |
| Sep-30 | |
| Sep-29 | |
| Sep-25 | |
| Sep-25 |
