Shell Faces A High Whisper Bar As ARC Closing And Softer Chemicals Test Its Five-Year Peak
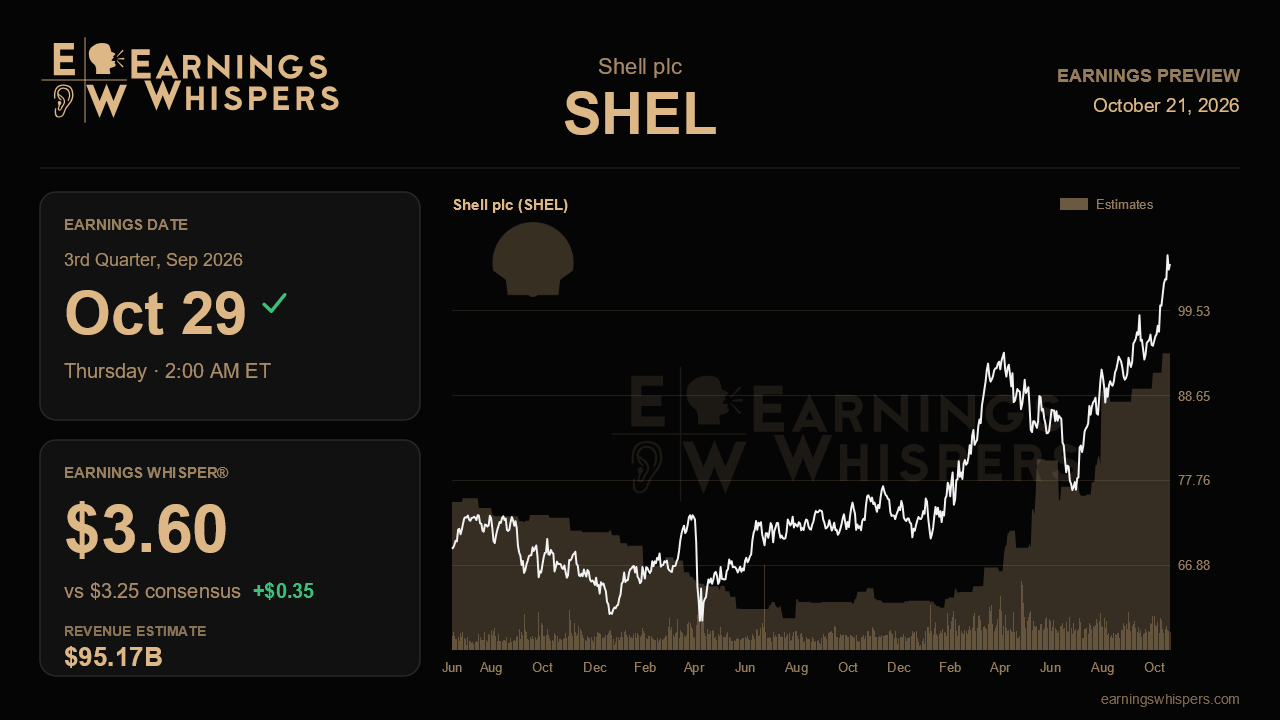
Shell heads into its third-quarter report coming off its best quarter in more than five years, and the market has treated that performance as a floor rather than a peak. The stock has climbed about 17% since the last release, nearly 13 percentage points ahead of the S&P 500. That leaves the October 29 report, due before the opening bell, with an unusual job: proving that a quarter powered by record refining runs and a surprise chemicals turnaround was the start of a durable earnings level, not a high-water mark.
The formal expectations bar is actually lower than last quarter. Consensus calls for EPS of $3.25, below the $3.52 Shell delivered in the second quarter, on revenue of roughly $95.2 billion, slightly under the prior period's $96.4 billion. Against last year's weak base, the comparison is still dramatic: EPS would rise nearly 75% and revenue about 35%. The more telling number is the Earnings Whisper of $3.60, which sits comfortably above consensus and even above last quarter's result. In other words, the published estimate implies a modest sequential step down, while the informal expectation implies Shell can hold or improve on a quarter management itself described as exceptional.
That tension matters because management's own outlook pointed to some cooling. On the last call, executives flagged chemical spreads beginning to soften, a continuing lubricants headwind from the loss of Pearl GTL base-stock supply, and capex inflation running around 5% to 6% alongside tight deepwater rig markets. Chemicals is the swing factor to watch. After quarters of depressed margins, the segment turned free-cash-flow positive in the second quarter, and that inflection was a large part of the improving narrative. If chemicals slips back toward breakeven, it would suggest the turnaround was cyclical luck rather than self-help. Refining, which ran at a record 102% utilization, is likely to normalize somewhat, so evidence that margins held up even as utilization eased would support the bull case.
The Middle East remains the other key variable. The Strait of Hormuz disruption removed roughly 20 to 25 million tonnes per year of Qatari LNG and Pearl volumes, and the Pearl Train 2 repair has slipped to the end of the first quarter of 2027. Any further delay, or signs the outage is bleeding more into trading and integrated gas results, would challenge the idea that the rest of the portfolio can keep offsetting it. On the positive side, LNG Canada running at full capacity should provide a full quarter of contribution, and an update on the Phase 2 investment decision targeted before year-end would reinforce Shell's long-term LNG pitch.
Strategically, this report should also clarify the ARC Resources deal, which was expected to close in the third quarter pending Investment Canada Act approval. Confirmation of closing, early integration details and a timeline for the roughly $1.5 billion in annual free cash flow it is supposed to add are important, since the deal was largely funded with stock and management has acknowledged it must prove mid-teens returns. Capital returns are the other tell. Cash flow from operations topped $21 billion last quarter, and whether Shell holds its $3 billion buyback pace, lifts it, or stays within its 40% to 50% distribution framework while digesting ARC will signal how confident it really is.
Sentiment has drifted more bearish than it was ahead of the last report, even as the stock trades well above its 200-day moving average of about $87 and within roughly 1% of its post-earnings high near $106.68, effectively testing a breakout. That combination suggests a crowd that has bought the story but worries about holding it. The central question is whether Shell's cost cuts, LNG growth and chemicals recovery can sustain second-quarter earnings power through softer spreads and lost Middle East volumes. A result near the whisper with a clean ARC update keeps the narrative intact; a slide toward consensus with chemicals fading would make the recent rally look ahead of the fundamentals.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 1 hour | |
| 8 hours | |
| 11 hours | |
| 14 hours | |
| Oct-20 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 |
Britain govt held talks With UBS over potential London move report
SHEL
Private Banker International
|
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 |
