TPG Must Show Fee Engine Can Absorb A Guided Capital Markets Dip In Q3
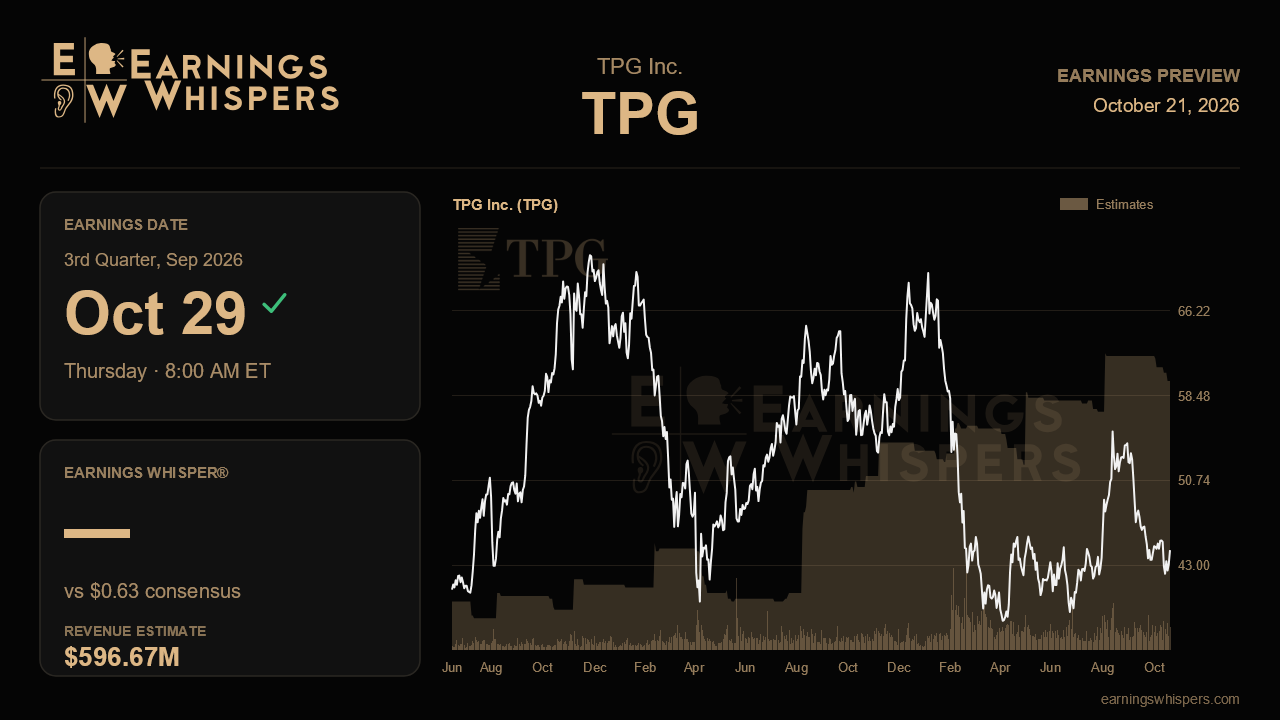
TPG heads into its third-quarter report with a split personality. The core earnings machine, built on management fees and fee-related earnings, came off its strongest quarter in years, yet the stock has slipped since that report and sentiment has soured. Management also warned ahead of time that one lever, transaction and monitoring fees, would weaken this quarter after deal closings were pulled forward into the second quarter. The question for the October 29 pre-market release is whether investors are pricing in a slowdown that is really just timing, or something more lasting.
Wall Street expects earnings of $0.63 a share, down from $0.69 last quarter but up about 19% from $0.53 a year ago. That combination fits the story management told: a sequential dip driven by capital markets fees, set against a higher base of recurring fees. The revenue consensus of $596.7 million implies a 51% drop from the year-ago $1.22 billion. TPG's reported revenue swings heavily with performance allocations and other volatile items, so the revenue figure says less about the business than it seems. Fee-related revenue, which reached $628 million last quarter, is the better gauge of underlying health.
Margins will tell investors the most. TPG posted a 50% fee-related earnings margin in the second quarter, up from 44.3% in the first, but kept its full-year target at 47% rather than raising it. Since the first half averaged roughly that level, management has effectively signaled a second half near the guide, not a continued climb. A margin that holds in the high 40s despite lighter transaction fees would suggest the step-up in management fees, which rose 9% sequentially last quarter, is doing the heavy lifting. A slide well below that would raise doubts about how much of the second quarter's strength came from one-time deal timing.
The growth engine also faces checks. Assets under management reached $327 billion, up 25% from a year earlier, and management reaffirmed its target of raising more than $50 billion in 2026, with over $26 billion already in hand by midyear. Third-quarter fundraising should show whether TPG is on pace to reach that target or will need a heavy fourth quarter. Newer initiatives deserve attention as well: the OpenAI deployment platform with more than $4 billion committed, the Jackson partnership that grew to $4.5 billion, and the Smith & Howard and Echo Realty acquisitions. Investors will want signs that these are turning into fee-paying capital. On the softer side, realized performance allocations fell to $35 million from $68 million as private equity exits slowed across the industry, and redemptions in the private wealth vehicles rose to 2.1% from 1.3%. Any further rise in wealth-channel outflows would challenge the retail growth story, while a recovery in exits would help carried interest, which grew 15% to $1.4 billion last quarter.
The market's mood has cooled. Sentiment has moved from mildly bullish before the last report to moderately bearish now, and the stock is down 5.6% since the last report while the S&P 500 gained 1.1%. At $44.38, shares sit below their 200-day moving average of $46.62 and in the lower part of a post-earnings range that ran from a $55.50 peak down to $41.24. The rally after the second-quarter results has fully unwound, which lowers the bar somewhat. The CFO handoff from Jack Weingart to Axel Andre adds some uncertainty to how the outlook is presented.
The narrative stays intact if TPG can show that the expected drop in transaction fees is a timing issue against rising management fees, keep margins near its 47% target, and stay on track toward $50 billion in fundraising. If the fee dip spreads further or wealth flows weaken more, the stock's recent slide will look justified rather than an opportunity.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 7 hours | |
| Oct-14 | |
| Oct-01 |
TPGs $10B Climate Fund Shows Investors Arent Giving Up on the Energy Transition
TPG
Benzinga Private Markets
|
| Sep-29 | |
| Sep-18 | |
| Sep-17 | |
| Sep-17 | |
| Sep-15 | |
| Sep-15 | |
| Sep-09 | |
| Sep-08 | |
| Sep-08 | |
| Sep-02 | |
| Aug-13 | |
| Aug-10 |
