Tenet Must Show Its Raised Outlook Can Withstand Deepening Exchange Erosion
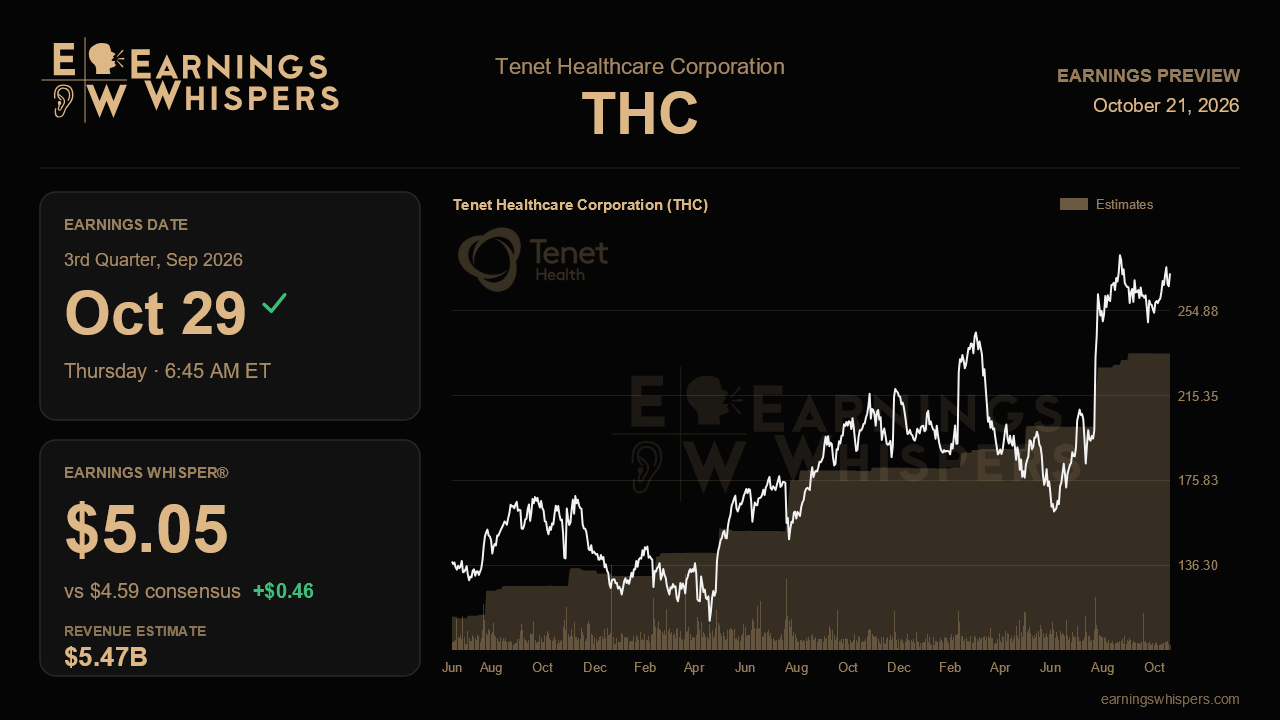
Tenet Healthcare enters its third-quarter report having done something it declined to do in the spring: raise its full-year outlook, and by a wide margin. The question now is whether that confidence was the start of a durable upswing or a high-water mark lifted by one-time Medicaid money and aggressive cost cutting. The report before the open on October 29 should go a long way toward answering it, particularly as the company's exposure to shrinking insurance-exchange enrollment keeps growing.
Wall Street expects earnings of $4.59 per share on revenue of $5.47 billion. That would be a 24.1% jump from last year's $3.70, on revenue growth of just 3.4%, a gap that tells the story of Tenet's model. Margin gains and a shrinking share count are doing most of the work, not the top line. The Earnings Whisper of $5.05 sits roughly 10% above consensus, a meaningful premium that suggests the market expects Tenet to clear published forecasts comfortably. A sequential decline from the second quarter's $6.12 and $5.63 billion should not alarm anyone, since that period benefited from $140 million in newly approved Florida supplemental Medicaid payments plus out-of-period amounts.
The guidance math makes the setup more interesting. Management now projects 2026 earnings of $20.30 to $21.69 per share, up from $16.38 to $18.68, on revenue of $21.9 billion to $22.5 billion. Full-year consensus of $17.50 sits well below the bottom of that new range, which implies either stale estimates or genuine skepticism about the second half. If it is the former, the whisper number is the more realistic bar. Underneath the per-share figures, Tenet lifted adjusted EBITDA guidance by $295 million to $4.83 billion to $5.03 billion, with nearly all of that increase coming from the hospital segment.
That hospital strength is what this quarter must confirm. Same-store adjusted admissions improved to 2.6% growth in the second quarter from 0.6% in the first and flat in the fourth, while revenue per adjusted admission swung to a 3.3% gain from a 1.5% decline. Sustaining both would validate the raise. The counterweight is the exchange business, where revenues fell 17% in the second quarter versus roughly 9% to 10% in the first, with lost volume converting nearly one-for-one into uninsured patients. Damage spread to Arizona and Michigan alongside Florida, South Carolina and Texas. Management built caution into the back half, assuming only about $60 million of fundamental outperformance versus roughly $100 million in the first half, largely from expense and AI-driven efficiencies. A further step down in exchange revenue, or softer inpatient elective surgery in those states, would test that cushion. At USPI, the ambulatory surgery arm, same-facility cases slipped 1.2% even as revenue rose 5% on a deliberate shift toward higher-acuity work like total joints. Steady pricing with stabilizing case counts would support that strategy, while another volume decline would invite harder questions.
Expectations have clearly warmed. Sentiment has flipped from 16.4% bearish ahead of the last report to 5.2% bullish, and the stock has gained 15.9% since then, outpacing the S&P 500 by nearly 12 points. At $272.32, shares sit about 25% above their 200-day moving average and a few percent below the post-earnings high of $283.05, with the entire recent range trading above last quarter's peak. Capital returns help explain the enthusiasm: $1.36 billion of buybacks year to date, a fresh $2 billion authorization and leverage down to 2.33 times EBITDA.
The verdict hinges on whether hospital volume and pricing gains can keep outrunning exchange erosion without leaning on another Medicaid windfall. If Tenet holds or nudges its raised outlook while exchange losses stabilize, the narrative stays intact. If the uninsured shift accelerates faster than cost savings can offset, the rally leaves little room for disappointment.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 6 hours | |
| Oct-20 | |
| Oct-20 | |
| Oct-17 | |
| Oct-16 | |
| Oct-16 |
Meta, Tesla Take Center Stage As Earnings Season Kicks Into High Gear. Everything You Need To Know.
THC
Investor's Business Daily
|
| Oct-15 |
Tenet Healthcare, IBD's Stock Of The Day, Rides Blue Wave Toward Buy Point
THC
Investor's Business Daily
|
| Oct-02 | |
| Oct-01 | |
| Sep-24 | |
| Sep-18 | |
| Sep-15 | |
| Sep-15 | |
| Sep-14 | |
| Sep-11 |
