Tradeweb Must Prove Its Swaps-Led Growth Can Reaccelerate As Stock Tests Its Highs
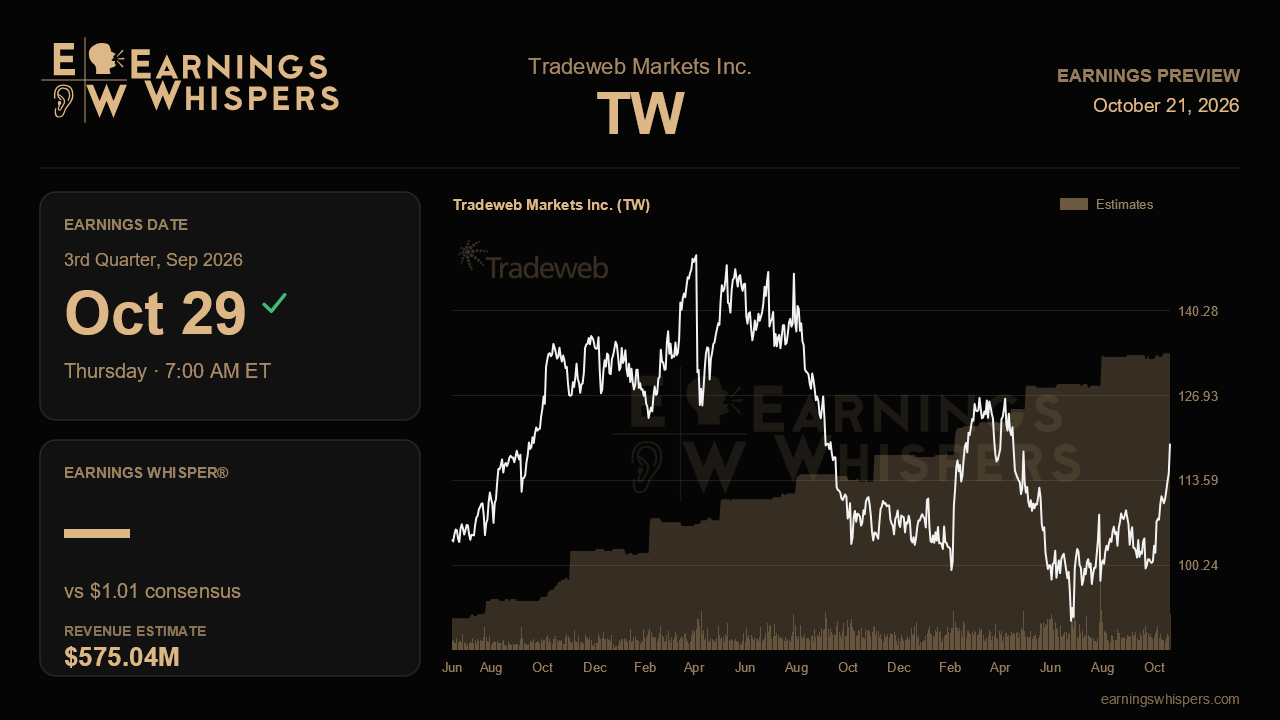
Tradeweb heads into its third-quarter report with the stock pressing against its highs and Wall Street betting that last quarter's slowdown was a calendar quirk rather than a trend. After revenue growth cooled to 9% in the second quarter against a punishing April 2025 comparison, analysts expect it to bounce back into the low teens. That puts the burden on the company to show its growth engine is still running at full speed.
Consensus calls for earnings of $1.01 per share on revenue of about $575 million, up roughly 16% and 13% from a year ago. Both figures would mark a step up from the $0.97 and $558.9 million posted last quarter. The revenue target lines up neatly with management's comment that July average daily revenue was tracking up by a low-teens percentage, so the Street is essentially extrapolating the early-quarter run rate across the full three months. Management did not issue revenue guidance, but it reaffirmed full-year expenses toward the top half of its $1.1 billion to $1.16 billion range while still promising margin expansion. That matters because earnings are expected to grow faster than revenue, which assumes some operating leverage even as technology and occupancy costs climb nearly 40% year over year. Last quarter's EBITDA margin improved by only about a quarter of a point, so any slippage in cost discipline could leave a revenue beat without a matching earnings beat.
The operating story rests most heavily on swaps. Core risk market share gains widened from 130 basis points a year earlier to a record 207 basis points last quarter, and total swaps share climbed to 24.1%. Another quarter of share gains near that level would confirm that electronification of the rates market is structural rather than cyclical. U.S. Treasuries offer a second test. Share finally broke out of its long plateau near 22% to reach 22.5%, and holding or extending that gain would suggest the improvement is durable. International revenue, which supplied about two-thirds of last quarter's growth, is a third line worth tracking.
Credit is where the narrative is most vulnerable. Management warned that investment-grade and high-yield share was tracking below June levels early in the quarter, even as block trading and request-for-quote volumes hit records. The timing is awkward, because ICE's pending acquisition of MarketAxess creates a larger, integrated competitor in exactly this market. Management framed that deal as validation of the credit opportunity, but softer share this quarter would invite questions. Investors should also look for further moderation in fee compression: cash credit fee per million fell about 11% last quarter, an improvement from mid-teens declines, while long-tenor swaps fees slid around 10% on mix. Persistent weakness in retail credit and wholesale Treasuries remains a drag, though a narrowing of the retail decline from 22% would help.
The market has already voted on the story. Shares are up about 19% since the last report, beating the S&P 500 by nearly 15 percentage points, and at roughly $119 they sit just beneath their post-earnings high and above the prior quarter's peak, comfortably clear of the 200-day moving average. Sentiment has improved from strongly bearish to modestly bearish, a sign skeptics are retreating but have not capitulated. The heavier buybacks management pursued during the earlier dislocation now look well timed, yet the rally means less margin for error.
Ultimately, this report hinges on whether reaccelerating revenue arrives alongside the promised margin expansion. Continued swaps and Treasury share gains, steady credit despite the competitive shake-up, and expenses that stay within plan would validate the broadening-growth thesis and could carry the stock through its highs. A credit share stumble or costs outrunning revenue would challenge it at an unforgiving moment.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 | |
| Oct-19 | |
| Oct-14 | |
| Oct-09 | |
| Oct-06 | |
| Oct-01 | |
| Sep-22 | |
| Sep-10 | |
| Sep-09 | |
| Sep-04 | |
| Sep-03 | |
| Aug-27 |
