SAP Beats And Nudges Cloud Outlook Higher, But Flattering Comparisons And A 49% Run-Up Raise The Bar
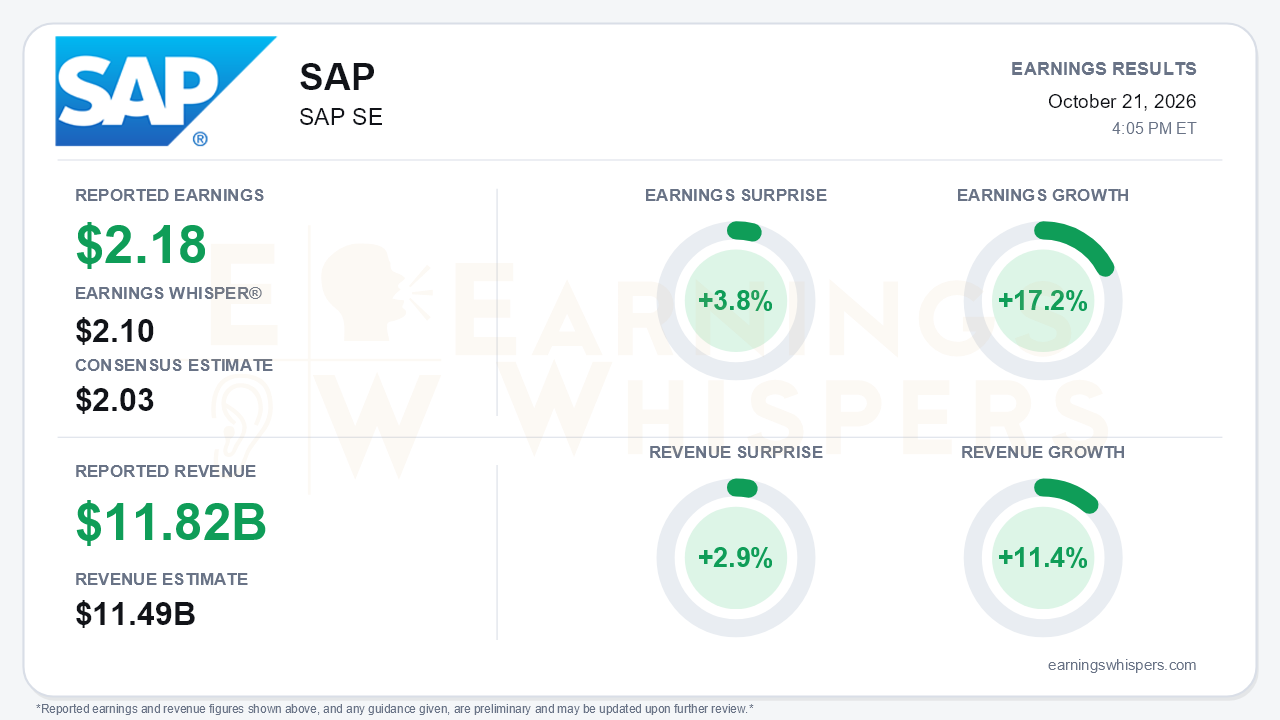
SAP delivered the record quarter its management had been promising and then some. The company reported earnings of $2.18 per share, beating the $2.03 consensus by 3.8% and clearing the $2.10 Earnings Whisper number. Revenue of $11.82 billion topped the $11.49 billion estimate by 2.9%. Earnings grew 17.2% year over year and revenue rose 11.4%. In euro terms, total revenue crossed €10 billion for the first time (€10.27 billion, up 12% at constant currencies), and non-IFRS operating profit topped €3 billion. Management moved its 2026 cloud revenue and cloud-and-software revenue outlook toward the upper end of the ranges. The central tension is that the headline acceleration is real but partly manufactured by easy comparisons and one-offs, and it arrives after a stock run that already priced in much of the good news.
The quality of the beat deserves scrutiny. Non-IFRS operating profit grew 18%, double the 9% pace of the second quarter. However, the year-ago quarter carried roughly €0.1 billion each from an adverse tax-litigation ruling and a workforce transformation charge, so a meaningful share of the profit acceleration reflects the comparison rather than the business. Operating margin still expanded 1.2 points to 29.5%, and cost discipline is evident. Cloud revenue grew 25% at constant currencies versus 24% in Q2. SAP acknowledged, though, that quarter-specific effects lifted the figure, mainly a multi-quarter catch-up from customers emerging from financial distress worth about a point. Strip that out and cloud growth was essentially flat sequentially. Free cash flow rose 36% year over year to €1.72 billion but fell sharply from €3.0 billion in Q2, with higher receivables and migration credits weighing.
Beneath the surface, the cloud franchise remains the engine. Current cloud backlog reached €24.1 billion, up 26% at constant currencies, matching Q2 and up from 25% earlier in the year. Management said it is slightly accelerating organically. The source material conflicts on Cloud ERP Suite growth. The release reports 29% (28% at constant currencies), while the call analysis cites 38% versus 27% in Q2. Investors should anchor on the released figure, which still represents solid, steady growth rather than a step change. The legacy decay is also intensifying. Support revenue fell 5%, licenses fell 9%, and services fell 4% (5% at constant currencies), a steeper decline than Q2's slight dip. Management expects further deliberate services declines in 2027. Cloud gross margin slipped to 74.3% from 74.6% in Q2 and 75.2% in Q1, pressured by hardware costs and AI investment.
The call preserved a credible growth story built around AI. Joule Work is now live with customers. Nine of the ten largest deals among the top 50 included AI or Business Data Cloud components. SAP raised its internal AI efficiency target to up to €3 billion over two years, from roughly a €2 billion run-rate by 2028, and plans to automate cloud delivery operations to cut contractors and support cloud margins. The Dremio and Reltio integrations and the planned TechWolf acquisition deepen the data and AI stack. Bears still have legitimate ammunition:
- **Unchanged guidance elsewhere:** Operating profit, free cash flow, and backlog guidance were only reaffirmed, and backlog growth is still expected to decelerate slightly, implying an exit near 23-24%.
- **Macro caution:** Management flagged oil near $110 and U.S. rates above 5% as risks to a fourth quarter that carries roughly half of annual bookings.
- **Tougher 2027 bar:** Management conceded that a stronger 2026 makes its promised 2027 revenue acceleration harder to deliver.
The market setup is more complicated than the surprise implies. Shares opened at $153.75 after the July report and sat at $228.98 ahead of this release, a 48.9% gain. That left the stock within 0.2% of its inter-earnings high and 19.2% above its 200-day moving average. Earnings Whispers investor sentiment improved substantially, from -0.35 to -0.04, but remained marginally negative even after that rally. Expectations have warmed considerably without turning outright bullish. The Earnings Whispers trend signals are mostly positive, with price, sequential growth, and AVWAP readings constructive while momentum is neutral.
The bottom line is that SAP delivered a clean beat, a modest raise, and evidence that its cloud backlog and AI strategy are holding up. Much of the quarter's profit acceleration came from soft comparisons and a one-time cloud catch-up, and guidance outside the top line was unchanged. With the stock pressed against its highs after a near-50% advance, the debate now shifts to fourth-quarter bookings under a tougher macro backdrop and SAP's ability to deliver the 2027 revenue acceleration it has promised.
Read our earnings preview for SAP SE: https://www.earningswhispers.com/article/SAP/20481
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-12 | |
| Oct-12 | |
| Oct-09 | |
| Oct-07 | |
| Oct-07 | |
| Oct-07 | |
| Oct-07 | |
| Oct-06 | |
| Oct-06 | |
| Oct-06 |
