Intel's Server Boom Faces A Supply Test As Stock Lags Its Own Turnaround
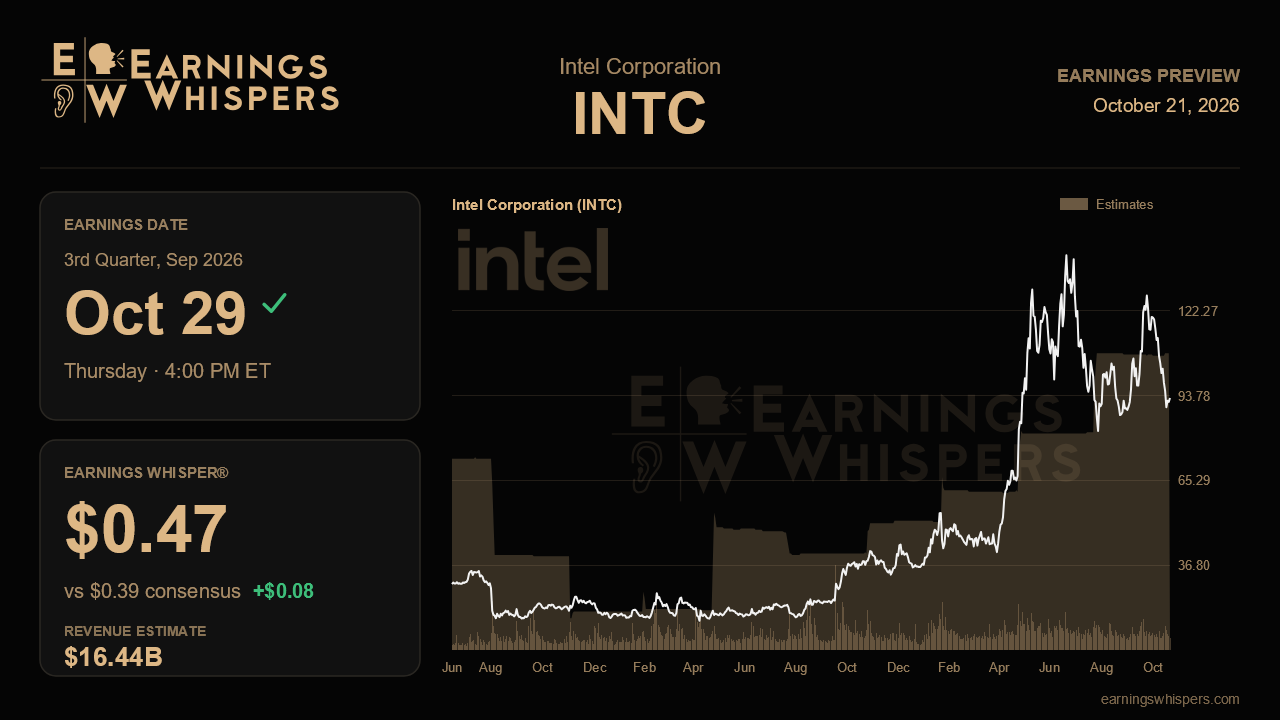
Intel heads into its third-quarter report with an awkward mismatch. Three months ago management delivered its most confident call in years, describing the strongest revenue growth in more than a decade and a half, lifting its capital spending plans and committing to high-volume production on its 14A process in 2028. Since then the stock has fallen 8.6% while the S&P 500 gained 4.1%. That leaves a market that seems to doubt whether the operating story can keep pace with the rhetoric. The report after the close on October 29 is the first real chance to settle that argument.
The Street is looking for non-GAAP earnings of $0.39 a share on revenue of $16.44 billion. That would be roughly 20% top-line growth from the $13.65 billion posted a year ago, and earnings more than triple the year-ago $0.11. Management guided to about $0.38 on revenue of $15.8 billion to $16.8 billion, so consensus sits a touch above the midpoint on both lines but comfortably inside the range. The more telling number is the whisper of $0.47, well above consensus. It signals that the investors most engaged with the name expect Intel to clear its own guidance by a wide margin again, a habit it has built over a string of consecutive beats. A result that merely matches the guide could therefore feel like a miss.
The data center business carries this narrative. Last quarter that segment grew 59% from a year earlier. Management said its server outlook had improved again, calling for strong double-digit industry unit growth extending into 2028. Custom ASIC work reached a roughly $2 billion run rate, with a path toward $4 billion. Validation this quarter means another sequential step up in data center revenue and evidence that new long-term customer agreements are turning into shipments. The catch is supply. Intel conceded that wafers, memory and substrates remain tight, that shipments are weighted toward the end of the third quarter and into the fourth, and that it will not fully catch up with demand by year end. If the backlog is real but parts arrive late, revenue could land near the middle of the range rather than the top, and fourth-quarter guidance becomes the more important signal.
Margins are the second test. Gross margin reached 41.8% last quarter, far above a guide that had called for a decline. The third quarter is guided to 42%. Holding that level would show that manufacturing gains are offsetting rising input costs. Those gains include 18A output running about 25% ahead of target and Panther Lake costs falling roughly in half this year. The input costs include substrates and memory. Continued narrowing of the foundry operating loss, which improved to about $2.1 billion last quarter, would strengthen the case that heavier capital spending is a bet on momentum rather than a leap of faith.
The weak spot is the PC business. Management already expects PC demand to run below seasonal norms in the second half and full-year units to fall by a low-double-digit percentage, as memory price inflation weighs on consumers. Client revenue was guided roughly flat, and further inventory write-downs would be an unwelcome repeat. A cleaner PC quarter would help, but a soft one is largely expected.
Sentiment has cooled, with bullish readings at 14.6% compared with 24.8% ahead of the last report. Shares at $91.69 sit above the 200-day average but much nearer the post-earnings low of $81.79 than the $127.44 high, after a sharp run-up and retreat. The central question is whether Intel can show that data center demand and manufacturing improvements are converting into revenue and margin fast enough to justify a capital spending ramp that is moving ahead of signed foundry customers. Strong server shipments and confident fourth-quarter guidance would keep the turnaround narrative intact. A supply-limited quarter could leave the stock's skeptics in charge a while longer.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 |
