Reddit's Bar Sits Above Its Own Guidance As US User Questions Linger
Reddit heads into its third-quarter report with an unusual combination: a money machine that keeps outrunning forecasts, and a user story that has started to wobble. Last quarter delivered an eighth straight period of revenue growth above 60%, yet it also produced the company's first notable sequential drop in US daily users and a forward outlook that implied a clear slowdown. The question on October 29 is whether monetization can keep carrying the story while the audience side gets harder to read.
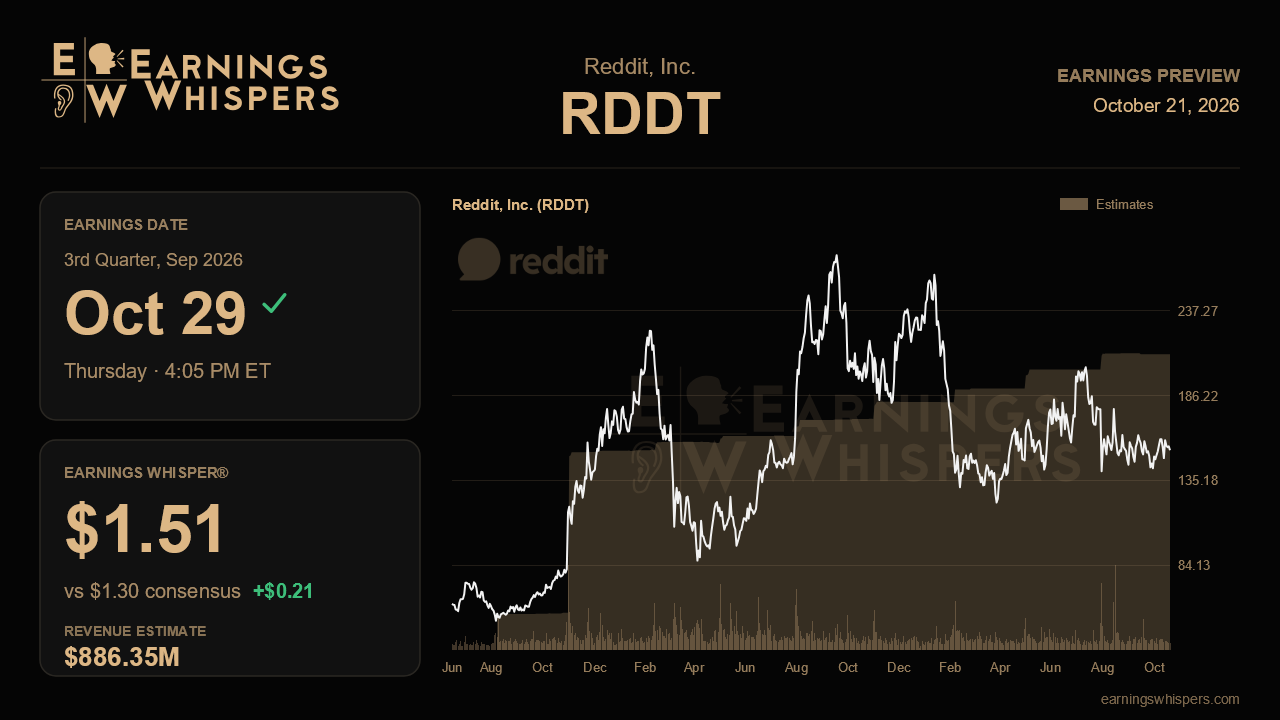
The Street has already decided Reddit will beat its own numbers. Management guided third-quarter revenue to $860 million to $870 million, implying roughly 48% growth at the midpoint. Consensus now sits at $886.4 million, about $16 million above the top of that range, which works out to expected growth of 51.5%. On earnings, analysts are looking for $1.30 per share, up 62.5% from $0.80 a year ago, while the whisper number of $1.51 sits well above consensus. That gap is not trivial. It suggests the informal bar is a clean beat on both lines, not a result that merely lands inside guidance. Given Reddit's habit of clearing its outlooks, that is a reasonable assumption, but it leaves less room for a result that is good rather than great.
The commercial engine gives the bulls plenty to point to. Average revenue per user climbed 36% to $6.18 last quarter, active advertisers grew about 70%, and Reddit Max, the automated campaign tool, saw its revenue jump 150% sequentially. Management also guided adjusted EBITDA margin to about 45% at the midpoint, up from 43%, and trimmed its stock compensation outlook. Validation this quarter would look like continued strength in advertiser counts, evidence that newer tools such as the Shopify integration, shopping listing ads and dual attribution for app install campaigns are adding to demand, and margins at or above that 45% target. Operating cash flow, which doubled last quarter and topped $1 billion on a trailing basis, is another proof point, especially now that buybacks have become meaningful after $235 million was repurchased in the second quarter.
The harder test is users. Search referrals turned choppy late last quarter, AI Overviews have yet to help traffic, machine-translated content that once drove international growth declined, and user acquisition spending produced mixed returns. Management argued that logged-out drive-by traffic matters less than direct and app users, and it pointed to a 50% improvement in new app user retention as early product progress. The complication is that Reddit has stopped reporting the logged-in and logged-out split, so investors will have less detail just as scrutiny rises. Another sequential US decline would make the user problem harder to dismiss, while stabilization would support management's claim that the core audience remains healthy. Any comment on data licensing renewals heading into early 2027 also carries weight.
Sentiment has cooled noticeably, with readings moving to 17.8% bearish from 5% bearish before the last report. The stock has done nothing special, rising 3.8% in line with the S&P 500 since the prior release. At $153.28, shares sit below the 200-day moving average of $164.42 and in the lower half of the post-earnings range of $135.22 to $184.28, well beneath the prior quarter's $208 peak.
That setup frames the report neatly. Strong numbers are expected, so a beat alone may not move the stock. What would change the conversation is a fourth-quarter outlook that halts the deceleration alongside user metrics that show the US softness was a blip. If monetization keeps compounding but traffic keeps slipping, the market will likely keep discounting how long pricing gains can outrun the audience.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 | |
| Oct-12 | |
| Oct-12 | |
| Oct-09 | |
| Oct-09 | |
| Oct-09 | |
| Oct-08 | |
| Oct-06 | |
| Oct-06 | |
| Oct-05 | |
| Sep-30 |
