Stryker's Second-Half Ramp Faces Its First Real Test As Vascular Supply Fix Comes Due
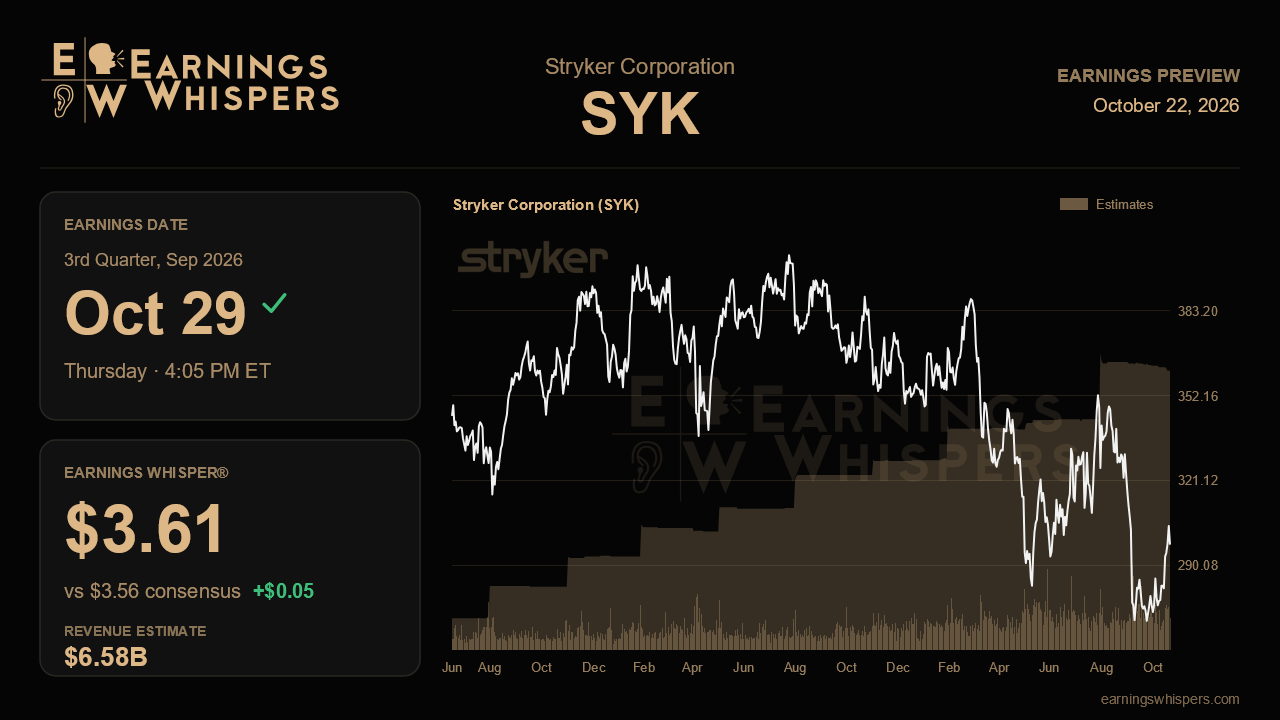
Three months ago Stryker looked like a company that had put its worst quarter behind it. Organic growth snapped back to 9% after a cyber incident crushed first-quarter results, margins rebounded, and management resumed share buybacks for the first time in roughly six years. The stock has since fallen about 10% while the S&P 500 gained nearly 4%, which means the third-quarter report, due after the close on October 29, arrives with the market openly doubting the recovery story management told in July.
The Street expects earnings of $3.56 per share on revenue of $6.58 billion, implying growth of 11.6% and 8.6%, respectively, from a year ago. Those are healthy figures, but notably they sit below the second quarter's $3.69 in EPS on essentially flat sequential revenue. The Earnings Whisper of $3.61 is a nickel above consensus, a modest signal that more engaged investors expect a small beat rather than a stumble. On the full year, management reaffirmed its $14.95 to $15.10 EPS range, and consensus of $14.99 sits close to the bottom of it. That positioning matters: analysts are not giving Stryker much credit for the upper half of its outlook, so a quarter that keeps the high end credible could reset expectations upward.
The central question is the second-half ramp. Management's guidance embeds roughly 11% organic growth over the final two quarters, a meaningful step up from the 9% just delivered, and it leans heavily on capital equipment production recovering from the cyber disruption. July's call offered encouraging evidence on the demand side, with elevated backlog, a record month for Mako robots and no order cancellations. This quarter needs to show that the backlog is converting into shipments. Strong results in MedSurg capital lines and continued momentum from the full US launch of the Mako RPS handheld robot would validate the plan. A quarter in which backlog grows but revenue lags would suggest production is still the bottleneck and would raise doubts about the fourth quarter carrying too much weight.
The second test is vascular. A supply disruption at an Inari peripheral vascular plant pushed US Vascular down 6.7% in the second quarter and cost the company an estimated 50 to 75 basis points of growth, including emergent procedures that simply went elsewhere. Management said the issue should be manageable by the end of the third quarter. Any sign that backorders persist into the fourth quarter would chip away at the 11% assumption and, more importantly, at confidence in management's operational forecasting after two consecutive quarters of self-inflicted problems. Updates on the newly acquired AVS intravascular lithotripsy business and a possible above-the-knee launch before year-end would help restore the vascular growth narrative.
Orthopaedics deserves attention as well. US hips and knees slowed to roughly 5% and 6% growth last quarter, partly on tougher comparisons, while new products such as Triathlon Gold and the Encompass ankle are still ramping. Margin commentary will also matter, since ongoing cyber remediation costs, lost manufacturing absorption and raw material inflation all weigh on second-half profitability, and proposed CMS reimbursement cuts loom in the background.
Sentiment has swung from mildly bullish before the last report to mildly bearish now, and the stock trades well below its 200-day moving average of about $326, sitting in the lower part of its post-earnings range. That combination sets a lower bar than the operating story might suggest. If Stryker shows capital shipments accelerating and vascular supply normalized, the reaffirmed guidance starts to look conservative. If either piece slips, the market's skepticism about an aggressive back-half plan will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 11 hours | |
| 12 hours | |
| Oct-21 |
Healthcare Stocks Are Rallying, and Flashing a Warning for the Rest of the Market
SYK
The Wall Street Journal
|
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-07 | |
| Oct-06 | |
| Oct-06 |
