AbbVie Faces A Street Forecast Above Its Own Guidance As Immunology Momentum Meets Apogee Dilution
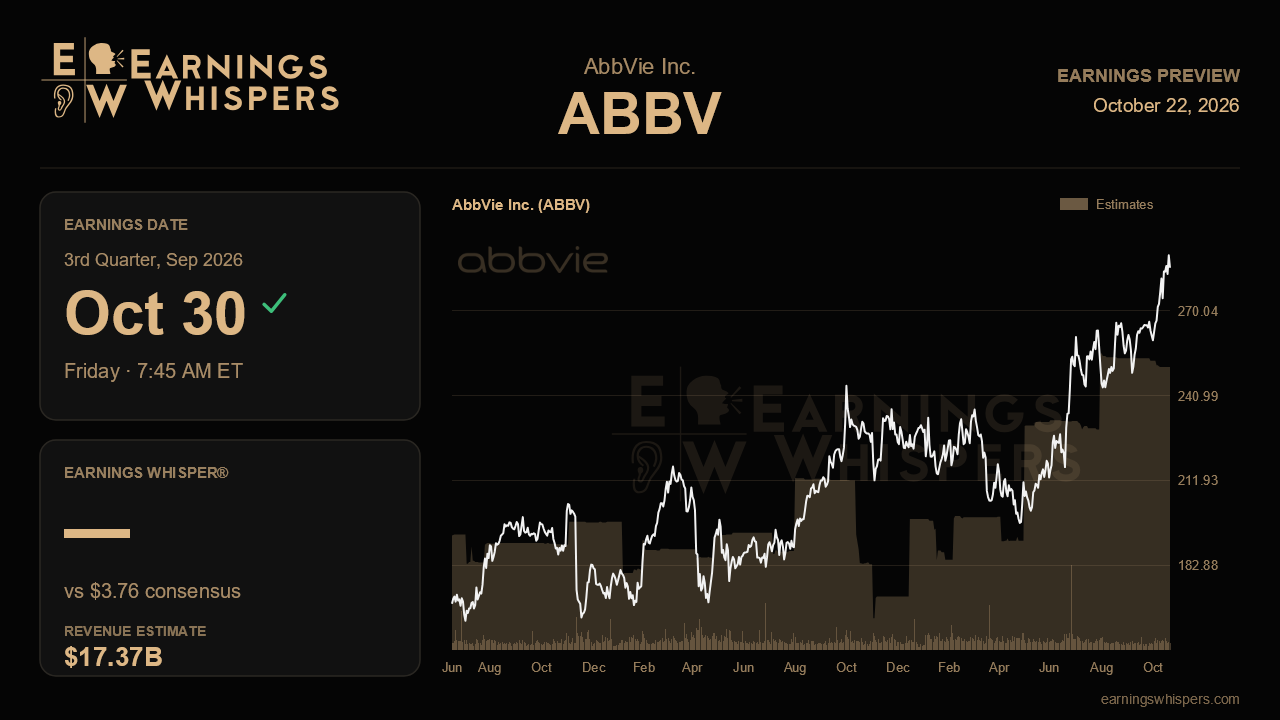
AbbVie heads into its third-quarter report with an unusual tension. Its revenue outlook has climbed every quarter this year, yet its earnings-per-share forecast keeps moving the other way. Analysts have quietly sided with the business over the guidance. That makes this report less about whether the core franchise is healthy and more about whether it is healthy enough to absorb the cost of the Apogee deal.
The Street expects earnings of $3.76 a share on revenue of about $17.37 billion when AbbVie reports before the open on October 30. Sales would rise roughly 10% from a year ago, about the same pace as the 10.2% growth posted in the second quarter. The projected doubling in EPS from $1.86 looks dramatic, but it mostly reflects a depressed year-ago comparison rather than a sudden step change in profitability. The more useful benchmark is sequential. Consensus calls for a modest gain from the $3.65 earned last quarter on roughly $380 million of additional revenue, which is a reasonable but not trivial ask.
The real friction is in the annual numbers. Management's latest full-year EPS range is $13.87 to $14.07, down from $14.37 to $14.57 when the year began. Last quarter's cut was largely an accounting story. Roughly 14 cents of Apogee dilution more than offset about 10 cents of improvement in the underlying business, and net interest expense guidance rose to about $2.9 billion to fund the deal. Even so, the consensus of $14.14 sits above the top of management's range. Analysts are effectively betting on another round of operational upside, so a quarter that merely tracks guidance could read as a disappointment on the annual line.
The case for that bet rests on immunology and neuroscience. Skyrizi delivered $5.5 billion last quarter, up 24%, and Rinvoq topped $2.5 billion, up nearly 24%. Full-year targets for Skyrizi and the neuroscience portfolio have each been raised three times this year, now to $21.7 billion and $12.7 billion. To validate that trajectory, AbbVie needs Skyrizi and Rinvoq to hold growth near those levels without leaning on currency, since the expected FX benefit was already trimmed to about half a point. Continued sequential gains in Vyalev, which jumped 27% last quarter to $256 million, would support management's view that it is on a blockbuster path. A fifth revenue raise would extend the pattern. Holding revenue guidance flat after three increases would be the first crack in the narrative.
The soft spots are well known, but they still matter at the margin. Aesthetics slipped again last quarter, with Juvederm down 6.6%. Oncology fell 2.4% operationally as Imbruvica dropped almost 30% under Medicare price negotiation. Any sign that aesthetics is stabilizing would be a genuine positive surprise, while deeper Imbruvica erosion would test how much growth is left over from immunology. On the catalyst front, updates on the Apogee closing, the expected Tevapidon approval and the pending decision on subcutaneous Skyrizi induction in Crohn's disease, which management framed as a driver of acceleration into 2027, should shape how the market views the outlook beyond this year.
The market has already leaned in. Shares have gained 12.8% since the last report, beating the S&P 500 by about nine points. At $284.80 the stock sits roughly 2% below its post-earnings high of $291.40 and far above its 200-day average near $235. Sentiment has also warmed noticeably, roughly doubling from the prior quarter. A stock testing its highs with analysts already above guidance leaves little room for a merely clean quarter. The deciding question is whether underlying growth is strong enough for management to close the gap between its EPS range and the Street's number. That would show that Apogee's dilution is a temporary toll rather than a lasting drag.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 11 hours | |
| 12 hours | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 |
Can This Small Biotech Enter A $4.3 Billion AbbVie Market? Rapport Rises
ABBV
Investor's Business Daily
|
| Oct-20 | |
| Oct-20 | |
| Oct-19 | |
| Oct-18 | |
| Oct-17 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 |
