BP Must Show Margins Can Climb Even As Revenue Cools, With Shares Near A Breakout
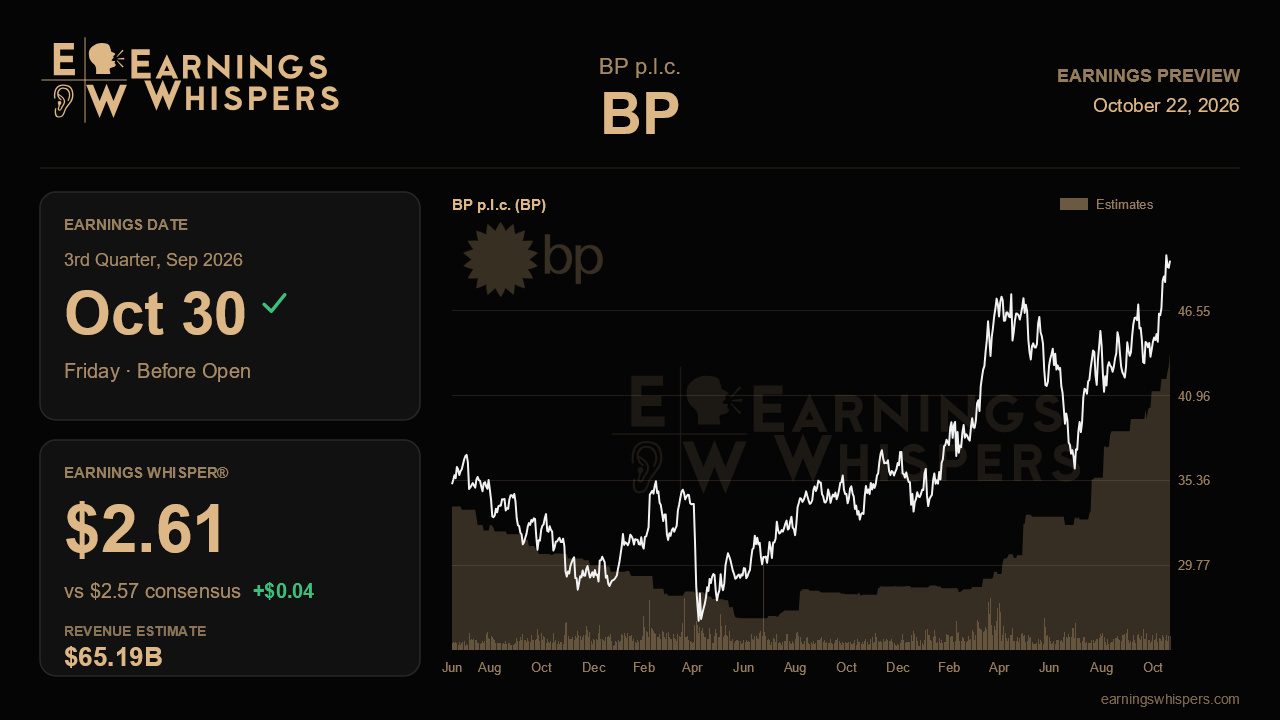
BP heads into its third-quarter report with an unusual equation for investors to solve. Wall Street expects revenue to fall from the prior quarter while profit per share rises meaningfully. That combination only works if margins widen, and with the stock trading near its highest level since the last report, the market appears to be betting that they will.
When BP reports before the opening bell on October 30, analysts are looking for earnings of $2.57 per share on revenue of about $65.19 billion. Against the year-ago quarter, that is a dramatic step up: earnings are projected to roughly triple, rising about 202% from $0.85, while revenue is expected to climb about 32% from $49.25 billion. The sequential picture is more nuanced. Last quarter BP earned $2.22 per share on $70.11 billion in revenue, so the consensus implies roughly $5 billion less top-line activity producing about 16% more profit per share. The Earnings Whisper of $2.61 sits only slightly above consensus, a small enough gap that it signals a modestly elevated bar rather than a demand for a blowout.
BP has not provided a fresh, explicit outlook that maps cleanly against these figures, which leaves the quarter's numbers to speak for themselves. That makes the mix of earnings across the business the key thing to dissect. For an integrated major, a quarter in which sales dip but earnings improve typically points to some combination of better realized margins in upstream production, stronger refining and marketing spreads in the customer and products business, cost discipline, or a favorable contribution from trading. The release should reveal which of those levers did the heavy lifting. Gains rooted in durable operating improvements, such as lower unit costs or stronger production from higher-margin barrels, would support the idea that BP's earnings power has reset higher. Gains that lean mostly on volatile trading results or one-time items would be harder to extrapolate, and a sophisticated market will likely discount them.
The year-over-year comparison also deserves scrutiny. A 32% revenue increase alongside a tripling in earnings suggests significant operating leverage, and the question is whether that leverage holds when the top line softens. If BP can deliver the expected profit on lower revenue, it validates the view that the company has become a leaner business. If earnings slip in step with revenue, it would suggest the prior quarter's strength owed more to the external environment than to anything BP controls. Updates on portfolio moves, including the proposed Angola upstream combination with Eni, could add color on how management is reshaping the asset base.
The market has already moved ahead of the report. Shares have gained about 15.3% since the last earnings release, beating the S&P 500 by nearly 14 percentage points. Sentiment has flipped sharply, from a bearish reading heading into last quarter to a solidly bullish one now. At $49.85, the stock trades well above its 200-day moving average of $42.43 and less than 1% below its post-earnings high of $50.27, putting it in position to test a breakout. The entire trading range has shifted higher from the previous quarter, when shares moved between roughly $36 and $47.66.
That backdrop raises the stakes. A stock that has rallied this hard into a report, with sentiment turning decisively positive, typically needs more than an in-line result to push through resistance. The central issue is whether BP can prove its margin expansion is real and repeatable. If profit rises even as revenue cools, the rerating has a foundation. If the numbers reveal that last quarter's earnings were simply riding a strong top line, the recent run may have gotten ahead of the fundamentals.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 8 hours | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-18 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 |
