Capri's Margin Gains Face A Revenue Test As Michael Kors Inventory Gap Bites
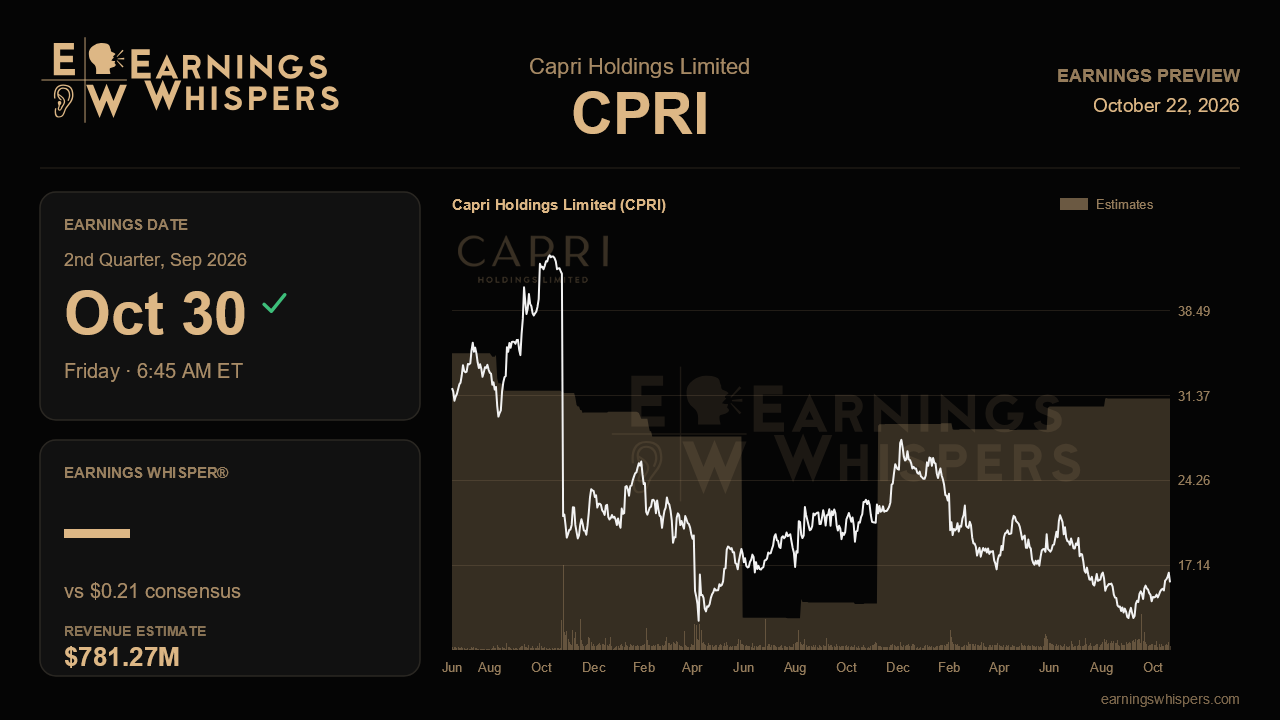
Capri Holdings heads into its fiscal second-quarter report with a peculiar setup: management has already told the Street that sales will shrink, and the real question is whether everything else in the story can hold together while they do. Last quarter the company beat on revenue, margin and earnings, then cut its full-year sales outlook anyway, preserving its profit target only by trimming expenses. This report is the first chance to see whether that trade-off was prudent housekeeping or an early sign that the Michael Kors recovery keeps slipping further out.
Expectations are tightly anchored to guidance. Consensus calls for earnings of $0.21 a share on revenue of $781.3 million, essentially on top of management's outlook for about $0.20 and roughly $780 million. Revenue would fall nearly 9% from the $856 million reported a year ago, a genuine contraction, even as earnings swing from a three-cent loss to a modest profit. That eye-catching earnings growth rate says more about a depressed comparison than about booming demand. With the Street parked right at guidance, a clean match is the baseline, and the details beneath it will matter far more than the headline numbers.
The biggest of those details is Michael Kors, guided to about $645 million. Management attributed the weakness to specific, largely temporary factors: roughly $50 million of inventory stuck in Asian port congestion and transit delays, about $15 million of softer business in Europe and the Middle East tied to regional conflict and thinner tourist traffic, $10 million of currency pressure, and a $10 million reversal of wholesale timing that flattered the prior quarter. Investors should want evidence that the inventory problem is being resolved, ideally with the delayed goods landing in time to support the back half. If the shortfall proves larger, or if the Europe softness looks like a demand issue rather than a shock, the reiterated second-half recovery becomes harder to believe. Encouragingly, wholesale point-of-sale turned positive last quarter, led by double-digit accessories growth at partners; a repeat would suggest the brand is healing even if reported revenue lags. Retail, which was still down high single digits, and the outlet channel, where new product arrived late, need to show at least stabilization.
Margins are where the bull case lives. Gross margin climbed to 65% last quarter, up 200 basis points, on more full-price selling, higher average prices and lower tariffs. Some pressure is plausible if air freight is needed to cover the inventory gap, so holding margins near that level would be a meaningful validation. Jimmy Choo is the other pillar: revenue accelerated to 10.5% growth with a 7.3% operating margin, well ahead of plan. Sustaining high-single-digit growth there would reinforce that Capri's turnaround is not resting solely on cost cuts.
The market has grown more skeptical. Bearish sentiment has more than doubled from the prior quarter, and the shares have slipped about 4% since the last report, lagging a roughly flat S&P 500. At $15.70, the stock sits well below its 200-day moving average of $18.21 and in the upper half of a post-earnings range of $12.40 to $16.96, a band that has shifted noticeably lower than the prior quarter's. That cautious positioning means the bar for relief is not especially high, but it also signals little patience for another cut.
Ultimately, this report turns on whether Capri can reaffirm the $3.4 billion revenue and $2.15 earnings outlook without leaning further on expense cuts. If the Michael Kors headwinds look truly transitory and margins hold, the reduced plan starts to look credible. A second consecutive trim to the sales outlook would suggest the recovery timeline is still drifting, regardless of how good the margins appear.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Sep-22 | |
| Sep-22 | |
| Sep-16 | |
| Sep-15 | |
| Sep-08 | |
| Sep-04 | |
| Aug-19 | |
| Aug-15 | |
| Aug-14 | |
| Aug-10 | |
| Aug-06 |
