Regeneron's First Full Sanofi Profit Share Meets An Eylea Biosimilar Test
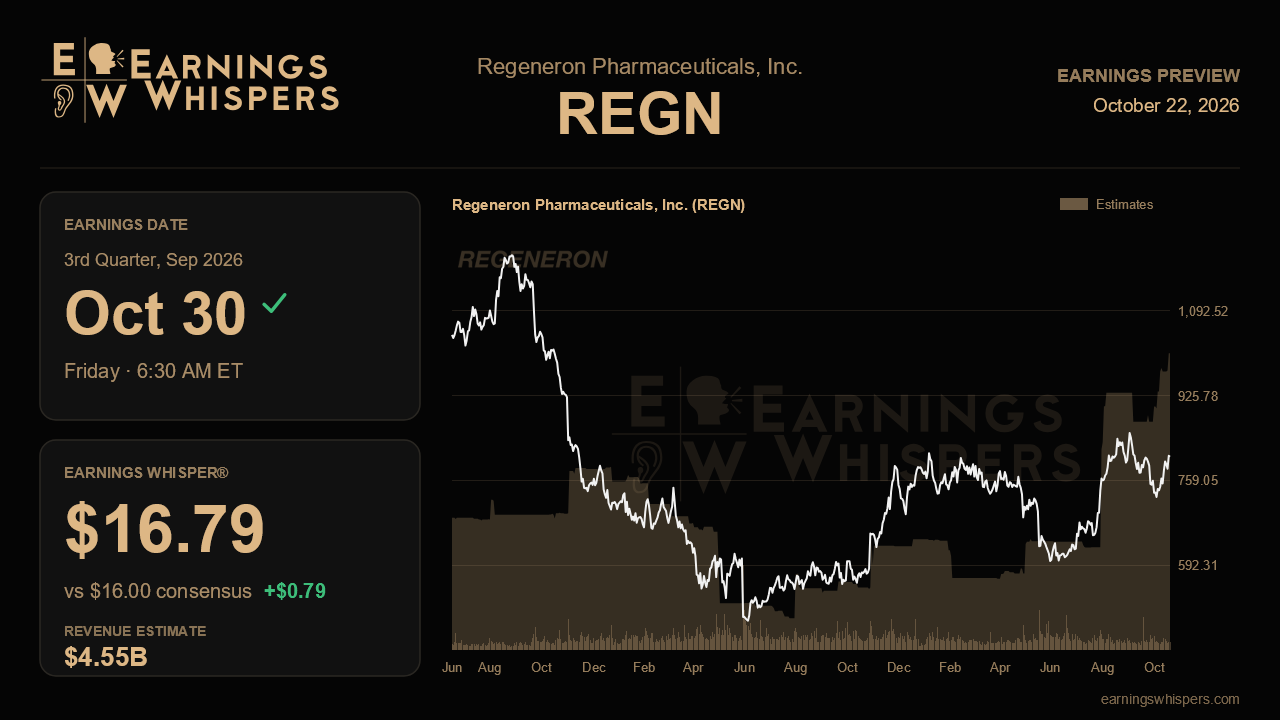
Regeneron heads into its third-quarter report with an unusual mix of tailwind and headwind arriving at the same time. This is the first quarter in which the company collects its full share of Sanofi collaboration profits, after fully repaying the development balance last quarter. It is also the first full quarter in which multiple biosimilar versions of the original Eylea 2mg compete in earnest. How those two forces net out will decide whether the recent reacceleration story holds.
The Street is setting a high bar. Consensus calls for non-GAAP earnings of $16.00 per share on revenue of about $4.55 billion. That revenue figure would mark growth of roughly 21% from a year ago, a step up from the 17% pace of the second quarter. The earnings estimate is a sharp jump from the $12.03 reported last quarter and the $9.63 of a year ago. Part of that sequential leap is mechanical. Second-quarter results absorbed a $0.99 charge from acquired in-process research, and the Sanofi profit-share step-up should fall almost entirely to the bottom line. The whisper number of $16.79 sits about 5% above consensus. That suggests some investors believe the Sanofi math is not fully reflected in published estimates. Management did not raise its full-year outlook last quarter. It only modestly refined it, so there is no explicit company target to measure the Street against.
The cleanest validation of last quarter's upbeat tone would come from Eylea HD. Sales hit a record $596 million, up 52% from a year earlier, and physician demand jumped 24% sequentially. That was a marked acceleration from roughly 10% quarterly demand growth in the prior two periods. Eylea HD now makes up about 60% of the U.S. franchise. Another quarter of double-digit sequential growth would show the conversion is outrunning biosimilar erosion on the older product. Management has guided for low-to-mid-teens sequential declines in Eylea 2mg in the second half, after a 13% drop to $412 million last quarter. A decline at the steep end of that range, paired with any stall in HD demand, would challenge the idea that the ophthalmology franchise has found its floor. Any update on the long-delayed prefilled syringe also matters. It is now targeted for year-end approval after slipping from mid-year.
Dupixent is the other swing factor. Management flagged that growth would moderate in the second half from about 38% in constant currency as recent indication launches annualize. A gradual slowdown is already expected. A sharp one would undercut the Sanofi tailwind just as it reaches full strength. Libtayo, which grew 29% and doubled its U.S. lung new-patient share to 20%, offers a smaller but useful read on commercial execution beyond the two flagships. On the pipeline side, any detail on talks with Sanofi's new chief executive about expanding the partnership to Dupixent follow-on programs could matter more to the stock than a few cents of earnings. The same goes for progress on the long-acting IL-13 antibody, now dosing atopic dermatitis patients.
Sentiment has warmed meaningfully. It remains slightly bearish but far less so than the negative reading ahead of the last report. The stock reflects that shift, up nearly 15% since the second-quarter release against a 5% gain for the S&P 500. At about $806, shares trade comfortably above the 200-day moving average and well above the prior quarter's range. They remain roughly 6% below the post-earnings high of $859, so this is a rerated stock rather than one pressing on a breakout.
With expectations reset higher and the oncology narrative dented by the fianlumab miss, the report needs to prove that Regeneron's growth now rests on durable pillars. That means full Sanofi economics plus Eylea HD gains large enough to absorb the biosimilar cliff. If both show up cleanly, the reacceleration thesis strengthens. If Eylea 2mg erosion outpaces HD conversion, the Sanofi windfall may look like it is masking a weaker core.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 14 hours | |
| Oct-20 |
EyePoint halves workforce and ends Phase III trial early after endpoint miss
REGN
Clinical Trials Arena
|
| Oct-16 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-12 | |
| Oct-09 | |
| Oct-08 | |
| Oct-06 | |
| Oct-02 | |
| Oct-02 | |
| Oct-02 | |
| Oct-01 |
