Exxon Mobil Must Prove Refining Windfall And Guyana Cash Inflection Can Outrun Lost Barrels
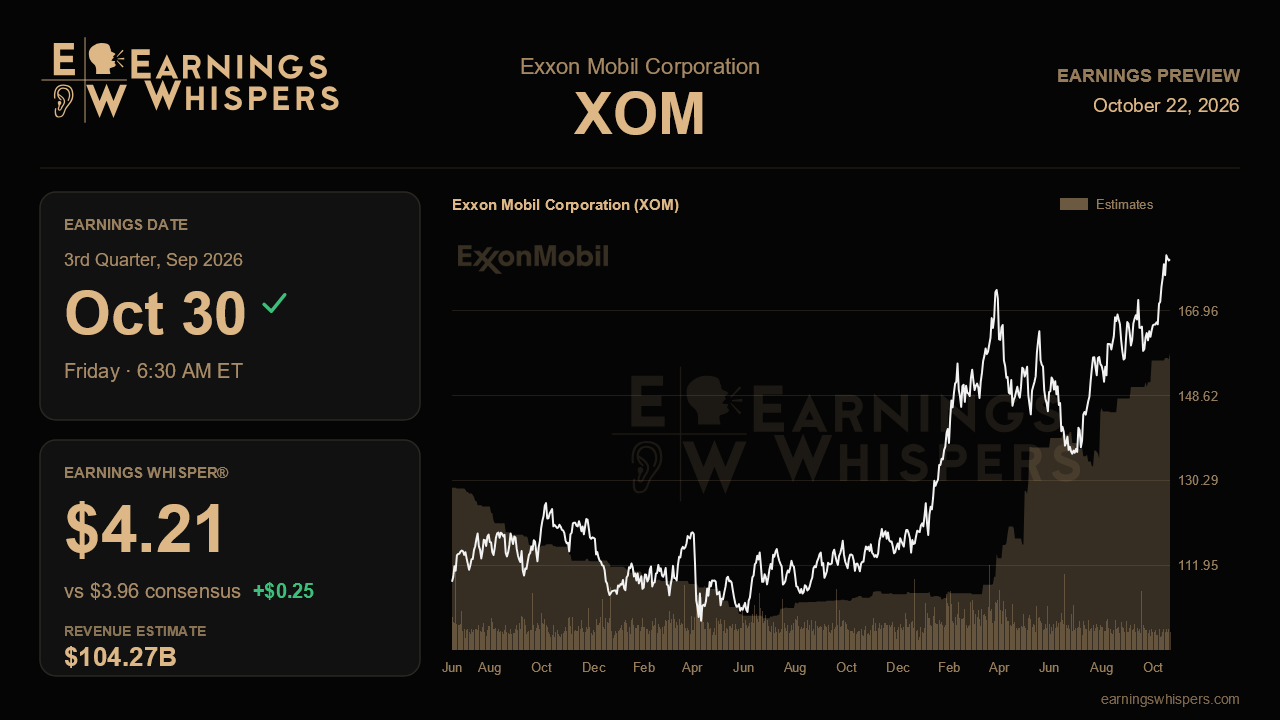
Exxon Mobil heads into its third-quarter report with an unusual math problem. Wall Street expects revenue to fall sequentially, yet earnings per share to climb. That only works if the margin story management told last quarter, built on tight refining markets, rebounding chemicals and a Guyana cash machine moving into a richer phase, is holding up even as roughly a tenth of upstream production remains sidelined by the Middle East conflict.
The consensus calls for EPS of $3.96 on revenue of $104.27 billion when the company reports before the open on October 30. That would more than double the $1.88 earned a year ago, a 110.6% jump, on revenue growth of 22.3%. The sequential comparison is more revealing. Last quarter Exxon earned $3.52 per share on $116.02 billion in sales, so analysts are effectively modeling about $12 billion less revenue alongside roughly 12% more profit. The Earnings Whisper of $4.21 sits about 6% above consensus, a meaningful gap suggesting that the buy side expects the margin tailwinds to show up more forcefully than published estimates assume. Exxon has not issued formal quarterly guidance, so the bar is being set by the narrative rather than by a number.
That narrative was confident. Management described second-quarter earnings of $14.5 billion, operating cash flow of $23.6 billion and free cash flow above $17 billion as industry leading despite the production hit. Chemical product margins rose about 180% from the first quarter, specialty products set records with best-ever base stock margins, and executives argued that refining would stay unusually profitable with about 3 million barrels per day offline through the Strait of Hormuz, China halting exports and Russian refineries disrupted. The cleanest validation this quarter would be downstream and chemical earnings that hold or improve on those levels, proving that last quarter was not a one-time spike. Watch also for evidence that higher crude prices, which management said had not fully flowed through inventories, are now lifting realizations rather than squeezing refining spreads.
Guyana is the newer and potentially more durable catalyst. Exxon said its roughly $55 billion investment and operating costs have been fully recovered, hitting the 75% cost recovery cap about two years earlier than planned, and it now expects 2030 Guyana free cash flow near twice the 2025 level. The tradeoff is lower volume entitlements over time. Investors should want early signs that the shift is translating into cash rather than just optics, along with updates on the fifth FPSO, slated to start by year-end, the potential ninth vessel and the four new exploration prospects. Structural cost savings, raised to $16.3 billion cumulative from $15 billion two reports earlier, offer another checkpoint; continued progress would support the claim that the new global operations organization and trading model are adding real earnings power.
The risks have not gone away. A prolonged Strait closure keeps volumes depressed, the damaged Qatar LNG trains face a multiyear repair, and a new European windfall tax on downstream profits, which Exxon is contesting, could dent the very segment carrying the quarter. Any sign that reopening is imminent also raises a question about how quickly the refining premium fades.
The market has already leaned in. Shares are up 15.8% since the last report, beating the S&P 500 by 12 percentage points, and at $178.09 the stock sits about 17% above its 200-day average and within roughly 1% of its post-earnings high of $180.26, testing a breakout. Sentiment has edged from slightly bearish to slightly bullish, a modest shift but one consistent with rising confidence. With the stock pressing its highs and the whisper above consensus, the central question is simple: can downstream and chemical margins, plus a richer Guyana cash profile, more than offset lost barrels? A clear yes keeps the story intact; anything less may leave a crowded trade looking for the exit.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 | |
| Oct-18 | |
| Oct-18 | |
| Oct-18 | |
| Oct-17 | |
| Oct-17 | |
| Oct-16 |
