Spotify Misses On EPS As Ads Finally Inflect, But Softer Q4 ARPU And Revenue Guidance Cloud The Margin Story
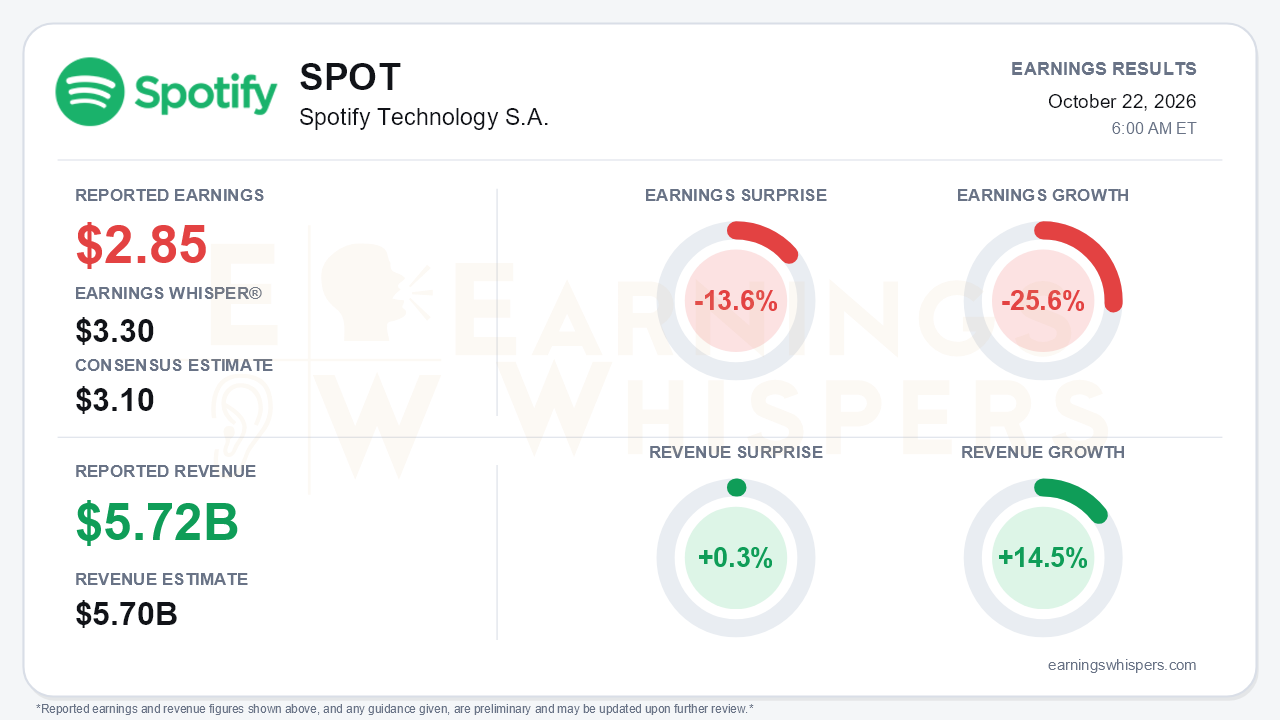
Spotify's third quarter delivered two different stories. On the operating side, management did what it said it would: ad-supported revenue inflected, subscribers beat guidance, and margins came in on plan. At the bottom line, the company reported earnings of $2.85 per share. That missed the $3.10 consensus by 13.6% and fell well short of the $3.30 Earnings Whisper number. Earnings declined 25.6% year over year. Revenue of $5.718 billion edged past the $5.70 billion consensus by 0.3% and grew 14.5% year over year. The guidance indicates revenue below estimates, which makes the beat look thin rather than reassuring. That is the central tension: operational execution was solid, but per-share earnings disappointed and the top line is slowing into the fourth quarter.
The quality of the EPS miss deserves scrutiny because it does not appear to come from the operating line. Operating income of €672 million landed just above the company's €670 million guide. Gross margin of 33.0% topped the 32.9% target and rose roughly 140 basis points year over year. With operations roughly on plan, the shortfall against per-share expectations appears to sit below operating income. The supplied materials do not identify the specific driver. The trajectory is still not pristine. Operating margin of 13.5% slipped from 13.7% in Q2 and 15.8% in Q1, reflecting the roughly €200 million in incremental 2026 investment management flagged earlier in the year. Free cash flow of €735 million also trailed Q2's €797 million and Q1's €824 million. Management characterized that decline as timing-related.
The most important development on the call was the long-promised advertising inflection. Ad-supported revenue growth jumped to 9% from 3% in both Q1 and Q2. Biddable formats now account for about 40% of ad revenue, and management guided Q4 further toward double digits. Subscribers reached 306 million, ahead of the 305 million guide and up from 300 million in Q2, with growth in every region. The Q4 subscriber target of 316 million implies another 10 million net adds. Management also said operating expense growth peaked in Q3 and should moderate into Q4 and 2027. That supports a Q4 operating income guide of €820 million and Q4 gross margin of 33.8%, up 70 basis points, for roughly 130 basis points of full-year expansion. Management's tone was noticeably more confident about durability and the payoff from its AI investments.
Bears still have legitimate ammunition. Revenue growth slowed to 14% from 15% in Q2, and the Q4 outlook implies similar or slower growth. Q4 ARPU growth is guided to just 4.5% to 5%, down from roughly 7% to 7.5% in Q2 and Q3, as price increases in more than 150 markets are lapped. MAU growth decelerated to 11%, adding 11 million users to reach 788 million. The Q4 target of 30 million net adds falls short of last year's record 38 million, partly because of deliberate friction on the free tier in emerging markets. Other overhangs remain:
- **Label renewals:** The UMG and Warner agreements come up for renewal in Q1 2027.
- **Gross margin investment:** Audiobook and Partner Program rollouts will weigh on Q4 gross margin.
- **AI risk:** Analysts raised concerns that AI agents could intermediate the listener relationship.
- **No 2027 view:** Management offered no 2027 guidance.
The catalyst list is long, however. Audiobooks expand from 22 to more than 180 markets by year-end, and the Spotify Partner Program extends to more than 50 markets. The company also announced:
- a new multi-year Joe Rogan deal;
- a Believe/TuneCore remix partnership;
- integrations with Meta Muse and ChatGPT.
Capital returns are also escalating. Buybacks reached $1.1 billion year to date, up from $361 million after Q1, and are now explicitly returning excess cash rather than merely offsetting dilution. Cash stands at €9.9 billion.
The market setup is more complicated than the surprise implies. Shares closed at $525.34 the day before the report, up 12.5% from the $466.95 open following the August release. That leaves the stock 5.7% above its 200-day moving average. It is also 8.8% below the $576 inter-earnings high set September 3, so some of the post-August rally had already been surrendered. Investor sentiment improved from slightly negative (-0.04) to modestly positive (0.08), a meaningful shift but still close to neutral rather than euphoric. The Earnings Whispers trend signals are largely positive, with price, sequential growth, momentum, and AVWAP all pointing up heading into the print. A whisper number $0.20 above consensus shows expectations were elevated, which makes the size of the EPS miss harder to dismiss.
The bottom line is that Spotify delivered the operating proof points investors were waiting for: an ad inflection, peaking expenses, subscriber beats, and expanding gross margin. However, it paired them with an EPS shortfall against high expectations and a fourth quarter defined by decelerating ARPU and revenue growth. The margin-expansion narrative remains credible. Yet with label renewals ahead and no 2027 guidance, the stock's run since August now has to be justified by profit leverage rather than top-line acceleration.
Read our earnings preview for Spotify Technology S.A.: https://www.earningswhispers.com/article/SPOT/20543
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 44 min | |
| 1 hour | |
| 1 hour | |
| 2 hours | |
| 2 hours | |
| 4 hours | |
| 4 hours | |
| 4 hours | |
| 4 hours | |
| 4 hours | |
| 5 hours | |
| 5 hours | |
| 5 hours | |
| Oct-20 | |
| Oct-20 |
