Nasdaq Falls Short Of The Whisper As Recurring Growth Accelerates And Market Services Stalls
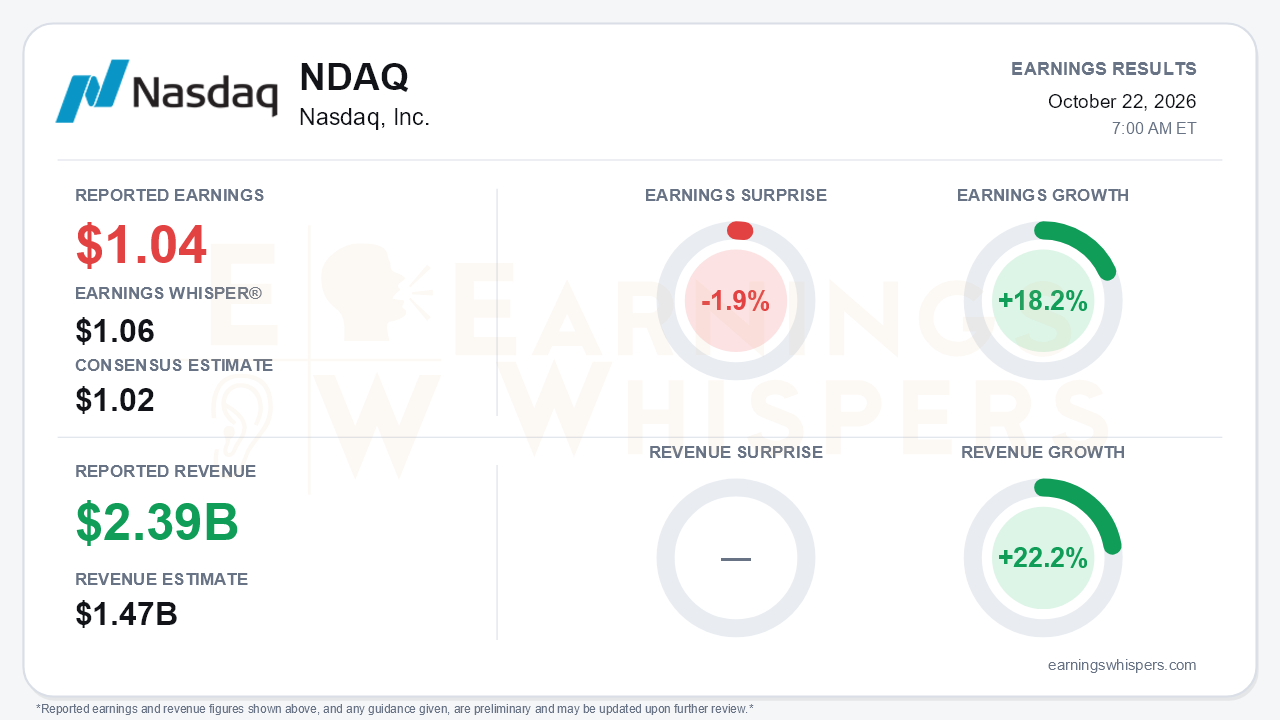
Nasdaq delivered non-GAAP earnings of $1.04 per share for the third quarter. That beat the $1.02 consensus but fell 1.9% short of the $1.06 Earnings Whisper number. Earnings grew 18.2% from a year ago, which is solid but slower than the 25% pace management cited for the second quarter. That deceleration is the central tension in the report. Nasdaq's subscription and solutions engine is accelerating on nearly every recurring metric, while its transactional Market Services business slowed sharply. The quarter also needed more expense than investors had planned for.
The revenue comparison needs context. Earnings Whispers recorded revenue of $2.393 billion, up 22.2%, against a $1.47 billion consensus, a 62.8% surprise. The reported figure is gross total revenue, which includes $912 million of transaction rebates and brokerage and clearance fees passed through to market participants. The consensus tracks net revenue. On that basis, Nasdaq generated $1.481 billion, up 13% reported and 14% organically, modestly ahead of the estimate rather than a blowout. The GAAP line also deserves some scrutiny. GAAP EPS of $0.96 rose 31%, helped by a $16 million favorable legal settlement and the absence of restructuring charges. Non-GAAP operating margin improved only one point to 57%, because organic non-GAAP expenses rose 12% against 14% organic revenue growth.
The operating story beneath the headline is notably stronger. Organic ARR growth reached 14% to $3.4 billion, up from 12% last quarter. Solutions revenue growth climbed to 18%, compared with 17% in the second quarter and 14% in the first. Financial Technology posted record 18% ARR growth, up from 16%, and the gains were broad:
- Capital Markets Technology ARR rose 19%.
- Verafin ARR also grew 19%, with revenue up 23% and net revenue retention of 111%.
- Verafin's 12 year-to-date enterprise signings already exceed the nine it signed in all of 2025.
- Agentic AI users rose to 850, from 750 in the second quarter and 500 in the first, with 70 paying clients.
Index was the standout. Revenue jumped 39% on record average ETP assets of $1.108 trillion and record trailing net inflows of $141 billion, which compares with $109 billion a quarter earlier. This is the call's most credible argument: Nasdaq's growth mix is shifting toward durable, recurring revenue.
Bears have legitimate ammunition elsewhere. Market Services net revenue grew just 2%, after 11% and 10% in the prior two quarters. The segment's margin fell five points to 61% as U.S. options capture weakened in a low-volatility environment. Management also flagged modest softening in the IPO market in recent weeks. Third-quarter listings dropped to 15 operating companies raising $32 billion, versus 26 raising $106 billion in the second quarter. Non-GAAP expense guidance was raised for the third straight time, to $2.55-$2.58 billion, partly tied to M&A. The fourth quarter also faces a tough Capital Markets Technology comparison against prior-year Calypso upfront revenue, and recent testing revenue is episodic.
The catalyst list is long and largely aimed at market structure:
- The LeveL Markets ATS acquisition closed October 15 and is expected to add $7-8 million of fourth-quarter revenue under the new Digital Liquidity Networks unit.
- 23/5 trading is slated for December 6.
- The Bruce ATS deal involves powering 24/7 U.S. equities trading.
- HSBC is extending Calypso into exchange-traded derivatives clearing.
- Hilton's listing transfer is scheduled for November.
- Some issuers are already asking to be early adopters of a planned 2027 equity token.
The SEC's innovation exemption for off-exchange tokenized venues is a counterweight that Nasdaq opposes, though the call characterized its impact as capped. Capital return remains aggressive. The company returned $496 million in the quarter, has a new $315-$385 million accelerated share repurchase planned for the fourth quarter, and has $2.2 billion of buyback authorization remaining.
Investors came in without strong conviction. Earnings Whispers sentiment improved from -0.08 to roughly neutral at -0.00, a meaningful thaw but not enthusiasm. Shares entered the report at $96.12, up 3.3% since the open after the July report and 6.2% above the 200-day moving average. They sat 4.8% below the August 27 inter-earnings high of $100.97, after recovering from a September 16 low of $87.94. Price, momentum, and AVWAP trend readings are positive, while sequential growth is neutral. That mix fits a stock that has rebuilt some trust but has not reclaimed its highs.
The bottom line is that Nasdaq's quality improved even as its headline growth cooled. Accelerating ARR, FinTech, and Index trends strengthen the long-term recurring-revenue thesis. However, the whisper miss, a stalled Market Services segment, rising expense guidance, softer IPOs, and a tougher fourth-quarter comparison suggest near-term EPS growth may keep moderating. Investors will have to decide how much of that slowdown the subscription engine can offset.
Read our earnings preview for Nasdaq, Inc.: https://www.earningswhispers.com/article/NDAQ/20529
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Oct-09 | |
| Oct-08 |
