American Airlines' Record Revenue Can't Outrun Fuel As Full-Year Guidance Slides Deeper Into A Loss
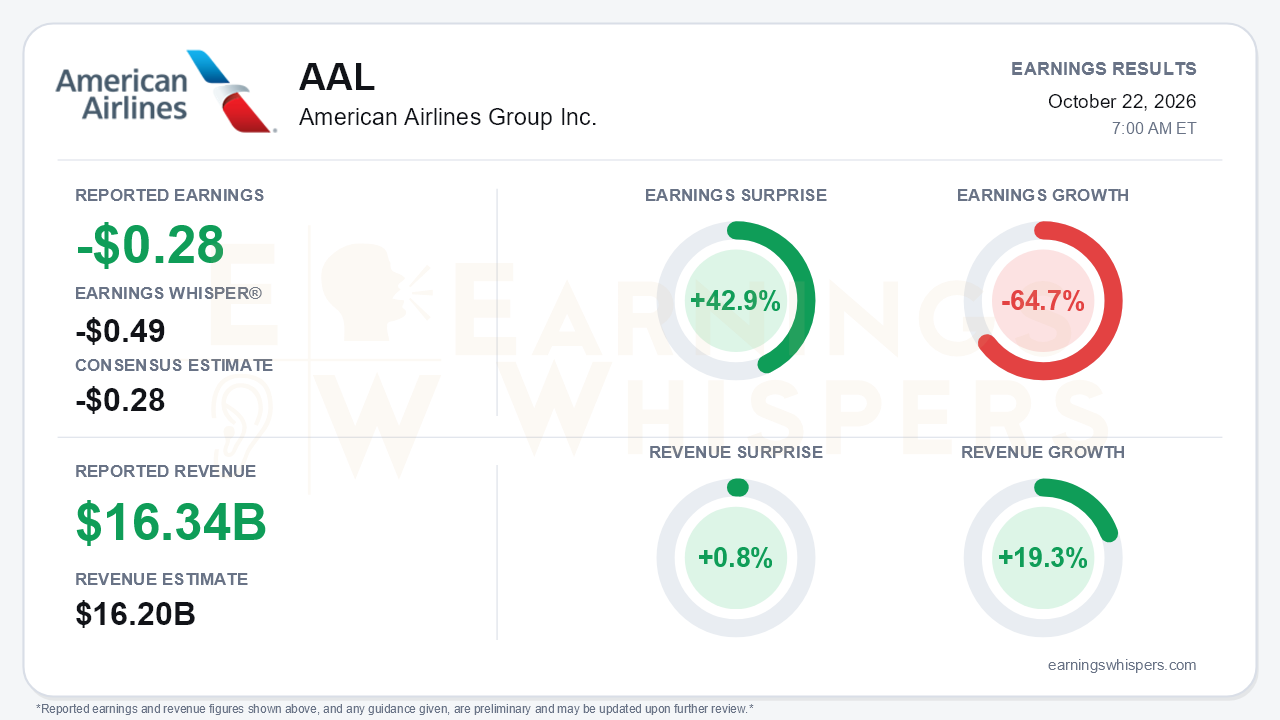
American Airlines Group delivered the revenue quarter bulls wanted and the earnings outlook they feared. The carrier posted an adjusted loss of $0.28 per share on revenue of $16.335 billion for the September quarter. That matched the consensus estimate, but it was 42.9% better than the Earnings Whisper number of -$0.49, a sign that investors had braced for worse. Revenue grew 19.3% year over year, beat consensus by 0.8%, and cleared the top of management's 16% to 19% guidance range. The bottom line moved the other way. Adjusted earnings fell 64.7% from a year ago, and the GAAP loss widened to $0.41 per share from $0.17. That is the central tension: American's commercial engine is accelerating, yet fuel is absorbing nearly every dollar of the improvement.
The scale of the fuel problem is stark. American paid $3.85 per gallon, up 62.7%, and fuel expense rose $1.9 billion, or 67.5%. Revenue rose about $2.6 billion, but total operating expenses rose $2.7 billion. Operating margin excluding special items slipped to 0.8% from 1.2%, and the pre-tax margin on the same basis fell to -1.4%. Non-fuel cost control was genuinely good: CASM-ex rose just 3.0%, which management called the best among network carriers. The GAAP-to-adjusted gap of $87 million after tax was driven largely by nonoperating items, including an impairment on the company's Republic Airways stake. That charge is noise rather than a core operating signal.
Beneath the headline, the revenue mix is improving faster than the prior quarter suggested. Managed corporate revenue rose roughly 28%, building on 26% in the second quarter and 13% in the first. Premium unit revenue climbed 18.5%, up from about 13% last quarter, versus 14.4% for Main Cabin. Total unit revenue rose 14.5%. Every international entity posted double-digit unit revenue gains, led by Latin America at 21.1%. However, this was a yield story, not a volume story. Traffic grew only 1.0% against a 4.2% capacity increase, load factor fell 2.6 points to 83.4%, and enplanements declined slightly. Yield rose 18.3%, so the yield-over-load strategy is clearly working on pricing. Even so, softer loads are a risk if pricing power fades.
The guidance cut is where the setup changed most. Management guided fourth-quarter revenue up 19.5% to 22.5%, an acceleration from the third quarter. It also expects fuel near $4.70 per gallon, nearly double last year, adding about $2.8 billion in expense. The result is a fourth-quarter adjusted loss guide of $0.50 to $1.10 and a full-year range of -$1.00 to -$1.60. That is down from -$0.65 to +$0.65 in July and a far cry from the $1.70 to $2.70 profit outlook offered at the start of the year.
The call added more caution:
- **No free cash flow target:** Positive full-year free cash flow was no longer reiterated, even as capex rose to $4 billion to $4.5 billion.
- **Slower 2027 growth:** Capacity growth will slow considerably, which management flagged as pressure on unit costs.
- **Fewer deliveries:** Expected aircraft deliveries slipped again, to 47.
- **Debt not falling:** The release shows net debt of $28.1 billion at quarter end on its own definition. On the call, however, management pointed to year-end net debt of roughly $30.5 billion, essentially flat, instead of the earlier promise of a reduction. The figures are not directly comparable, but the message is clear: deleveraging toward the 3.0x target is delayed.
- **Spirit:** The failed bid for Spirit assets removed one potential growth avenue.
The forward catalysts are real but longer-dated. They include:
- Starlink Wi-Fi extended to the entire mainline fleet of more than 1,000 aircraft.
- A widebody order campaign management said is close to wrapping up.
- Seven new long-haul routes for 2027, including Chicago-Tokyo.
- A plan to bring Alaska into joint businesses.
- Narrowbody retrofits lifting premium seating toward 40%.
- AAdvantage enrollments up 27.4% and cargo revenue up 29%.
Liquidity improved to $11.8 billion, and nine-month operating cash flow rose to $4.5 billion from $3.4 billion. Near-term balance sheet stress therefore looks contained.
Investors had already been marking the stock down. Earnings Whispers sentiment fell from 0.20 to roughly zero ahead of the report, a meaningful slide from modestly positive to neutral. Shares entered earnings at $12.24, down 12.5% since the open after the July report. That left them 10.4% below the $13.65 200-day moving average and 28.5% below the early-August high of $17.11. The stock sat just 5.2% above its inter-earnings low, set only two days before the release. The Earnings Whispers price and AVWAP trend readings remain negative, consistent with a stock that has been steadily de-rated as fuel estimates climbed. With expectations this compressed, an in-line adjusted print against a gloomier whisper and accelerating revenue guidance gave the stock some room. The deeper full-year loss still gives bears legitimate ammunition.
The bottom line is that American is winning the revenue battle and losing the fuel war, for now. Premium, corporate, and loyalty trends are improving quarter over quarter, and unit costs are disciplined. However, a third consecutive guidance cut, a delayed deleveraging path, and slower 2027 growth mean the earnings recovery depends heavily on fuel prices American cannot control.
Read our earnings preview for American Airlines Group Inc.: https://www.earningswhispers.com/article/AAL/20499
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 6 hours | |
| 9 hours | |
| 11 hours | |
| 13 hours | |
| 13 hours | |
| 14 hours | |
| 15 hours | |
| 15 hours | |
| 17 hours | |
| 18 hours | |
| Oct-21 | |
| Oct-20 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 |
