Argenx Beats As VYVGART Sales Accelerate, But Forte Costs, A $4 Billion Spending Plan, And Pipeline Pruning Complicate The Story
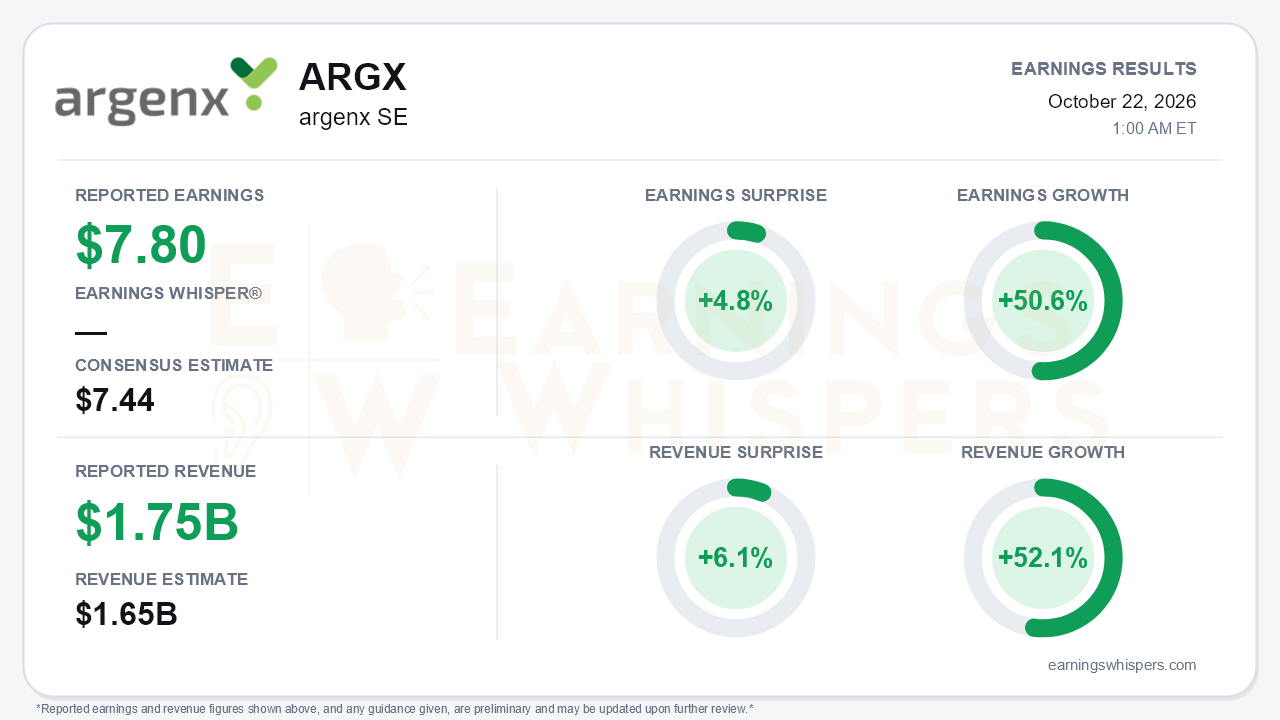
argenx delivered another clean beat on the commercial engine. Earnings were $7.80 per share against a $7.44 consensus, a 4.8% surprise. Revenue of $1.751 billion topped the $1.65 billion estimate by 6.1%. Earnings grew 50.6% year over year and revenue rose 52.1%. The core driver was VYVGART, with product net sales of $1.721 billion, up 54% year over year and 13% sequentially. The sequential pattern matters as much as the annual comparison: sales were roughly $1.3 billion in Q4 2025 and Q1 2026, then $1.5 billion in Q2 and $1.7 billion in Q3. That is a franchise gaining speed, not plateauing. The central tension is that the company is now spending that growth aggressively, and the bill showed up in the margin line this quarter.
The quality of the earnings beat deserves scrutiny from two directions. On one side, reported results absorbed roughly $150 million of Forte Biosciences acquisition expenses in SG&A. As a result, operating profit slipped to $486 million from $494 million in Q2, and reported operating margin fell to about 28% from roughly 33%. Excluding those costs, management put the operating margin near 37%, which would be a clear improvement. On the other side, the bottom line got meaningful help below the operating line. A $97 million deferred tax benefit cut income tax expense to just $32 million on $538 million of pre-tax profit, compared with $42 million a year ago on a much smaller base. Strip out the Forte charge and the tax tailwind, and the two roughly offset. The beat is real, but it was driven by sales rather than by any underlying margin story.
The call strengthened the demand narrative. U.S. sales reached $1.5 billion, up 16% sequentially after 15% growth in Q2, with stable net pricing. Payer coverage for the seronegative gMG launch jumped to about 96% of covered lives from roughly 55% at Q2. Management described a larger-than-expected halo effect on seropositive prescribing, and about 10% of seronegative prescribers were new to VYVGART. Management called it among the strongest quarters of patient growth since launch, with both MG and CIDP contributing. Rest-of-world sales rose to $158 million, up 70% year over year. The one soft spot was Japan, which dipped to $81 million from $102 million, but that reflects lapping a one-time $25 million distribution benefit rather than weakening demand.
The forward calendar is unusually dense. Several near-term events are lined up:
- an IMNM sBLA filing by year-end following the positive ALKIVIA study;
- an ocular MG submission and a pediatric MG PDUFA date in February 2027;
- the autoinjector launch in the second half of 2027;
- the December readout of the Phase 3 EMPASSION study, a head-to-head trial of empasiprubart against IVIG in MMN.
Management now frames up to five potential U.S. launches in 2027. The Forte deal adds FB102, which is moving to Phase 3 in celiac disease. Bears have legitimate ammunition, however. Dermatomyositis missed its primary endpoint in ALKIVIA and will require another registrational trial on an undisclosed timeline. The Sjögren's and thyroid eye disease programs were discontinued after futility analyses. EMPASSION is a binary non-inferiority test, a format that carries genuine risk. Spending is also stepping up: combined R&D and SG&A guidance is now about $4 billion for 2026, roughly 45% growth, versus earlier guidance implying growth near 30%, and 2027 spending has not been guided. Cash and current financial assets stood at $3.7 billion. That compares with $4.4 billion at year-end 2025 per the release, and with $5.2 billion at Q2 per the call, after roughly $2.1 billion was paid for Forte.
The market setup is more complicated than the surprise implies. Shares hit a 52-week high of $1,072.75 on September 2, then slid to an inter-earnings low of $787.73 on October 8. They entered the report at $890.05, 17% below that peak, only 2.2% above the opening price after the July report, and 4.5% above the 200-day moving average. Investor sentiment improved from -0.11 to -0.01. It moved meaningfully toward neutral but is still not positive, suggesting expectations were tempered rather than euphoric heading into the print. The Earnings Whispers trend signals lean positive on sequential growth and momentum, while AVWAP remains negative, consistent with a stock that has not recovered its September highs.
The bottom line is that argenx's commercial franchise is accelerating, and the quarter's beat rests on genuine demand rather than accounting. The investment debate has shifted, though. The question is no longer whether VYVGART can grow. It is whether a roughly $4 billion spending base, a thinner but more focused pipeline, and a binary December MMN readout can justify a stock that has already given back much of its late-summer run.
Read our earnings preview for argenx SE: https://www.earningswhispers.com/article/ARGX/20503
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-19 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-08 |
Former Highflier Argenx Plummets On A Surprise Setback In Sjogren's
ARGX -11.83%
Investor's Business Daily
|
| Oct-08 | |
| Oct-08 | |
| Oct-08 | |
| Oct-08 | |
| Oct-08 |
