P&G Beats On A Volume-Led Sales Rebound, But A Swelling Cost Bill Keeps Guidance Pinned In Place
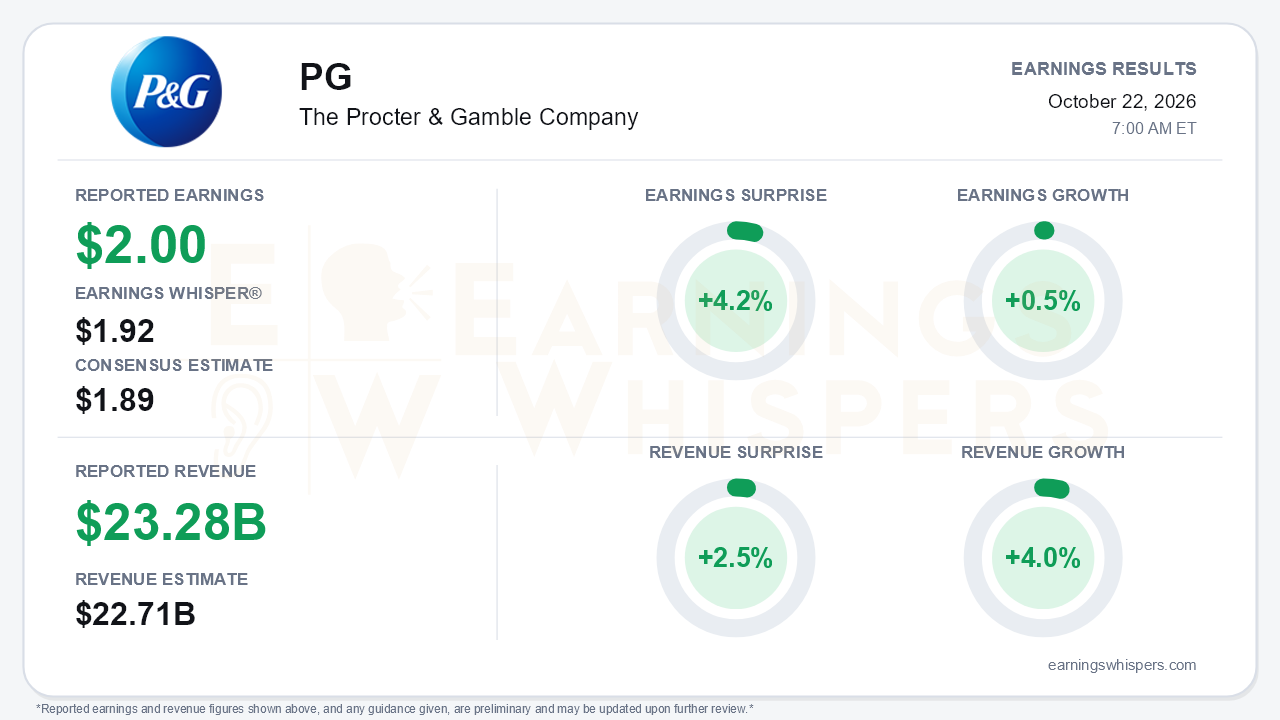
Procter & Gamble opened fiscal 2027 with the cleanest top-line quarter it has posted in some time, but the earnings line shows how little of that improvement is reaching shareholders. Core EPS of $2.00 beat the $1.89 consensus and the $1.92 Earnings Whisper number by 4.2%. Revenue of $23.28 billion rose 4.0% and topped the $22.71 billion consensus by 2.5%. Earnings, however, grew only 0.5% year over year, and currency-neutral core EPS was flat. That is the central tension: demand and market share are clearly improving, while costs are rising faster than management expected only three months ago.
The composition of sales growth was strong. Organic sales rose 4%, with 2.4 points from volume, 1.1 points from mix and only 0.4 point from pricing. All five segments grew organically, led by Beauty at 5.4% and Fabric & Home Care at 4.8%. Fabric & Home Care, the largest segment, delivered 4.3% volume growth. Below gross profit, the picture weakens. Core gross margin fell 150 basis points. Commodity costs took 140 basis points and product reinvestment another 140, while 120 basis points of productivity savings and 50 basis points of tariff relief offset only part of the damage. Core SG&A leverage of 80 basis points, helped by restructuring that cut 15% of non-manufacturing headcount, held the core operating-margin decline to 80 basis points. The quality of the beat therefore deserves scrutiny. It came from volume and overhead discipline, not from margin resilience, and Baby, Feminine & Family Care pre-tax earnings fell 4% despite 3% sales growth.
The call made the reacceleration more credible. Organic growth reached 4% after roughly 0% in the fourth quarter of fiscal 2026 and 3%+ in the third quarter. Volume turned positive after being flat. More than 70% of P&G's top U.S. customers are now holding or growing share, up from about 50% in the second half of fiscal 2026 and below 10% in the first half. Management is targeting more than 80% by calendar year-end. Twenty-nine of the top 50 category-country combinations held or grew share, compared with 23 last quarter. U.S. category growth improved to about 3% from about 2%. Greater China grew 8%, and SK-II rose 12-13%. Management's tone was noticeably more confident.
Some of that strength needs a discount:
- About 3 points of China's growth came from Pampers gaining volume while a competitor was disrupted, which may prove temporary.
- Some European shipments were pulled into the quarter ahead of merchandising events.
- Management guided first-half organic growth to roughly 3%, which implies a second-quarter slowdown, partly because consumers are strained by high fuel prices.
- Family care has not yet returned to share gains, and Olay China is still not growing.
The forward cost math is where bears have legitimate ammunition. P&G raised its after-tax commodity, energy and freight headwind to about $1.4 billion, assuming $100 Brent, from about $1.0 billion at $90 in July. Management noted that spot oil is above $110. Net interest expense doubled to about $300 million after tax on Thorne-related borrowing; short-term debt due within one year rose to $17.0 billion from $11.3 billion. The total headwind now stands at $0.79 per share, an 11% drag on core EPS growth, up from $0.56. Only about 5% of the cost hit landed in the first quarter versus roughly 8% for the full year, so the heavier pressure arrives in the second quarter with little time to offset it. P&G will also need price increases in a promotional market.
Against that backdrop, guidance was reaffirmed rather than raised: 1-3% organic growth and core EPS of $6.89 to $7.11. Management explicitly declined to steer toward the upper end. All-in sales guidance moved to 2-4% to include Thorne, which closed in October and gives P&G a vitamin and supplement platform it plans to expand internationally. Other catalysts include:
- the U.S. launch of Pampers Amore, projected to exceed $100 million in its first year;
- a relaunch of Charmin and Bounty Essentials aimed at turning family care share in the second half;
- the November 19 Investor Day.
Cash generation remained solid, with 93% free cash flow productivity and $3.9 billion returned to shareholders.
The market had already priced in much of the recovery. Shares rose 10.9% from the open after the July report to $156.84 before this release. That left them 5.8% above the 200-day moving average and about 2% below the inter-earnings high of $159.98 set October 16, near the top of a range that bottomed at $140.20 on the day of the last report. Price and AVWAP trend readings are positive. Investor sentiment, however, stayed negative and edged slightly lower, from -0.24 to -0.26. Investors bid the stock up without becoming more optimistic about the earnings path.
The bottom line is that P&G delivered the volume and share recovery that skeptics doubted, and the operating story is healthier than it was two quarters ago. That improvement is being consumed by rising commodity, freight and interest costs. With guidance only held, a slower second quarter flagged and oil above the company's own planning assumption, the stock enters the post-report period near its highs on a stronger sales story but no stronger earnings outlook.
Read our earnings preview for The Procter & Gamble Company: https://www.earningswhispers.com/article/PG/20535
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 3 hours | |
| 5 hours | |
| 8 hours | |
| 8 hours | |
| 8 hours | |
| 9 hours | |
| 9 hours | |
| 11 hours | |
| 11 hours | |
| 11 hours | |
| 11 hours | |
| 11 hours | |
| 12 hours |
