Lockheed Martin Beats And Raises Again As Munitions Boom Drives Record $292 Billion Backlog, But F-35 Timing Clouds Aeronautics
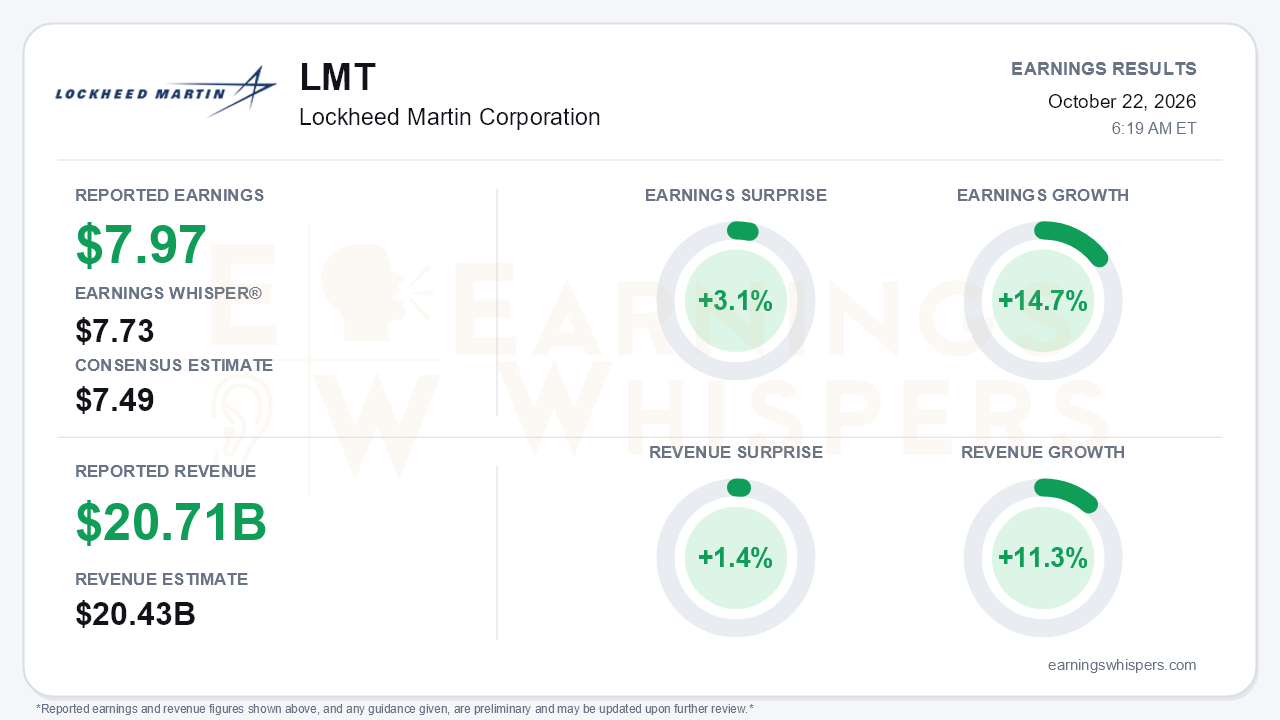
Lockheed Martin delivered the quarter defense bulls wanted. Third-quarter earnings of $7.97 per share topped the $7.49 consensus and the $7.73 Earnings Whisper number, beating expectations by 3.1%. Revenue of $20.711 billion beat the $20.43 billion consensus by 1.4%. Earnings grew 14.7% year over year and revenue grew 11.3%, a clear acceleration from the 7% sales growth the company posted through the first nine months. The bigger development was below the income statement. Backlog jumped 27% in a single quarter to a record $292.0 billion, up from $230 billion in June and $194 billion at year-end. Management also raised full-year guidance for the second straight quarter. The central tension is that Missiles and Fire Control is carrying an increasingly large share of the story, while Aeronautics, the company's largest segment, is moving the other way.
The quality of the beat deserves some scrutiny. Business segment operating profit, a non-GAAP measure, rose 10% to $2.229 billion. Segment margin slipped to 10.8% from 10.9%, and consolidated GAAP operating margin fell to 11.8% from 12.3% as unallocated 'other' costs rose to $158 million from $59 million. Earnings outpaced operating profit partly because of a lower effective tax rate of 15.1% versus 16.5%, driven by foreign-derived income deductions, and a slightly smaller share count. At Rotary and Mission Systems, a $40 million favorable contract resolution offset $45 million of unfavorable adjustments on Heavy Lift and Seahawk, so that segment's 4% profit growth was not clean. Aeronautics absorbed another $80 million of unfavorable adjustments on the F-16 and C-130, and its margin fell to 9.0% from 9.4%. Free cash flow of $3.0 billion trailed last year's $3.3 billion, which the company attributed to unusually high customer receipts in the prior-year quarter.
Missiles and Fire Control is the engine. Segment sales and profit each rose 24%, extending a sequence that ran from 8% growth in the first quarter to 19-24% in the second. PAC-3, THAAD, GMLRS and PrSM ramps drove the gain. The seven-year PAC-3 MSE award, valued at up to $58.6 billion, put $52.5 billion into backlog. It followed the $35 billion THAAD contract last quarter, and together they lifted segment backlog to $142.5 billion from $46.7 billion at year-end. Management raised MFC's 2026 sales guide to $17.25-$17.45 billion from $16.5-$16.9 billion. It also lifted the long-term framework to a mid-teens sales growth rate, up from 'at least double digit' in January. Capacity is being built to match: 2 million square feet of munitions facility additions across eight sites, plus large supplier awards to Boeing, L3Harris and Northrop.
Aeronautics is where bears have legitimate ammunition. The next F-35 lot award slipped into 2027, and segment guidance was cut to $31.1-$32.5 billion in sales and $2.92-$2.95 billion in profit. F-35 deliveries totaled 94 through nine months, down from 143 a year ago. More pointedly, the release disclosed that costs on the Lot 20 advance acquisition contract began exceeding contractual authorization and funding this quarter. Absent more funding, that will weigh on results and cash. A 10-year F-35 framework agreement offers longer-term visibility, but the near-term exposure is real. Several other risks also remain open:
- FY2027 began under a continuing resolution.
- Profit terms on munitions handshake agreements are not finalized.
- A pension contribution of more than $1 billion looms in 2027.
- The cash-tax tailwind will fade.
Guidance reflects that mix. Sales guidance rose to $80-$82 billion, EPS to $30.35-$30.75 from $29.95-$30.65, and free cash flow sharply to $7.8-$8.0 billion from $7.0-$7.2 billion. The segment profit outlook barely moved. The release shows roughly $8.575-$8.675 billion versus $8.5-$8.7 billion, while call notes framed it as a narrowed top end. Either way, the midpoint is essentially flat. In other words, the raise was mostly volume and cash rather than margin. Management also pointed to high-single-digit 2027 revenue growth with all four segments expanding.
Investor sentiment improved meaningfully into the report, moving from modestly negative (-0.15) to roughly neutral (+0.03). That suggests skepticism had eased without turning into enthusiasm. The stock has gone essentially nowhere, up just 1.2% since the open after the July report at $551.51. It sits 2.4% below its 200-day moving average. Shares swung from an August 18 high of $612.75 to an October 8 low of $497.00 and entered the report near the middle of that range. Most Earnings Whispers trend readings, including sequential growth and momentum, are positive, but the price trend remains negative. The fundamentals have improved faster than the share price.
The bottom line is that Lockheed's munitions franchise has fundamentally changed the scale and duration of its growth outlook. A record backlog, a second consecutive raise and stronger cash guidance all support a credible acceleration story. The beat leaned partly on tax and one-time items, however, margins are flat rather than expanding, and F-35 funding and contracting risk is now explicit. Investors have a stronger multi-year growth case, but the margin and Aeronautics questions are not yet resolved.
Read our earnings preview for Lockheed Martin Corporation: https://www.earningswhispers.com/article/LMT/20526
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 5 hours | |
| 5 hours | |
| 9 hours | |
| 10 hours |
Lockheed Reports Q3; U.S.-Israel Sketch Out postelection Iran Attacks
LMT +6.96%
Investor's Business Daily
|
| 10 hours |
Quantum Stocks: Defense Giants Northrop, Lockheed Take Aim At Frontier Technologies
LMT +6.96%
Investor's Business Daily
|
| 12 hours | |
| 12 hours | |
| 13 hours | |
| 14 hours | |
| 14 hours | |
| 14 hours | |
| 15 hours | |
| 15 hours | |
| 15 hours | |
| 15 hours |
