Buy, Hold, or Sell Meta Stock After Q3 Earnings & Stock Split Announcement?
Meta Platforms META) stock sold off on Thursday despite the social media giant delivering better-than-expected third-quarter results and announcing plans for a 2-for-1 stock split in early 2027.
While Meta's advertising business continues to grow impressively, concerns about surging artificial intelligence (AI) spending, deteriorating free cash flow, and mounting legal expenses have overshadowed its strong quarterly performance.
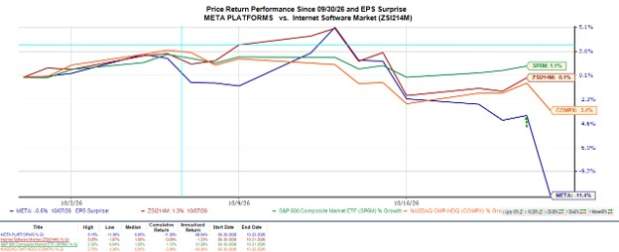
Image Source: Zacks Investment Research
Meta's Strong Q3 Results Overshadowed by Rising Costs
Meta reported Q3 revenue of $64.6 billion, climbing 26% year over year and topping Wall Street expectations of roughly $63.4 billion.
Reported earnings reached $3.83 per share, reflecting a $9.89 billion legal settlement charge. Excluding this charge, Q3 EPS was $7.40, exceeding expectations of $6.52 per share by 13%.
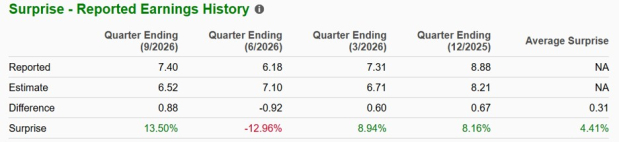
Image Source: Zacks Investment Research
However, investors are increasingly concerned about Meta's aggressive AI investments, with quarterly capital expenditures reaching $34.91 billion. More concerning, free cash flow turned negative at $2.12 billion compared to positive free cash flow of $10.63 billion in the prior-year quarter.
Meta also narrowed its full-year capital expenditure outlook to $135-$145 billion, raising the lower end from $130 billion. Furthermore, the company faces additional legal uncertainty following a $25 billion judgment in a New Mexico privacy case, which Meta plans to appeal.
Despite these concerns, Meta expects Q4 revenue of $73-$76 billion, which came in range of analyst consensus forecast of $73.65 billion or nearly 23% YoY growth (Current Qtr below).
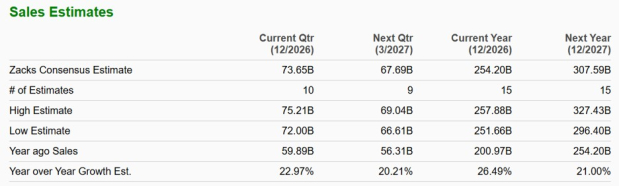
Image Source: Zacks Investment Research
Meta Announces Effective 2-for-1 Stock Split
Adding to the intrigue surrounding its Q3 report, Meta announced plans to introduce a new class of non-voting Class C shares in January 2027.
Under the plan, shareholders will receive one new non-voting Class C share for every existing Class A or Class B share they own, effectively doubling their total shares. As a result, Meta's publicly traded Class A stock is expected to trade at roughly half its pre-split price, with the new Class C shares accounting for the other half of shareholders' investment value.
Although the split won't change Meta's overall market valuation or the total value of an investor's holdings, the lower share prices could make Meta more accessible to retail investors and potentially attract renewed buying interest following the recent selloff.
Meta's Earnings Estimates Were Trending Lower
Notably, Meta's earnings estimate revisions were trending lower heading into its Q3 report.
Over the last 60 days, the Zacks Consensus EPS estimate for fiscal year 2026 (F1) has declined 7% from $32.20 to $29.94 per share, as shown below. Estimates for FY27 (F2) have slipped 1.69% from $34.41 to $33.83 per share.
These downward revisions reflect growing concerns about Meta's profitability as rising AI infrastructure investments weigh on operating margins and cash flow.
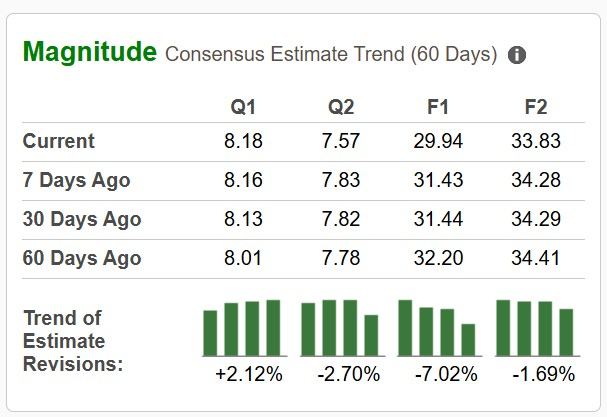
Image Source: Zacks Investment Research
Bottom Line
Meta Platforms stock currently lands a Zacks Rank #4 (Sell), reflecting the unfavorable trend in earnings estimate revisions as investors weigh its aggressive capital spending against its impressive revenue growth.
Nevertheless, Meta's better-than-expected Q3 performance, resilient advertising business, and upcoming stock split could start creating a more attractive long-term buying opportunity amid the recent selloff.
For now, investors may want to wait for earnings estimates to stabilize and for greater clarity on AI spending before aggressively buying the dip.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Meta Platforms, Inc. (META): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Mentioned In This Article
Latest News
| 32 min | |
| 44 min | |
| 2 hours |
Bill Ackman Says Meta Can Finance 'Whatever They Want,' Points to $82 Billion Cash
META -6.98%
Benzinga Prediction Markets
|
| 2 hours | |
| 2 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 4 hours | |
| 4 hours | |
| 4 hours |
