Southwest Beats On Record Unit Revenue, But A Fuel-Driven Guidance Cut Keeps The Earnings Story Under Pressure
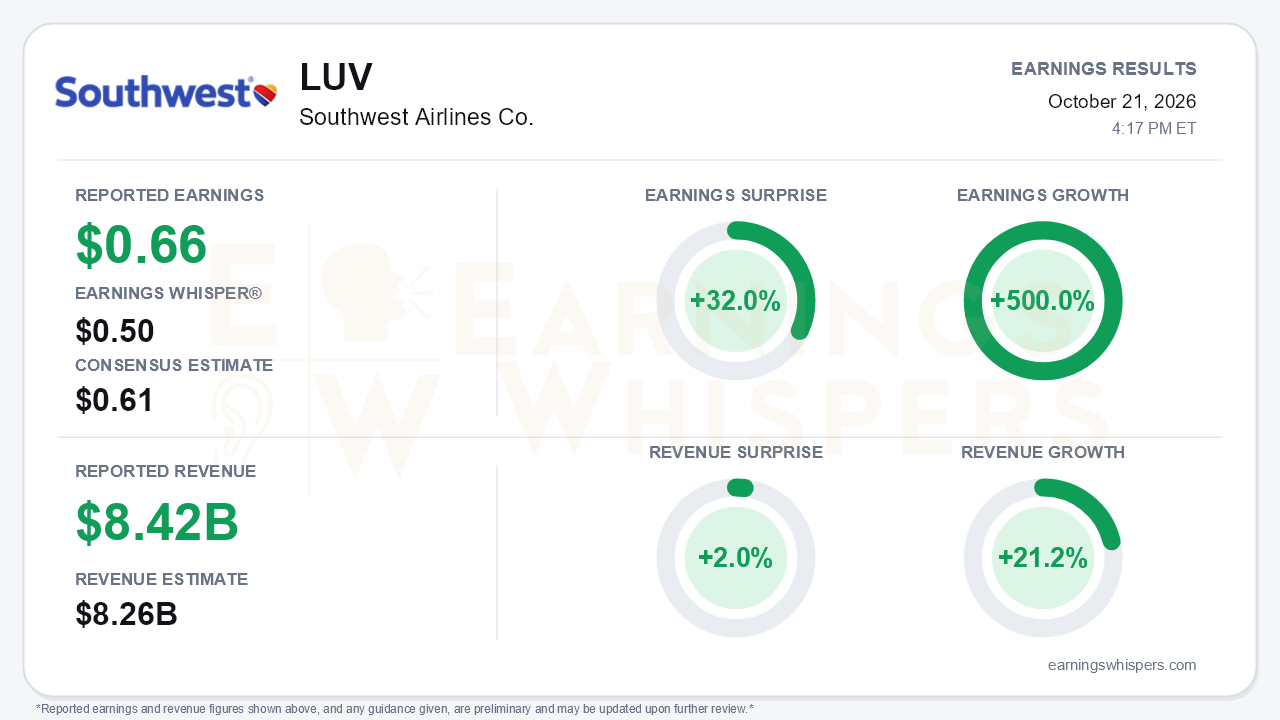
Southwest Airlines (NYSE: LUV) delivered a clean headline beat for the third quarter, with adjusted EPS of $0.66 against a $0.61 consensus and a far lower $0.50 Earnings Whisper number, a 32.0% surprise. Revenue of $8.422 billion topped the $8.26 billion consensus by 2.0% and grew 21.2% year over year, while adjusted earnings grew 500.0% from last year's depressed $0.11. On a GAAP basis, net income rose to $270 million, or $0.55 per share, from $54 million, or $0.10. The central tension is that commercial results keep exceeding plan while the earnings outlook keeps shrinking. Management cut full-year adjusted EPS guidance to $2.60 to $2.85, down from $3.25 to $4.25 in July and from 'at least $4' earlier in the year. Fuel drove most of that reduction, and the outlook landed below estimates.
The quality of the beat deserves scrutiny. Unit revenue was exceptional. RASM rose 21.6% on capacity down 0.4%, beating the 17.5% to 19.5% guide and accelerating from 20.1% in the second quarter, even as Southwest lapped last year's bag-fee launch. The average fare jumped 26.9%, and yield set an all-time record. However, passengers carried fell 3.2% and load factor was flat at 79.8%, so the growth came from price and product mix rather than volume. Below the revenue line, $214 million of gains on aircraft sales and sale-leasebacks sat inside operating results. That equals nearly half of the $452 million in adjusted operating income, and management expects those gains to fall sequentially in the fourth quarter. A 6.1% decline in diluted share count also flattered per-share comparisons. Fuel was the main drag. It ran $3.92 per gallon versus an assumed $3.70 to $3.75, adding $821 million of expense and creating a $1.08 headwind to adjusted EPS.
The call preserved a credible growth story on the revenue side. Managed business revenue rose 29% on flat capacity and has improved sequentially all year, with 20 of the company's 50 best managed-business booking days falling in the quarter. Fourth-quarter RASM is guided up 19% to 21%, with roughly 65% of revenue already booked. Management also said the seat initiative is tracking at or ahead of its roughly $1.5 billion 2027 EBIT target. Margins tell a less comfortable story. Adjusted operating margin of 5.4% was up 4.8 points year over year but down from 6.7% in the second quarter, and adjusted EPS fell sequentially from $0.94. CASM-X growth is also climbing, from 3.4% in the second quarter to 3.8% in the third and a guided 4.0% to 4.5% in the fourth. About a point of that comes from removing six seats per 737-700 for extra legroom. The rest reflects maintenance timing, healthcare costs, advertising, and below-target on-time performance that won't be fully addressed until first-quarter 2027 schedules.
The catalyst list is long and mostly aimed at 2027:
- **Rapid Rewards overhaul:** the program changes take effect January 1, 2027, adding a Platinum tier with a companion pass.
- **New lounges:** the first Icon lounges are expected to open in late 2027.
- **Premium credit card:** Southwest's first premium Chase co-brand card launches next year.
- **Fleet:** the 737 MAX 7 is now certified, and 2027 deliveries should exceed 2026.
- **Financial targets:** the March 2, 2027 Capital Markets Day is where the multi-year targets will be tested.
Bears have legitimate ammunition as well. Management assumes fourth-quarter fuel of about $4.55 per gallon and expects it to stay elevated into 2027. Comparisons get tougher as 2025 initiatives are lapped. Capacity growth keeps getting trimmed, to about 1.2% for the year from 2% to 3% originally. Current debt maturities also jumped to $2.15 billion from $324 million at year-end, although $5.6 billion of liquidity and 1.9x gross leverage provide cushion.
The market setup is more complicated than the surprise implies. As of the report date, shares were at $39.88, down 12.4% since the open following the July report and about 8.2% below the 200-day moving average of $43.46. Earnings Whispers price and AVWAP trend readings remain negative. Investor sentiment, already slightly negative, weakened modestly from -0.18 to -0.23. That suggests investors were bracing for the fuel-driven reset and do not yet trust that record revenue will translate into earnings.
The bottom line is that Southwest's commercial transformation is producing industry-leading unit-revenue gains, but rising fuel and creeping unit costs keep absorbing them. The third-quarter beat leaned partly on asset-sale gains and a shrinking share count. The guidance cut, the third downward step this year, matters more to the earnings trajectory than the beat itself. Management's assertive margin-expansion talk for 2027 will need to be backed by concrete targets in March, and by fuel cooperating, before the stock's downtrend has a fundamental reason to reverse.
Read our earnings preview for Southwest Airlines Co.: https://www.earningswhispers.com/article/LUV/20470
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 4 hours | |
| 13 hours | |
| 14 hours | |
| 15 hours | |
| 15 hours | |
| 17 hours | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-16 |
Southwest just updated Rapid Rewards: What to know about the new elite status tiers
LUV
Yahoo Personal Finance
|
| Oct-15 | |
| Oct-15 |
