Valero's Crack-Spread Windfall Nearly Doubles EPS Again, But Its Modest Beat And Cash Hoarding Raise The Question Of Durability
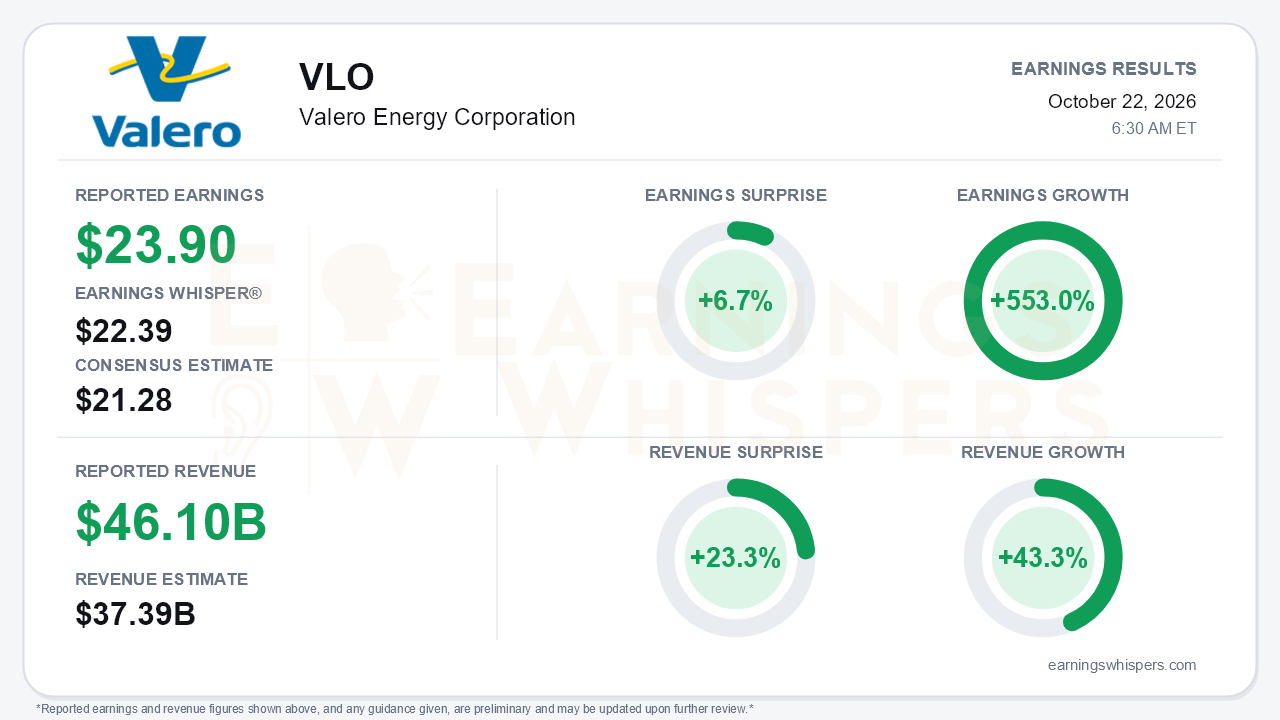
Valero Energy (NYSE: VLO) delivered another extraordinary quarter. Third-quarter adjusted earnings reached $23.90 per share, ahead of the $21.28 consensus and the $22.39 Earnings Whisper number, a 6.7% beat. Revenue of $46.098 billion topped the $37.39 billion consensus by 23.3%. Year over year, earnings grew 553.0% and revenue grew 43.3%. Growth also accelerated sharply on a sequential basis. Adjusted EPS nearly doubled from $12.54 in the second quarter, which itself followed $4.22 in the first quarter. Yet the quality of the beat deserves scrutiny. The revenue surprise was more than three times the EPS surprise, which largely reflects Brent averaging $91.61 versus $68.14 a year ago. And against the whisper number, the bottom-line upside was a relatively narrow $1.51 for a company printing nearly $24 a share in a single quarter.
The quarter was a margin story, not a volume story. Refining throughput actually fell to 2.97 million barrels per day from 3.09 million a year earlier, mostly because the Benicia refinery has been idled. Even so, refining margin per barrel jumped to $39.24 from $13.14, and adjusted refining operating income rose to $8.8 billion from $1.7 billion. It was $4.5 billion in the second quarter. Product markets did the heavy lifting. Gulf Coast ultra-low-sulfur diesel cracks averaged $72.27 per barrel versus $21.05 a year ago, and North Atlantic diesel cracks topped $77. Valero also captured wider feedstock discounts: Maya traded $13.37 under Brent and Western Canadian Select $16.49 under, roughly double last year's spreads. A falling share count, at 285 million diluted shares versus 309 million, added to per-share leverage. Results were essentially clean, with the GAAP and adjusted figures separated only by $4 million of Port Arthur fire costs.
The call preserved a credible case that the environment is not fleeting. Management cited "high confidence" that the crack environment is sustainable. It also said it sees no demand destruction, pointing to U.S. wholesale gasoline up 4% and diesel up 2% year over year, plus a recovery in U.K. demand. Management tied crude dislocations to a freight spike, with VLCC rates from the Gulf Coast to Asia near $30-35 per barrel versus about $5 in 2025. That spike is widening discounts on Gulf Coast heavy sour crude, and Canadian heavy barrels are now trading $27-30 under Brent in the fourth quarter. Valero set a record for Venezuelan crude processing. The $230 million St. Charles FCC optimization came online on time and on budget and has already exceeded its investment-case EBITDA despite only partial operation. Fourth-quarter throughput guidance was raised for the Gulf Coast to 1.855-1.905 million barrels per day and for the North Atlantic to 480-500 thousand barrels per day.
Beneath the refining surge, several trends moved the wrong way. Renewable diesel operating income halved sequentially to $353 million from $717 million. Management attributed the drop to a DGD3 storm outage, foreign feedstock runs that do not earn the production tax credit, and D4 RIN weakness. Fourth-quarter renewable diesel guidance also softened, with volumes lowered to 325 million gallons and opex raised to $0.53 per gallon. Ethanol set a production record but slipped to $272 million from $318 million in operating income. On the cost side, refining cash opex rose to $5.03 per barrel from $4.70, and full-year G&A guidance climbed to about $1.1 billion from about $960 million. Mid-Continent and West Coast throughput guides were trimmed.
Capital allocation is the subtler shift. Valero repaid $526 million of maturing debt and built cash to $9.8 billion, up from $4.7 billion at year-end, while net debt-to-capitalization fell to 4%. At the same time, the payout ratio dropped to 52% of adjusted operating cash flow from 59% in the prior two quarters and 66% in late 2025. Management's newly explicit openness to acquisitions in the Gulf Coast, North Atlantic and ethanol suggests the cash may be earmarked for deals rather than buybacks. Some shareholders could view that as a mixed signal at peak-cycle margins.
Bears have legitimate ammunition on durability. Management itself flagged diesel crack compression if crude spikes and headline risk from SPR releases or easing Russian sanctions. It also warned that roughly 1.5 million barrels per day of industry turnarounds were deferred, setting up a heavier 2027 maintenance season. The market setup is more complicated than the surprise implies. Shares rose 47.3% since the opening after the July report, to $436.75, and sit about 57% above the 200-day moving average. They also entered the report about 5.4% below the 52-week high of $461.52 set on October 14. Investor sentiment nonetheless stayed slightly negative and weakened modestly, moving from -0.13 to -0.17. That pattern suggests a crowd that respects the numbers but doubts their staying power.
The bottom line is that Valero is converting an exceptional margin environment into record earnings, cash and balance-sheet strength. Its flagship refining system is running well, and management is guiding Gulf Coast volumes higher. However, the beat was modest relative to the run in the shares. Renewables are fading sequentially, costs are drifting up, and the payout is shrinking. The investment debate has moved from whether Valero can earn in this cycle to how long these cracks last and what management does with a nearly $10 billion cash pile.
Read our earnings preview for Valero Energy Corporation: https://www.earningswhispers.com/article/VLO/20550
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-22 |
US Refineries Are Running Near Their Limits. Fund Manager Sees Diesel Above $5 Into 2027
VLO
Benzinga Prediction Markets
|
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 | |
| Oct-14 | |
| Oct-14 |
