Bloom Energy Crushes Estimates And Raises Guidance A Third Time, But A Negative Cash-Flow Quarter Shows The Cost Of Scaling
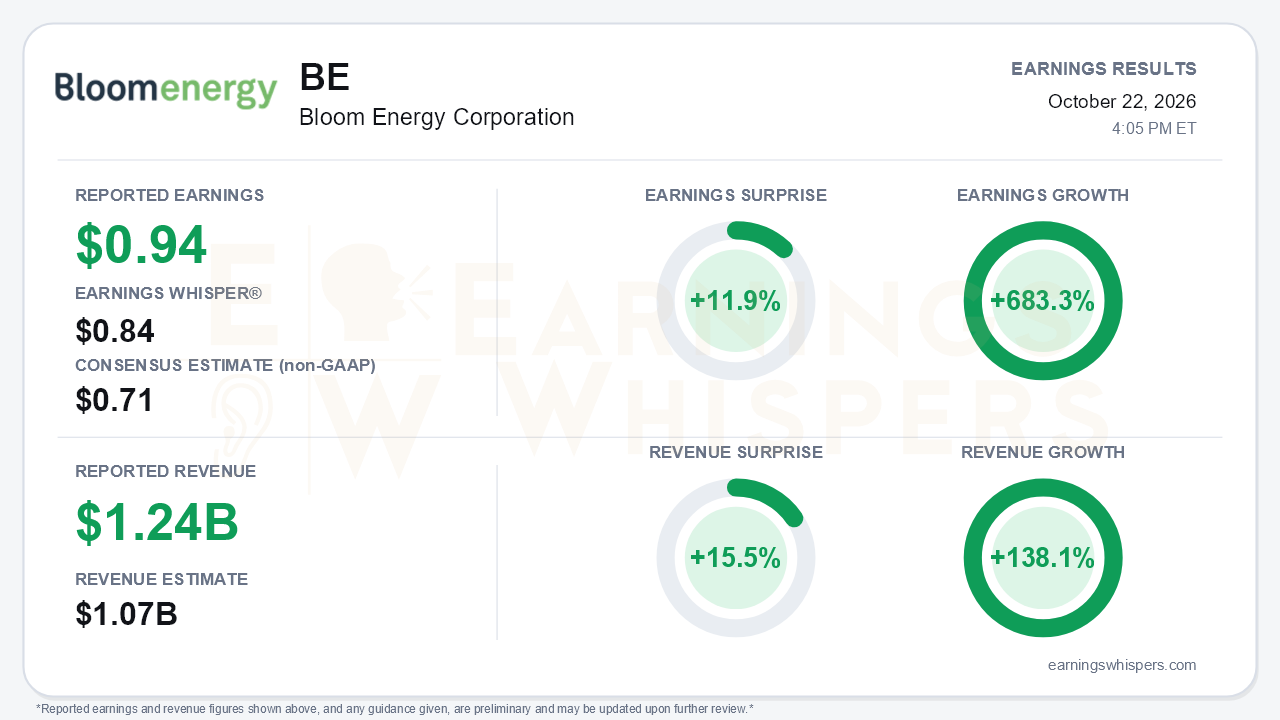
Bloom Energy delivered another quarter that pushed its growth story further than skeptics expected. Non-GAAP earnings of $0.94 per share beat the $0.71 consensus and cleared the $0.84 Earnings Whisper number, an 11.9% surprise. Revenue of $1.236 billion beat the $1.07 billion consensus by 15.5%. Earnings grew 683.3% year over year and revenue rose 138.1%. On a GAAP basis, Bloom earned $0.78 per diluted share versus a loss of $0.10 a year ago. Management also raised full-year guidance for the third time in 2026, to $4.4-$4.6 billion in revenue and $3.10-$3.40 in non-GAAP EPS. The central tension is that the income statement has never looked stronger, while the cash-flow statement had its weakest quarter of the year as Bloom spends heavily to meet demand.
The earnings beat was driven mainly by operations rather than accounting. Product revenue crossed $1 billion for the first time, at $1.07 billion, up 179% year over year. Non-GAAP product gross margin improved for a third straight quarter, from 35.3% in Q1 to 37.2% in Q2 and 38.4% in Q3. Non-GAAP operating expenses rose only 26% year over year against revenue that more than doubled, which lifted non-GAAP operating margin to 23.1% from 8.9% a year ago. Two caveats matter.
- **Margins outside product:** Total non-GAAP gross margin was essentially flat sequentially at 34.5% versus 34.3%. Installation stayed negative at -3.5%, services slipped to 21.4% from 22.0%, and electricity margin fell sharply.
- **Help below the operating line:** GAAP net income benefited from $22 million of interest income, $12.6 million of other income and a negligible tax provision.
The call kept the demand narrative firmly intact. Management said backlog is growing faster than revenue and described capacity plans as "all dialing up." That includes expanded real estate in Fremont to prepare for capacity beyond 5 GW. New commercial fronts include:
- AEP's 700 MW carbon-capture-enabled project for Google;
- a conditional U.S. Army award through partner Indelible;
- first shipments into Texas;
- an emerging front-of-meter utility channel;
- Nebius's first 300 MW block in New Jersey, ready about five months after contract.
Management also said international wins are expected "soon." The guidance trajectory captures the momentum. The revenue outlook has climbed from $3.1-$3.3 billion in February to $4.4-$4.6 billion. The non-GAAP operating income outlook has more than doubled, to $960 million-$1.03 billion.
Bears do have legitimate ammunition, and most of it sits in working capital. Operating cash flow swung to -$27 million from +$226 million in Q2. Capex jumped to $153 million, putting free cash flow at roughly -$181 million and pulling cash down to $2.5 billion from $2.7 billion. Several balance-sheet lines grew quickly:
- Contract assets rose $430 million in the quarter.
- Inventory grew $170 million.
- Receivables rose $175 million.
- A new customer consideration asset, about $307 million combined, has appeared since year-end and deserves monitoring.
Customer deposits and deferred revenue have also surged, to roughly $754 million from $144 million at year-end, which supports management's demand claims. Year-to-date free cash flow remains positive at about $42 million. Still, Bloom stopped providing formal free-cash-flow guidance in Q2.
Several details also temper the Q4 outlook. Revenue growth is still strong but slowing sequentially, from about 42% in Q2 to 16% in Q3. The full-year gross margin target was held at roughly 34% despite higher revenue, which management attributed to mix, new-line startup costs and expediting. The implied fourth quarter of roughly $1.35-$1.55 billion is a wide range, and management said it hinges on the timing of a few year-end deliveries.
Investor sentiment improved meaningfully into the report, rising from -0.28 to -0.09. That is still slightly negative, which suggests the crowd had not fully embraced the story even after repeated raises. The stock entered earnings at $238.53. That is 30% above the open following the July report and about 9.6% above its 200-day moving average. However, shares sat 21.1% below their September 29 peak of $302.35, giving back a substantial portion of the inter-earnings rally. Sequential-growth and momentum trend readings are positive, while AVWAP remains negative. That mix fits a stock whose fundamentals have outrun its recent price action.
The bottom line is that Bloom's quarter strengthened the core thesis: demand, pricing power on product and operating leverage all improved, and guidance moved higher again. The open question is execution rather than demand. Working capital and capex are consuming cash, non-product margins are soft, and a lumpy fourth quarter will test whether the faster-growing backlog converts into cash as reliably as it converts into revenue.
Read our earnings preview for Bloom Energy Corporation: https://www.earningswhispers.com/article/BE/20557
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 1 hour | |
| 3 hours | |
| 4 hours | |
| 4 hours | |
| 4 hours | |
| 4 hours | |
| 4 hours | |
| 7 hours | |
| 15 hours | |
| 15 hours | |
| 17 hours | |
| 20 hours | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 |
