Rocket's Share Gains Face Their Toughest Test As Shrinking Mortgage Market Squeezes Revenue
Rocket Companies heads into its third-quarter report with a split personality. On its last call, management described what amounted to its best operating stretch in years: record purchase and refinance market share, the most profitable quarter in four years, and an expanded cost-savings target from the Mr. Cooper integration. In the same breath, it warned that the mortgage market would shrink sequentially for the first time since 2022 and guided revenue lower. The stock has sided firmly with the second half of that story, and the October 29 report, due after the close, will show whether execution can keep earnings moving up while the market moves down.
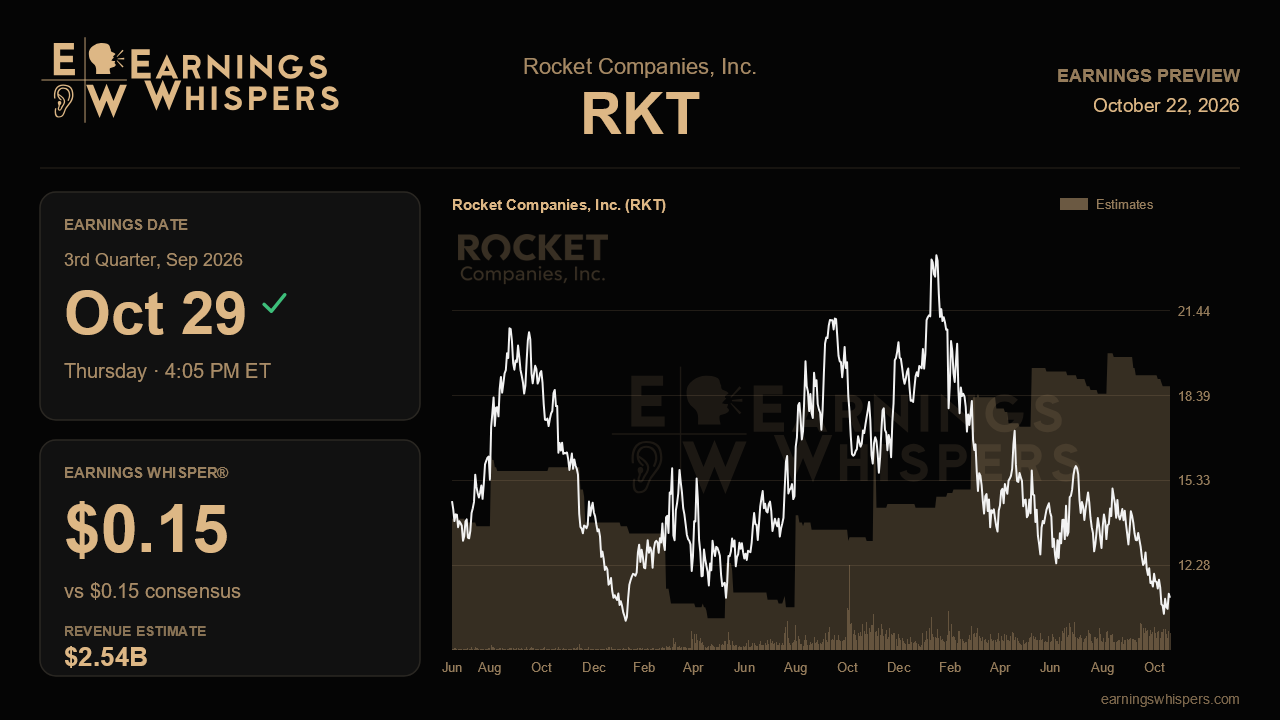
The Street is looking for adjusted earnings of $0.15 per share on revenue of about $2.54 billion. The Earnings Whisper sits right at $0.15, so there is no hidden optimism baked in beyond the published number. Revenue would be up roughly 58% from a year ago, but that comparison is flattered by a much larger company following the Mr. Cooper combination and says little about underlying demand. The more telling comparison is sequential: consensus implies a meaningful step down from the prior quarter's $2.78 billion. Management guided to $2.5 billion to $2.7 billion, well below the $2.79 billion analysts expected before that outlook, and the Street has since retreated toward the bottom of the range. That positioning matters. Analysts are not betting on Rocket clearing its own guidance comfortably, which lowers the bar for revenue but also signals skepticism that the market stabilized after rates climbed to around 6.8%.
The interesting tension is on the earnings line. Expecting EPS to hold near recent levels on lower revenue is effectively a bet on cost discipline. Adjusted EBITDA margin climbed from 20% a year ago to 28% last quarter, and Cooper synergies running ahead of plan should keep pulling expenses down. If Rocket can sustain margins in the high 20s on a smaller top line, it validates the argument that the business is structurally more profitable than it was in prior cycles. If margins slip back toward the mid-20s, it suggests that last quarter's leverage depended more on volume than on durable cost savings.
Several operating signals will sharpen that read. Gain-on-sale margin, excluding correspondent, already eased to 311 basis points from 322, and a further slide would indicate Rocket is buying share with price in a weaker market. Market share itself is the key proof point: holding or extending the record 6.2% purchase share and 14.3% refinance share in a contracting market would confirm that the gains are competitive rather than cyclical. The Redfin attach rate, at 47% and closing in on management's 50% goal, and the servicing portfolio's share of refi closings are the clearest evidence that the acquired businesses are feeding the origination engine. Progress on the roughly $500 million synergy target, newer channels such as Compass and RocketPro brokers, and any update on whether the $320 billion of servicing at rates above 6% is generating refinance activity round out the checklist.
Sentiment has warmed slightly, rising to 11.7% bullish from 5.5% before the last report, but remains muted. The stock tells a harsher story, down nearly 22% since the prior report while the S&P 500 was flat. At $11.11, shares trade well below the 200-day moving average of $15.11 and closer to the post-earnings low of $10.18 than the high of $15.18, a range that sits entirely beneath the prior quarter's.
That discount puts the central question in plain view. Investors already accept that the mortgage market is shrinking; what they need to learn is whether Rocket's share gains and cost savings can hold earnings steady anyway. Stable margins and sustained share would argue the selloff priced in too much cyclical pain. Margin erosion paired with guidance at the low end would suggest the market downturn is overwhelming the self-help story.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 57 min | |
| 2 hours | |
| 12 hours | |
| Oct-20 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 | |
| Oct-12 | |
| Oct-12 | |
| Oct-08 | |
| Oct-07 | |
| Oct-07 | |
| Sep-30 | |
| Sep-29 | |
| Sep-29 |
