American Express Beats And Lifts Its Reported EPS Outlook, But The Raise Leans On A One-Time Gain While Spend And Revenue Growth Cool
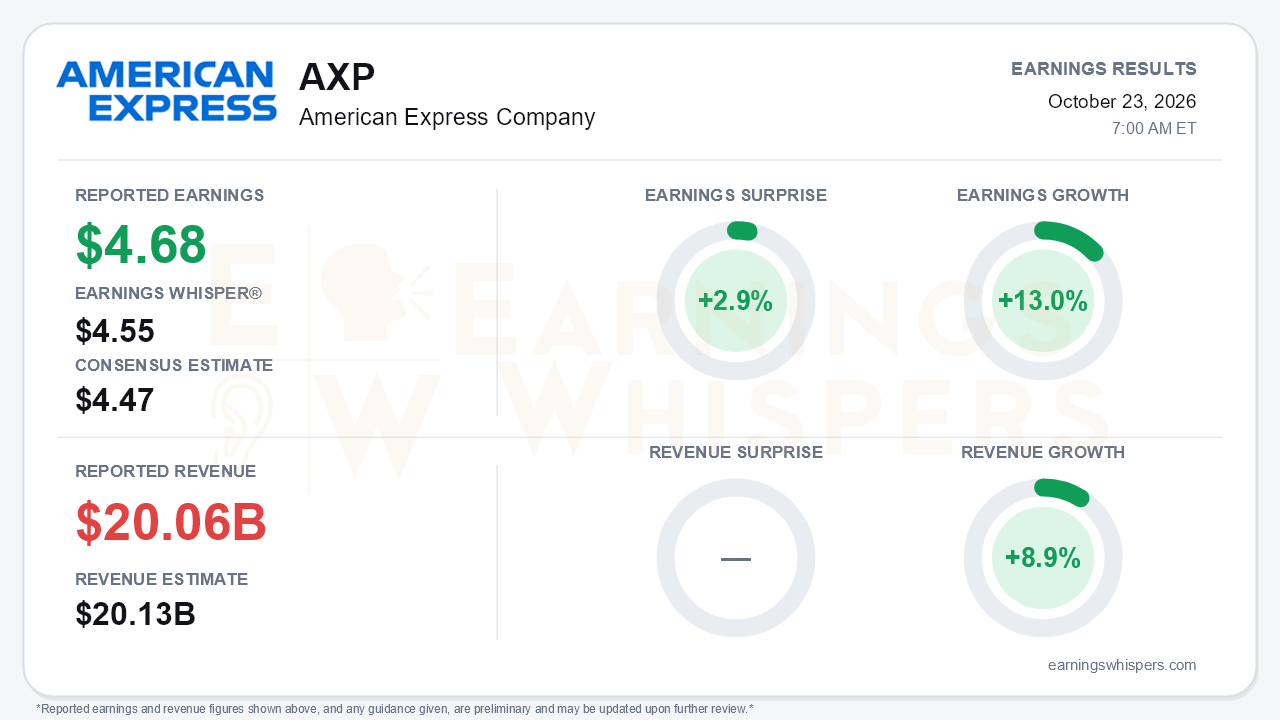
American Express delivered a clean bottom-line beat in the third quarter, but the details make it more of a margin-and-capital story than a growth story. The card issuer earned $4.68 per share, ahead of the $4.47 consensus and the $4.55 Earnings Whisper number, a 2.9% surprise. Earnings grew 13.0% year over year. Revenue of $20.062 billion rose 8.9% but slipped 0.3% below the $20.13 billion consensus. That is the central tension: profits are outrunning a top line that has now slowed for a second straight quarter, from 11% in Q1 to 10% in Q2 to 9% in Q3.
The guidance change deserves scrutiny. Management lifted its full-year 2026 reported EPS range to $18.30-$18.60, the first increase after the $17.30-$17.90 range had been held through Q4 FY25, Q1, and Q2. Most of that lift traces to the closed sale of the company's Global Business Travel Group stake, which contributed a $1.11 per-share gain that was partly reinvested. The adjusted range of $17.60-$17.90 sits inside the old range at its upper end. So the outlook was raised on a reported basis and narrowed on an underlying basis, which squares the call's upbeat framing with the narrowing characterization. The quarter also absorbed several items that cut the other way:
- a $336 million restructuring charge eliminating roughly 5% of global positions;
- increased legal reserves worth $0.51 per share, including an unrelated anticipated settlement;
- a $211 million reserve release tied to CECL model enhancements.
Investors looking for organic acceleration in the guide will not find it. The full-year revenue growth target of about 10%, raised in Q2, was only reaffirmed.
Beneath the headline, spending decelerated broadly from Q2's peak:
- Total billed business grew about 8%, versus 9.4% FX-adjusted in Q2.
- U.S. consumer spend slowed to 9.4% from 11%.
- International billings eased to 11% from 12-13%.
- Commercial spend grew just 3% reported, or 5% excluding co-brand exits.
- Net interest income growth cooled to 10% from 11-12%, partly because of those exits, which management said shaved about a point from revenue growth.
The offsets are real, though. Net card fee growth inflected as promised to 17% FX-adjusted from 15.4% in Q2. Platinum spend retention held at 99% a year after the product refresh. A record 76% of new accounts came on fee-paying products. Credit remains a standout: delinquencies have held at 1.2-1.3% for 15 quarters, and write-offs rose just 3% against 10% NII growth. The variable customer engagement expense ratio edged down to 44.3%, and management expects VCE growth to moderate significantly in Q4 as the Platinum refresh is lapped. Underlying operating expenses rose only 3%.
The call preserved a credible long-term growth narrative. Management pointed to:
- an exclusive Airbnb partnership bringing more than 1 million listings into Amex Travel;
- deeper OpenAI and Perplexity integrations and frameworks for agentic payments;
- network deals with mid-sized issuers such as Bread Financial and Synchrony;
- a new business savings account and corporate expense tools;
- a Graphite card running ahead of expectations.
But bears have legitimate ammunition. The OCC issued a consent order and civil money penalty that will require ongoing remediation and controls spending. Management stressed there is no asset cap and no impact on 2027 guidance. Marketing growth jumped to 11% from 6% in Q2, a sign the premium-card arms race with Chase, Citi, and Capital One is getting more expensive. The Visa/Mastercard settlement could also broaden merchant surcharging or honor-all-cards changes.
The market setup is more muted than the beat implies. Shares closed at $325.17 on the eve of the report, essentially flat (-0.3%) from the $326.12 open after the July release. They sat just 0.8% below the 200-day moving average of $327.90. The stock has round-tripped during the quarter. It peaked at $352.49 on August 5 and fell to $297.20 on October 1, then recovered to roughly the middle of that range: 7.8% off the high and 9.4% above the low. Investor sentiment improved only slightly, from 0.0529 to 0.0725, and remains barely positive. Earnings Whispers trend signals are mostly positive on sequential growth and momentum, but the price trend itself remains negative, consistent with a stock that has gone nowhere despite solid earnings.
The bottom line is that American Express is executing well on the levers it controls: fees, credit, expense discipline, and capital redeployment. However, the headline guidance raise is mostly a one-time gain, and the underlying revenue and spend trajectory is decelerating. With a new regulatory overhang and rising competitive spending, the next leg for the stock likely depends on whether spend growth stabilizes in Q4 rather than on another earnings beat.
Read our earnings preview for American Express Company: https://www.earningswhispers.com/article/AXP/20600
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 2 hours | |
| 2 hours | |
| 2 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 4 hours |
American Express Becomes the Latest Company To Announce Massive Layoffs Over the AI Boom
AXP
International Business Times
|
| 4 hours | |
| 4 hours | |
| 4 hours | |
| 4 hours | |
| 4 hours | |
| 4 hours |
